


Zhejiang Leapmotor Technology (SEHK:9863) recently signed a Vehicle Sales and Services Framework Agreement for 2026 with dealer partner Mr. Fu Yiqin, setting a RMB 250 million annual cap on related transactions.
The Vehicle Sales and Services Framework Agreement lands at a time when Zhejiang Leapmotor Technology’s short-term share price return has been positive, with a 1-day gain of 4.31% and a 7-day share price return of 6.26%. However, the year-to-date share price return has declined 26.76% and the 1-year total shareholder return is down 41.07%, while the 3-year total shareholder return of 7.40% points to a mixed longer-term picture and suggests recent momentum is rebuilding from a weaker base.
Scan how Zhejiang Leapmotor Technology fits into the wider opportunity set by comparing it with a hand picked 179 high quality undervalued stocks that may also be rebuilding momentum from weaker recent returns.
Zhejiang Leapmotor Technology now trades at a steep discount to both fair value estimates and analyst targets after a sharp share price rebound. Is the market being prudently cautious, or is it mispricing that gap in plain sight?
Most Popular Narrative: 42% Undervalued
The most followed valuation narrative for Zhejiang Leapmotor Technology points to a fair value of HK$63.06, well above the last close at HK$36.30. This frames the current discount as driven by how investors weigh growth against execution risk.
International expansion (leveraging Stellantis and FAW partnerships) in multiple regions with localized production and distribution (over 600 overseas outlets, production in Malaysia/Europe starting 2026, leadership in overseas start up exports) increases volume potential and diversifies revenue streams, while regulatory tailwinds (carbon credits, EV incentives) drive additional non auto and auto revenue.
See why 4 investors see Zhejiang Leapmotor Technology as 42% undervalued.
Result: Fair Value of HK$63.06 (UNDERVALUED)
Still, the Zhejiang Leapmotor Technology story can break if intense EV competition in China pressures pricing or if overseas partnerships dilute margins more than analysts currently factor in.
Find out about the key risks to this Zhejiang Leapmotor Technology narrative.
Another View: High Multiple Signals Caution
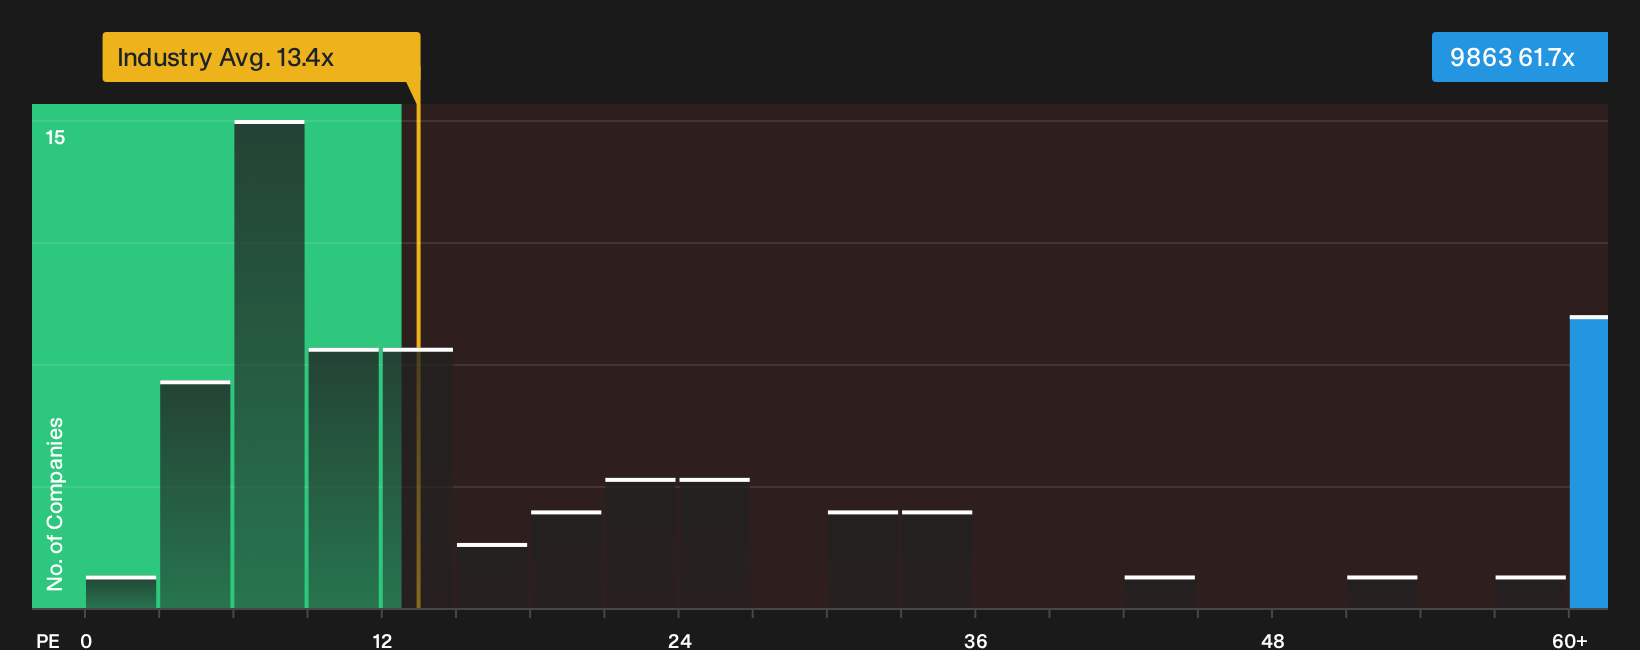
The earlier fair value narrative presents Zhejiang Leapmotor Technology as 42% undervalued, yet the current P/E of 61.7x tells a very different story. That multiple is far above the Asian Auto industry at 13.4x, the peer average at 7.8x, and even the fair ratio of 16.9x that the market could move towards. If sentiment cools and that gap closes toward the fair ratio, what might that imply for anyone buying purely on the under-valuation story?
See what the numbers indicate about this price gap in our valuation breakdown, starting with a closer look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Zhejiang Leapmotor Technology can feel confusing, so move quickly to test the valuation, pressure test the risks, weigh the potential rewards for yourself, and then drill into the 3 key rewards.
Looking for more Zhejiang Leapmotor Technology style ideas?
If Zhejiang Leapmotor Technology has sharpened your focus on price, risk and quality, use that momentum to scan other opportunities before they move without you.
- Target potential mispricing by running through the 179 high quality undervalued stocks that line up strong fundamentals with compressed market expectations.
- Build a sturdier core portfolio by checking the list of solid balance sheet and fundamentals (202 results) so you focus on financially resilient businesses first.
- Hunt for under-the-radar opportunities through the 619 high quality undiscovered gems that combine quality metrics with relatively low investor attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com