


Diesel markets are tight, Brent crude is holding above $100 a barrel, and governments are weighing fresh oil stock releases. This puts the Integrated Oil & Gas Majors screen firmly in focus. Pricing power, refining exposure, and balance sheet strength suddenly matter more than headlines. This article walks through 3 stocks tied to these pressures and explains how the same backdrop could either help or hurt your portfolio positioning.
The three Integrated Oil & Gas Majors highlighted below are only a starting sample, and the full screen pulled out 47 more large caps with equally compelling stories that are not covered here.
Head straight into the Integrated Oil & Gas Majors screener to identify, compare, and analyze the candidates that best fit your own highest conviction view of the sector.
EnQuest (LSE:ENQ)
Overview: EnQuest is a London based oil and gas producer focused on North Sea and Malaysian fields, giving the screener upstream exposure.
Operations: EnQuest generates about US$1.1b from Oil & Gas Exploration & Production, mainly from North Sea and Malaysian assets.
Market Cap: £529 million
EnQuest taps into the Integrated Oil & Gas Majors theme by offering direct North Sea production exposure that responds quickly to higher crude and diesel prices. This is relevant when supply interventions are on the table and upstream barrels help underpin the wider value chain.
Enhanced Oil Recovery (EOR) initiatives at the Kraken field have the potential to add 30 million to 60 million barrels of oil, which could significantly boost EnQuest's reserves and future production levels, positively impacting revenue and earnings.
What happens to EnQuest’s margin profile if a single key pressure on its funding costs moves in the wrong direction?
If that funding lever starts to move, read the full narrative for EnQuest to see how EnQuest’s risk, refinancing options and upside potential could be decoupling.

Etablissements Maurel & Prom (ENXTPA:MAU)
Overview: Etablissements Maurel & Prom is a Paris headquartered upstream oil and gas producer focused on oil and gas fields across Africa and Venezuela.
Operations: Etablissements Maurel & Prom generates about $506 million from Oil Operation, $79 million from Gas Production, $64 million from Other, and $6 million from Drilling.
Market Cap: €1.63 billion
Etablissements Maurel & Prom ties neatly into the Integrated Oil & Gas Majors theme as a crude focused producer. Its diversified fields feed into a refining system currently shaped by tight diesel supplies and elevated Brent prices.
The heavy dependence on Venezuelan reserves and production, with about half of 2P reserves and a large part of expected growth tied to a new OFAC license, leaves revenue and earnings vulnerable to any change in sanctions policy, license terms or local legal frameworks.
The real swing factor for Etablissements Maurel & Prom is what happens if a single external decision reshapes how much crude actually moves.
That external decision is only the starting gun, and the full narrative for Etablissements Maurel & Prom explains how shifting sanctions risk could be masking an opportunity for Etablissements Maurel & Prom.
Ithaca Energy (LSE:ITH)
Overview: Ithaca Energy is a London based producer focused on developing and operating oil and gas fields across the UK North Sea.
Operations: Ithaca Energy generates about US$3.2b from oil and gas exploration, development and production activities, entirely from the North Sea.
Market Cap: £4.7b
Ithaca Energy fits into this majors focused screen as a sizeable North Sea upstream player. Its cash flows are closely tied to higher crude pricing and tight refined fuel markets, putting real operating heft behind a theme that leans on scale and financial resilience.
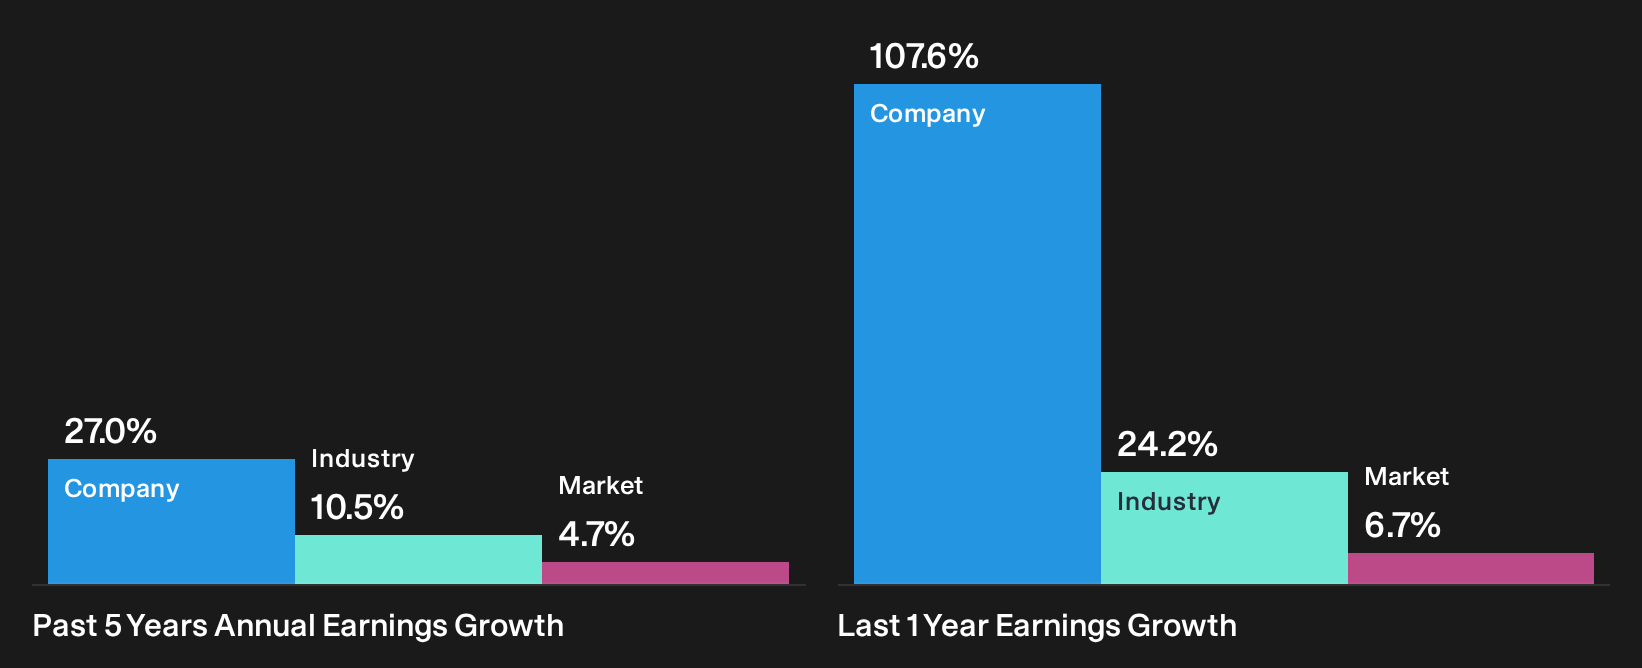
Strong production growth, driven by both organic performance improvements (such as increased production efficiency, debottlenecking, maintenance programmes, and newly sanctioned wells) and recent accretive acquisitions (notably expanded stakes in Seagull and Cygnus), could materially increase revenues and support higher earnings potential.
The real test for Ithaca Energy is what happens to that earnings potential if a single policy or tax assumption shifts against it.
If that tax risk is the hinge, the full narrative for Ithaca Energy shows how Ithaca Energy’s story could still be accelerating on production, deals and policy shifts.

Seeking Alternatives Before The Crowd?
Fresh themes move fast, and the best breakout stories rarely stay under the radar for long. Track what is flying or quietly dropping while it matters, and act while opportunities are still emerging.
- Spot cash generative outliers early by scanning the 39 profitable AI stocks that aren't just burning cash before the momentum narrative fully builds and early entry points get crowded.
- Track potential haven plays with the 1 dividend fortresses while yields and balance sheet strength still look mispriced and income opportunities have not been fully caught by the crowd.
- Hunt for future supply pinch winners using the 33 best rare earth metal stocks before demand stories gain full speed and valuations start moving on sentiment alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com