


Curtiss-Wright (CW) has kicked off a leadership reshuffle after long-serving Executive Vice President and Chief Financial Officer K. Christopher Farkas opted to retire, with Senior Vice President and Corporate Controller Gary A. Ogilby stepping in as interim CFO.
Recent trading has been rough for Curtiss-Wright, with the share price at US$504.16 after declining 6.77% over the past week and 9.79% over the past month. A much steeper 90-day share price fall of 32.97% contrasts with a very strong 3-year total shareholder return of 146.42%. This suggests long-term momentum remains intact even as the market reassesses near term risks around leadership change and upcoming earnings.
Scan beyond Curtiss-Wright and see how other engineers of record in complex industrial and defense markets are priced today with our curated list of solid balance sheet and fundamentals (25 results).
The sharp pullback in Curtiss-Wright looks harsh beside its multiyear shareholder gains and recent financial growth. Is this move signaling a change in the business, or a shift in sentiment that valuation can help clarify?
Most Popular Narrative: 36% Undervalued
Curtiss-Wright last closed at $504.16, while the most followed narrative pegs fair value at $786.25. This puts today’s slide against a much higher long-term value marker and makes the recent selloff look more like a sentiment reset than a change in the long-run story.
Backlog and order visibility remain central to the thesis, with total orders up 12% year to date against 9% sales growth, a book to bill above 1.2x, and backlog at US$4.3b. Taken together with raised 2026 sales, margin, and EPS guidance, these factors can support the idea that current pricing undervalues the potential operating leverage into revenue and net margin over the next few years.
See why 15 investors see Curtiss-Wright as 36% undervalued.
Result: Fair Value of $786.25 (UNDERVALUED)
Still, the Curtiss-Wright story hinges on big defense and nuclear contracts arriving on time, and on investors remaining comfortable with a richer P/E multiple.
Find out about the key risks to this Curtiss-Wright narrative.
Another View: Curtiss-Wright Through A Cash Flow Lens
A second yardstick tells a different story. Curtiss-Wright shares at $504.16 are trading above our DCF estimate of future cash flow value at $467.17, which points to the stock looking expensive on this model rather than undervalued. Which signal should carry more weight for you right now?
Before leaning on a single cash flow output, it can help to see how the SWS DCF model pieces together assumptions on growth, margins, and discount rates over time. Then compare that to your own expectations for Curtiss-Wright.Look into how the SWS DCF model arrives at its fair value.
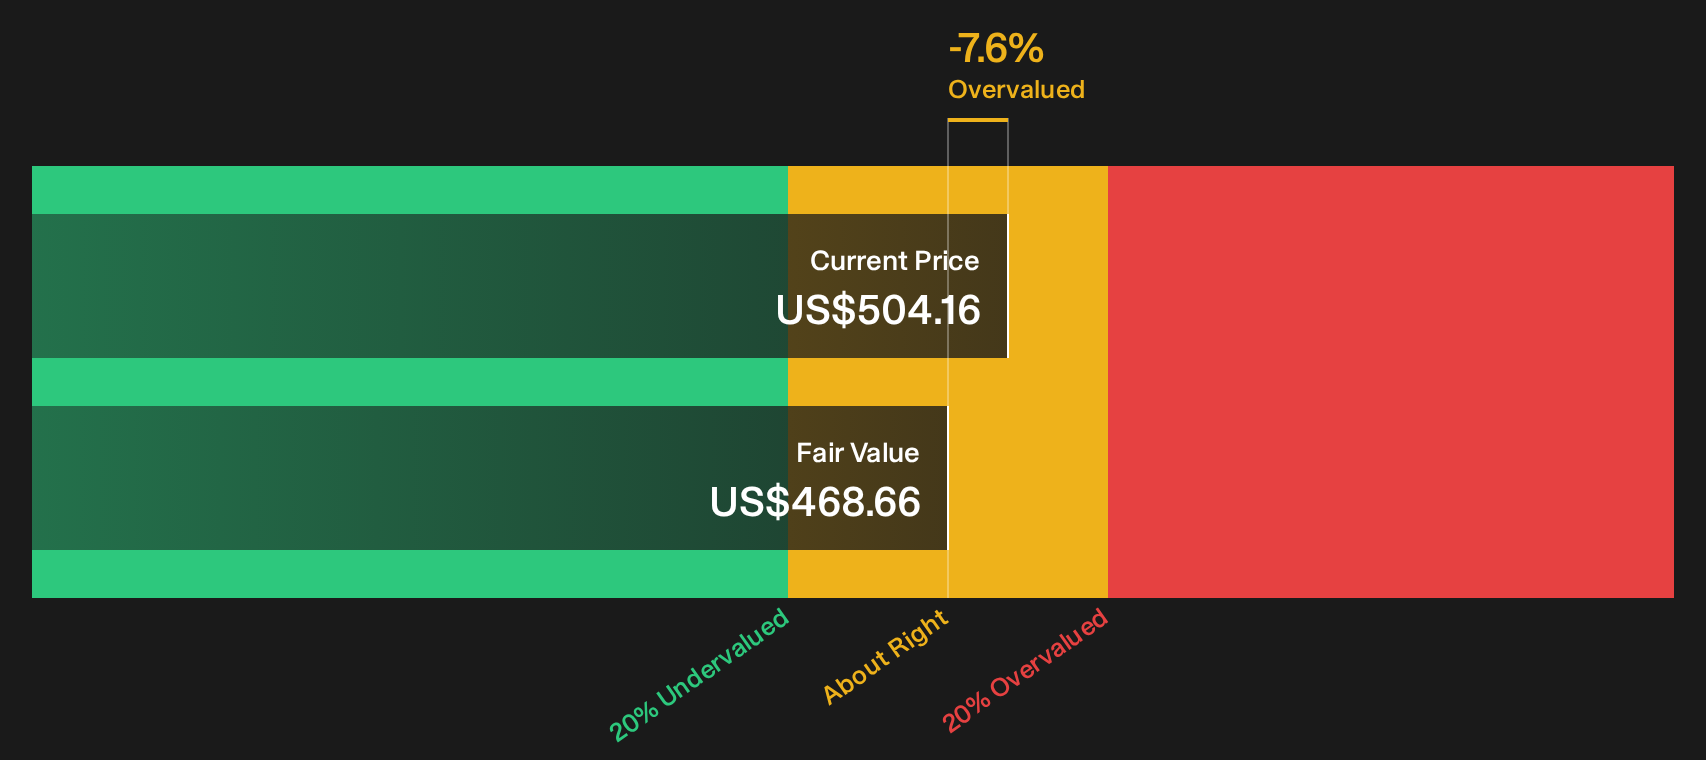
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Curtiss-Wright for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the mixed sentiment around Curtiss-Wright leave you on the fence? Consider moving quickly, reviewing the numbers, and pressure testing the optimism that hinges on 4 key rewards.
Looking For More Investment Ideas Beyond Curtiss-Wright?
If Curtiss-Wright has you thinking more broadly about opportunities, use this moment to scan other high quality ideas before the market moves without you.
- Target resilient themes first and sift through a 31 resilient stocks with low risk scores that can help anchor your portfolio when sentiment turns quickly.
- Hunt for quality at a discount and comb through a 20 high quality undiscovered gems that the wider market may not be paying close attention to yet.
- Prioritise fundamental strength and build your watchlist from a list of solid balance sheet and fundamentals (25 results) so you are prepared when prices reset.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com