


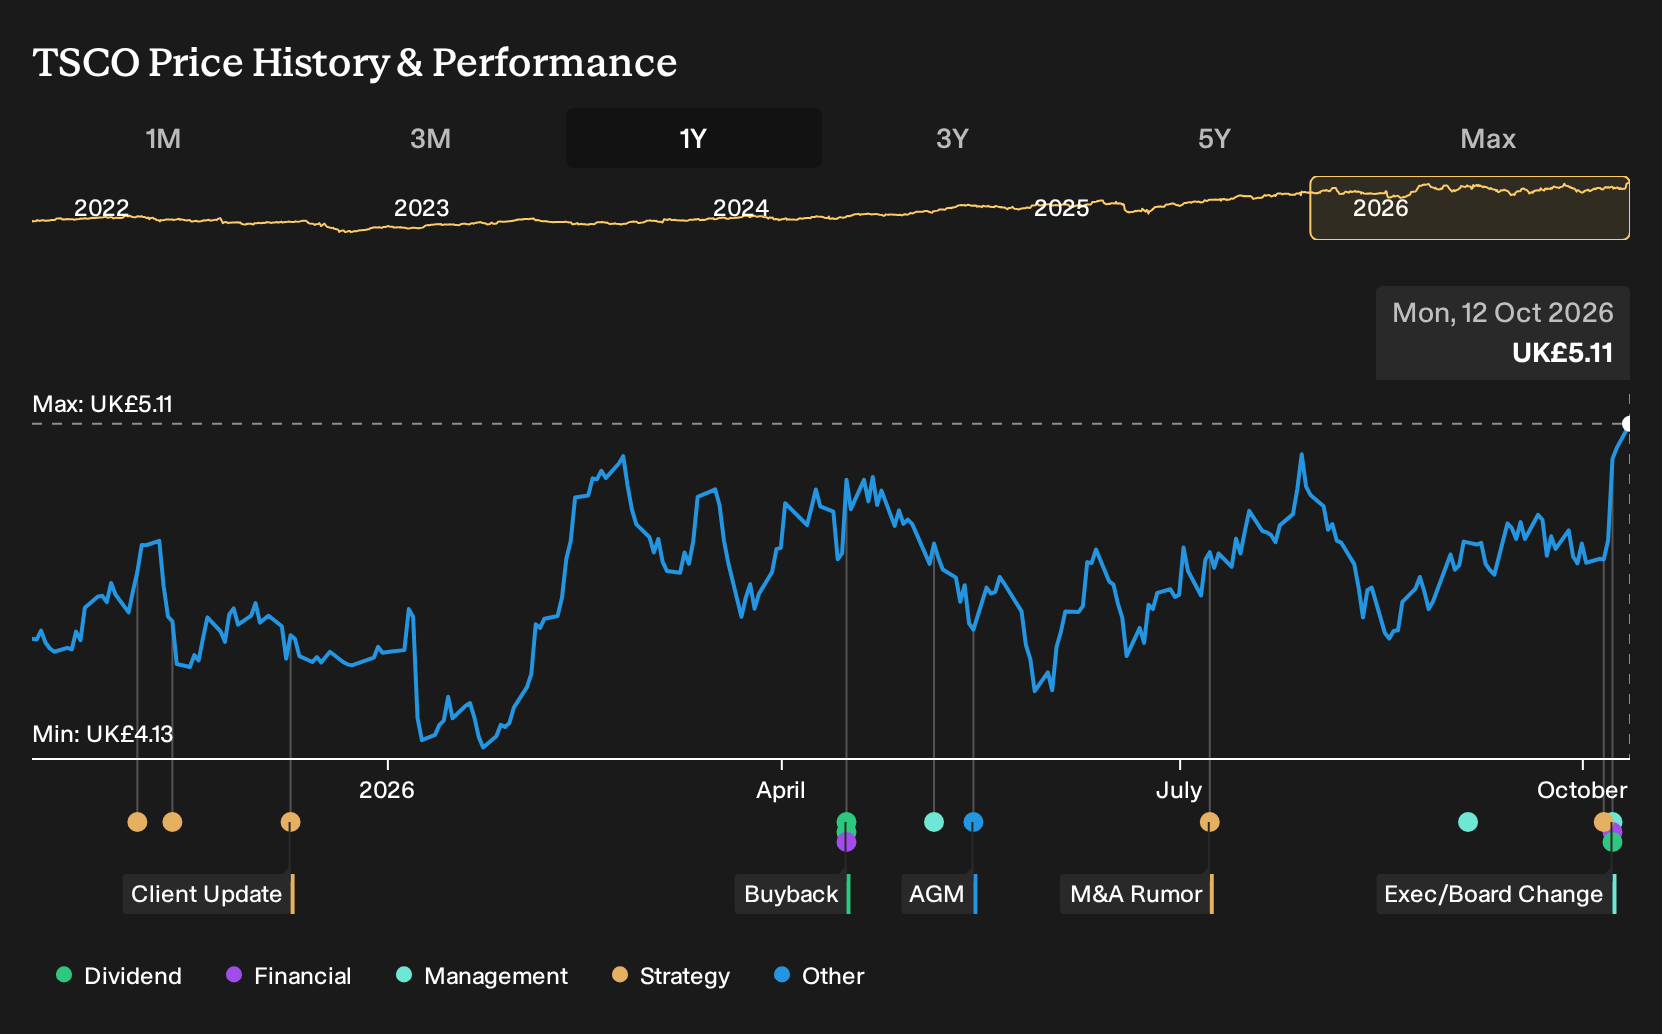
- Tesco reported half year 2026/27 results on 8 October 2026 with revenue of £37,353m, net income of £1,060m and higher earnings per share than a year earlier, alongside confirmation of completed £550m share buybacks covering 117,880,753 shares that represented 1.86% of the register.
- The Board approved an interim dividend of 5.05p per share, set at 35% of the prior full year payout, which indicates how Tesco is currently balancing cash returns with reinvestment after a period of cost efficiency efforts and new income stream development.
- This article considers how Tesco's investment narrative is affected by the stronger half year earnings and the higher first half dividend.
Tesco Investment Narrative Recap
Tesco still appeals to investors who believe a scale UK grocer can steadily grow profit by keeping prices sharp, running stores more efficiently and using data to earn extra, higher margin income. The latest half year numbers, with higher revenue, net income and earnings per share, broadly support that thesis without radically changing it.
The key short term swing factor remains how well Tesco holds margins while protecting its 27.8% market share in a weak volume backdrop, especially in pressured categories and convenience. Competitive intensity and softer traffic in smaller stores still look like the main operational risk right now.
The incoming appointment of Wendy Becker as a Non Executive Director looks most relevant for that margin and execution story. Investors are getting a board member who chairs Sony Group Corporation and leads remuneration at GSK, with a background at McKinsey, TalkTalk, Vodafone and as CEO of Jack Wills.
That mix points to experience in consumer brands, telecom style pricing decisions and digital services, which are all areas Tesco leans on as it builds online grocery, rapid delivery and data monetisation. For shareholders watching cost discipline, executive incentives and long term capital allocation, board level oversight is an important, if gradual, catalyst to track.
Tesco's analyst narrative points to £79.6b in revenue and £2.4b in earnings by 2029, based on a forecast 2.0% yearly revenue growth rate and an earnings increase of £0.5b from current earnings of £1.9b.
Uncover why Tesco's fair value is essentially in line with its current price.
Exploring Other Perspectives
You are seeing three fair value views from the Simply Wall St Community, with Tesco estimates spread between £5.22 and £7.24 per share. Those private investor models sit alongside live questions around weaker UK grocery volumes, pressure in convenience formats and potential M&A around Majestic. All of these factors could influence how future cash flows are assessed, so explore several viewpoints before deciding where you land.
Explore 2 other Tesco fair value estimates, including one that suggests it could be worth just £5.22.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tesco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tesco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tesco's overall financial health at a glance.
Looking For More Ideas Beyond Tesco?
If Tesco has sharpened your focus on cash generation, dividends and balance sheet strength, it can be useful to compare those traits with other businesses that share similar qualities. The Simply Wall St Screener gives you a quick way to line up multiple candidates side by side and test how your investment checklist holds up across different sectors.
- If you want potential mispricing combined with quality fundamentals, start with a curated group of 7 high quality undervalued stocks that already clear basic balance sheet and cash flow hurdles.
- For investors who care most about getting paid while they wait, focus on companies in the 1 dividend fortresses that pair higher yields with an emphasis on resilience.
- When capital preservation comes first, filter for sturdier financial positions using the list of solid balance sheet and fundamentals (9 results) to see which businesses look built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com