


Renewed attention on Home BancShares (HOMB) has been sparked by its dividend profile, with a 3.26% yield that exceeds both the Banks - Southeast peer group and the broader S&P 500.
The renewed focus on income has come alongside fairly mixed price action, with Home BancShares trading at US$28.50 and posting a 1-year total shareholder return of 8.18% and a 3-year total shareholder return of 45.77%. This points to longer term momentum, which contrasts with a softer 30-day share price return of 4.9% and a modest 2.11% year to date share price gain.
Compare Home BancShares' income story with a curated 8 dividend fortresses that combines yield with balance sheet resilience.
After a strong three year run, but only a modest move so far in 2026, the real puzzle for Home BancShares now is whether most of the upside has already played out or if valuation still leaves room ahead.
Most Popular Narrative: 14% Undervalued
On the most followed valuation view, Home BancShares screens as underpriced, with a fair value of $33.25 against the recent $28.50 close, and that gap all hinges on how management executes its current playbook.
Expansion focused on accretive, non dilutive bank acquisitions such as Mountain Commerce Bank, which brought in about US$1.5b of loans and deposits and is expected to deliver annual cost savings of about US$5.5m to US$6m after the November 2026 conversion, can add to revenue and earnings growth.
Planned system conversion and integration of Mountain Commerce Bank in November 2026, with modeled cost saves of roughly 20% of its expense base, can support a lower efficiency ratio and higher net income as the full run rate flows through from 2027.
See why 2 investors see Home BancShares as 14% undervalued.
Result: Fair Value of $33.25 (UNDERVALUED)
Still, the Home BancShares story can be knocked off course if loan growth remains choppy or if future acquisitions deliver weaker than expected cost savings.
Find out about the key risks to this Home BancShares narrative.
Another View: What Market Comparisons Say About Home BancShares
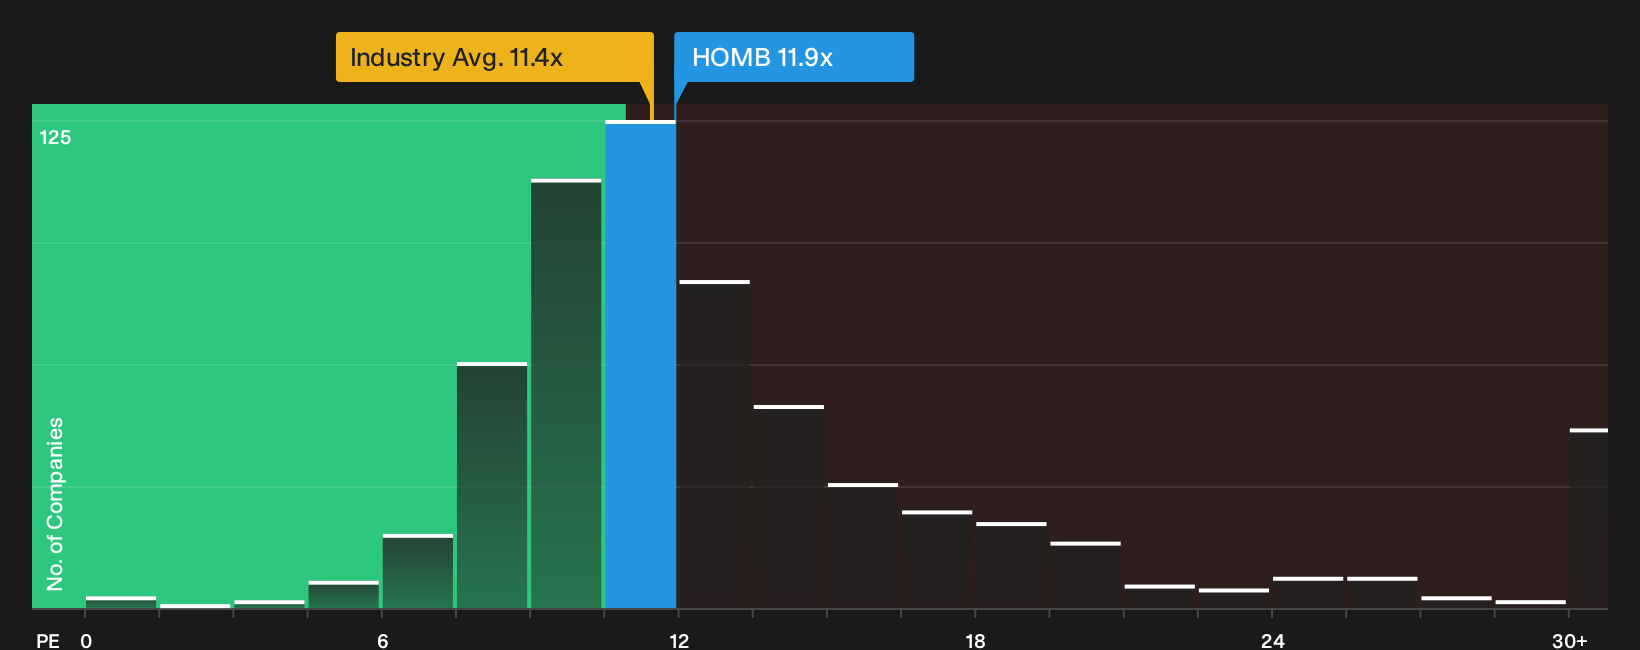
While the popular narrative has Home BancShares looking 14% undervalued on fair value estimates, the picture shifts when you just compare current pricing multiples. On a P/E of 11.9x, the bank trades slightly richer than the broader US Banks industry at 11.4x, yet cheaper than its direct peers at 13.5x. Against a fair ratio of 11.3x, the gap suggests investors are already paying a bit above the level the market could move toward, which raises the question of how much mispricing is really left on the table.
For a closer look at how that pricing stacks up against underlying earnings power, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of moving parts sit behind the mixed sentiment around Home BancShares, so weigh the income, valuation and execution risks yourself, then stress test your view against the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Home BancShares?
If Home BancShares has sharpened your focus on income and valuation, you can use that momentum to broaden your watchlist with a few targeted screeners that surface different types of opportunities.
Sharpen your hunt for potential value by scanning a curated set of companies with solid fundamentals in the 29 high quality undervalued stocks.
- Zero in on resilience first by running your filters through a 32 resilient stocks with low risk scores that highlights businesses with more defensive profiles and lower risk scores.
- Spot early potential by checking a focused pool of smaller stocks in the 11 elite penny stocks with strong financials that already show stronger balance sheets and financial quality.
- Aim for durability and financial strength by working through a list of solid balance sheet and fundamentals (25 results) that surfaces companies with healthier fundamentals backing their valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com