


Amidst the backdrop of geopolitical tensions and fluctuating energy prices, Asian markets have been navigating a complex economic landscape, with indices reflecting mixed performances. In this environment, identifying stocks with strong fundamentals becomes crucial as investors seek stability and potential growth opportunities.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Management SolutionsLtd | 7.61% | 23.78% | 29.72% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Kyosan Electric Manufacturing | 46.17% | 7.20% | 17.51% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Open Up Group (TSE:2154)
Simply Wall St Value Rating: ★★★★★☆
Overview: Open Up Group Inc., along with its subsidiaries, provides engineering dispatch services to manufacturers, construction contractors, and IT companies across Japan, the United Kingdom, and internationally with a market capitalization of approximately ¥169 billion.
Operations: The company generates revenue primarily from its Machinery and Electronics Segment at ¥66.74 billion and Construction Segment at ¥57.60 billion, with a smaller contribution from the IT Segment at ¥40.92 billion.
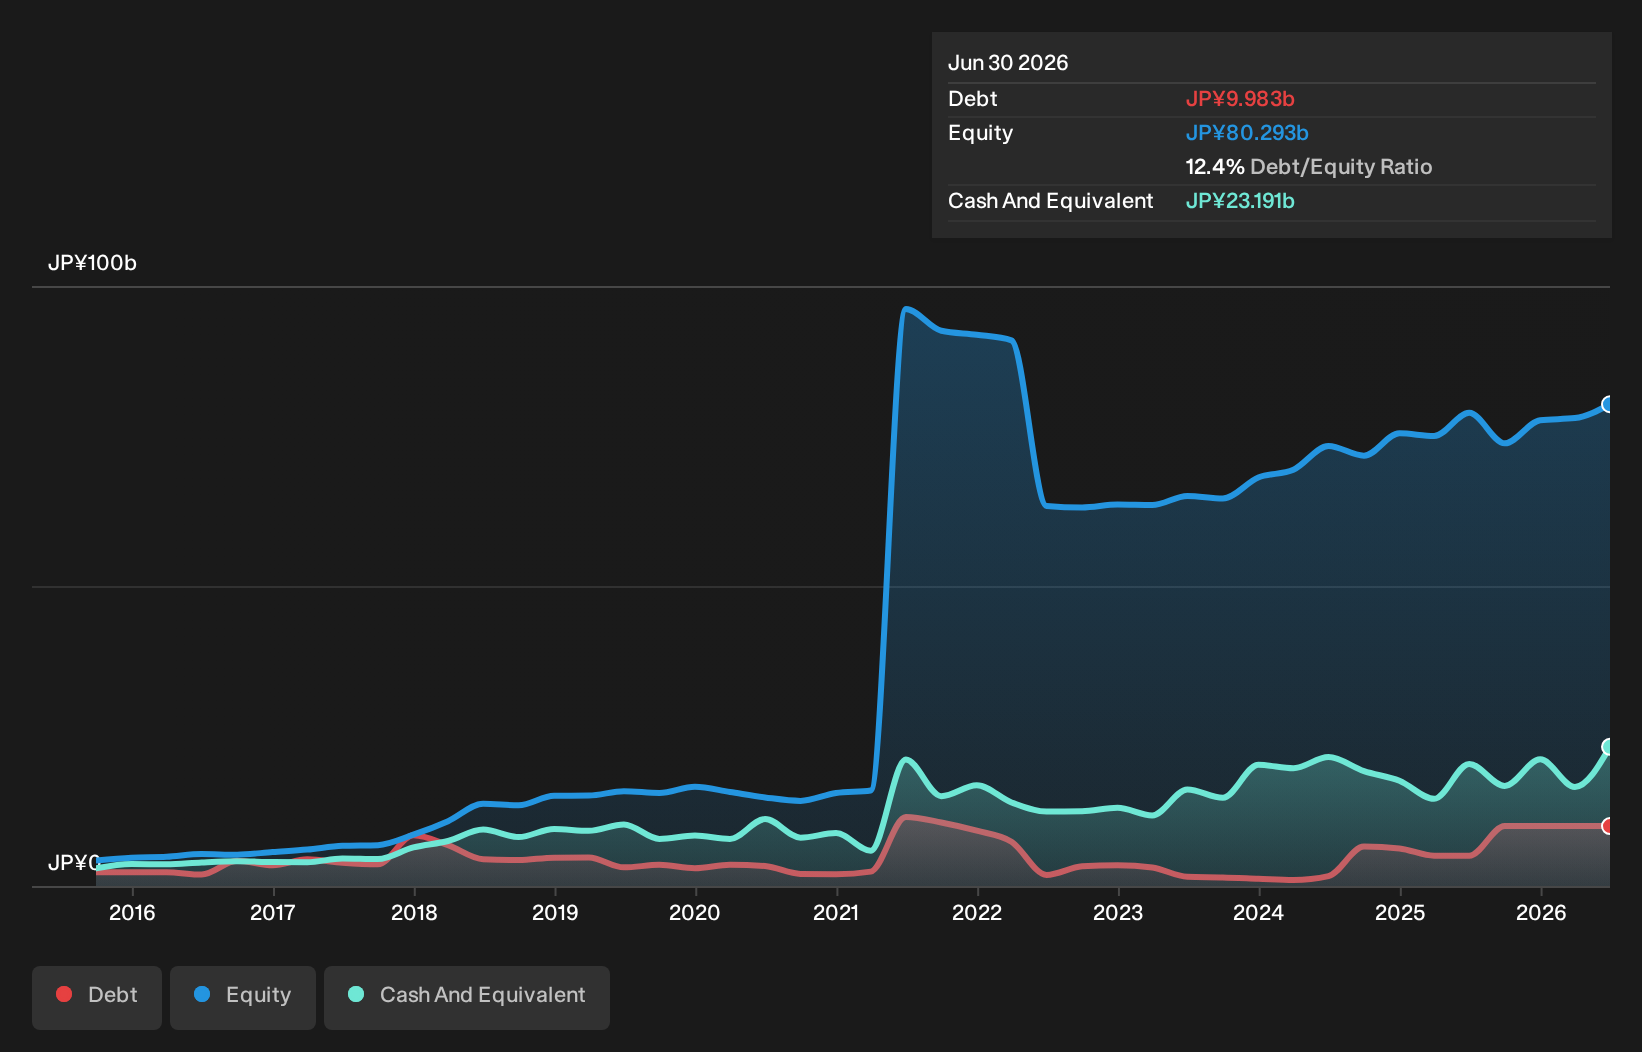
Open Up Group, a smaller player in the market, has seen its debt to equity ratio slightly rise from 12% to 12.4% over five years, yet it remains undervalued by trading at 46.1% below fair value estimates. The company is comfortably managing its debt with interest payments covered 141.6 times by EBIT and boasts high-quality earnings. Despite recent negative earnings growth of -5.8%, Open Up Group anticipates an annual growth rate of 8.55%. Recent leadership changes could impact strategic direction, while steady dividends reflect commitment to shareholder returns amidst evolving market conditions.
- Click here to discover the nuances of Open Up Group with our detailed analytical health report.
Review our historical performance report to gain insights into Open Up Group's's past performance.
Kitazato (TSE:368A)
Simply Wall St Value Rating: ★★★★★★
Overview: Kitazato Corporation specializes in the research, development, manufacturing, and marketing of medical devices and reagents for fertility treatment, with a market capitalization of ¥56.48 billion.
Operations: The primary revenue stream for Kitazato comes from its Medical Equipment Business, generating ¥11.53 billion.
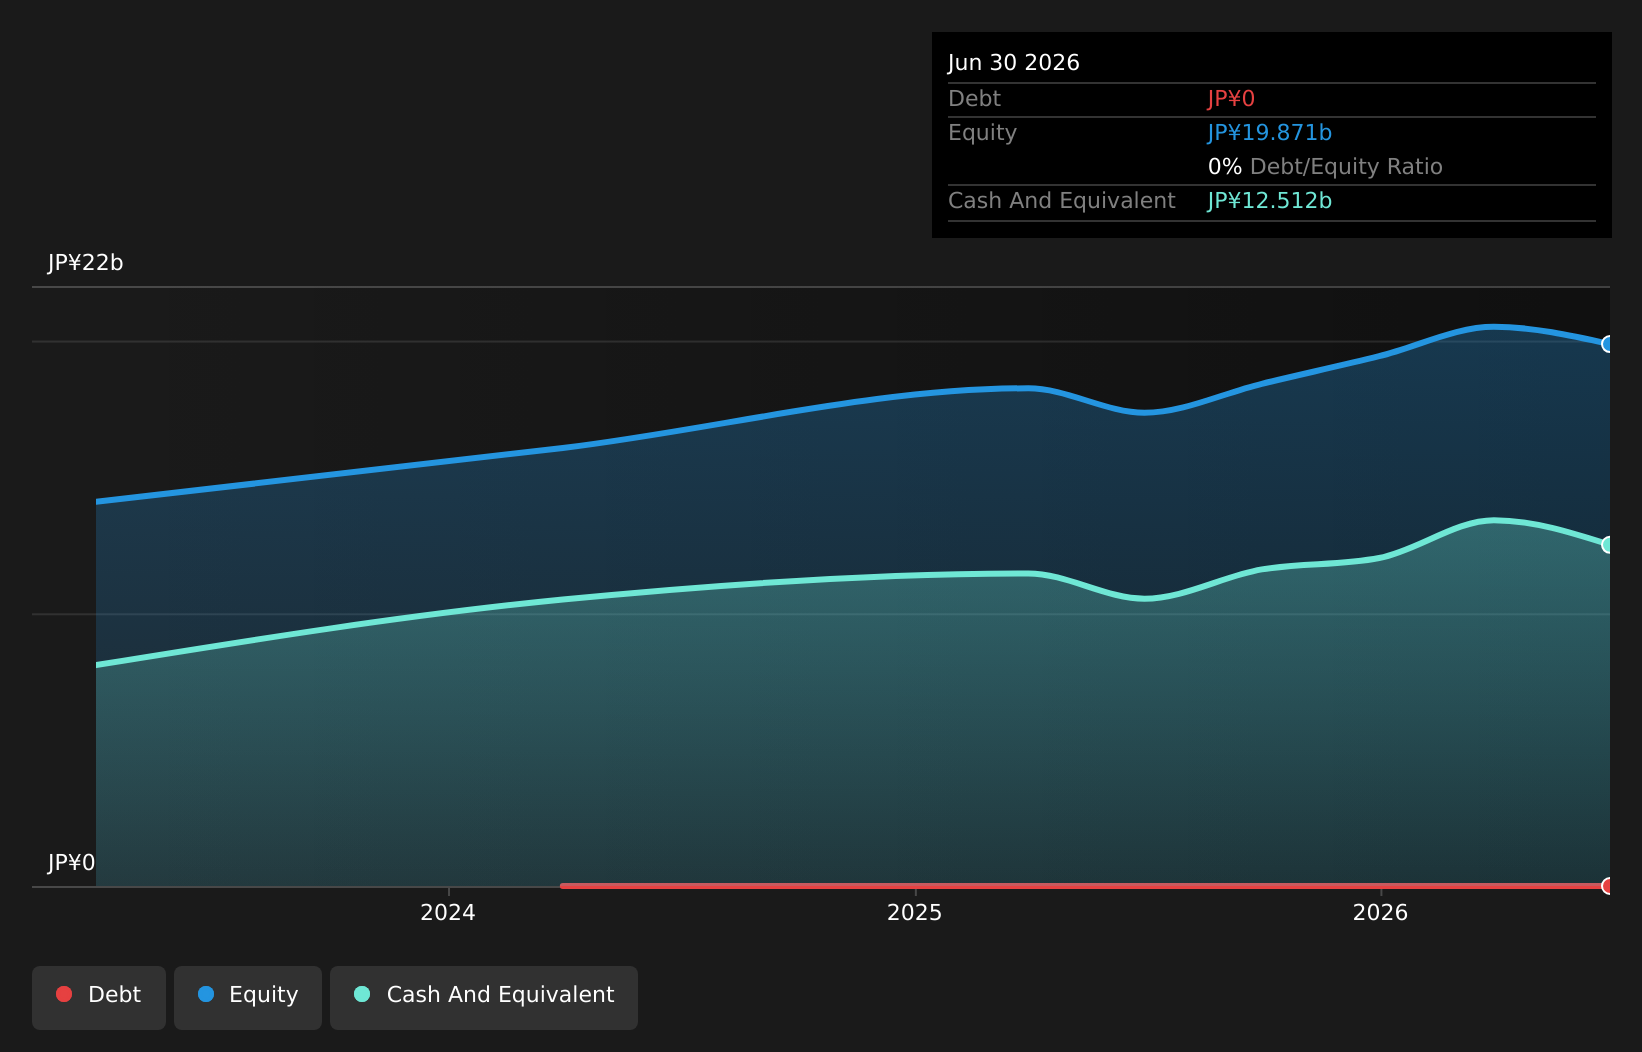
Kitazato, a promising player in the medical equipment industry, has shown impressive financial health with earnings growing by 12% over the past year, surpassing the industry's 4% growth. The company trades at a compelling 41.2% below its estimated fair value and boasts high-quality earnings. Kitazato remains debt-free for five years, reinforcing its robust financial position. Recent guidance suggests stable performance with expected net sales of ¥11.35 billion and operating profit of ¥6.12 billion for fiscal year ending March 2027. Despite maintaining dividends at ¥41 per share, Kitazato's future prospects seem optimistic given its strong fundamentals and market positioning.
- Click here and access our complete health analysis report to understand the dynamics of Kitazato.
Assess Kitazato's past performance with our detailed historical performance reports.
Eson Precision Ind (TWSE:5243)
Simply Wall St Value Rating: ★★★★★☆
Overview: Eson Precision Ind. Co., Ltd. is engaged in the production and sale of molds and consumer electronic components both in Taiwan and internationally, with a market capitalization of NT$16.94 billion.
Operations: Eson Precision Ind. generates revenue primarily from its Mold, Plastic, and Metal Products segment, amounting to NT$12.02 billion.
Eson Precision Ind. shines with its earnings growth of 27.5% over the past year, although it slightly trails the electronic industry average of 30.9%. The company is trading at a compelling value, being 79.3% below its estimated fair value, and boasts high-quality earnings with interest payments well-covered by EBIT at a remarkable 98.5 times coverage. Recent financials reveal robust performance; second-quarter sales reached TWD 3,213 million and net income climbed to TWD 258 million from TWD 196 million last year, reflecting resilience in operations despite challenges in matching industry growth rates fully.
- Dive into the specifics of Eson Precision Ind here with our thorough health report.
Explore historical data to track Eson Precision Ind's performance over time in our Past section.

Taking Advantage
- Unlock more gems! Our Asian Undiscovered Gems With Strong Fundamentals screener has unearthed 113 more companies for you to explore.Click here to unveil our expertly curated list of 116 Asian Undiscovered Gems With Strong Fundamentals.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com