


Tate & Lyle (LSE:TATE) has drawn fresh attention after reporting progress in its next generation sweetener programme with BioHarvest, alongside a cluster of new institutional disclosures under the UK Takeover Code.
Recent price action has been subdued, with Tate & Lyle’s 1-month share price return of 0.54% and 90-day gain of 0.45% sitting in the shadow of a much stronger year to date share price return of 52.86% and a 1-year total shareholder return of 50.91%.
Scan other ingredient makers and food specialists that may be seeing similar interest by running a focused screen of 5 high quality undiscovered gems that is aligned with the themes behind Tate & Lyle’s sweetener progress and fresh institutional disclosures.
The question now is whether Tate & Lyle’s sharp advance reflects a business quietly reshaped by new products and fresh capital on the register, or whether sentiment has simply run ahead of what the current valuation can justify.
Most Popular Narrative: 5% Overvalued
The most followed narrative currently pins Tate & Lyle’s fair value at £5.35, which sits slightly below the last close at £5.61. That gap is small, yet it frames a story where execution on earnings and margin targets needs to work hard just to keep the current valuation intact.
The analysts have a consensus price target of £5.35 for Tate & Lyle based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £6.15, and the most bearish reporting a price target of just £3.75.
See why 36 investors see Tate & Lyle as 5% overvalued.
Result: Fair Value of £5.35 (OVERVALUED)
Still, input cost deflation hitting regional sales, and any stumble integrating CP Kelco, could quickly challenge the idea that Tate & Lyle is only mildly mispriced.
Find out about the key risks to this Tate & Lyle narrative.
Another View: Tate & Lyle Through A Cash Flow Lens
The analyst target of £5.35 paints Tate & Lyle as slightly overvalued, yet the SWS DCF model points the other way. On that framework, the shares trade at a steep 67.9% discount to an estimated future cash flow value of £17.48, which is a very different story. Which signal do you trust more: the market’s current P/E or a long term cash flow track?
Look into how the SWS DCF model arrives at its fair value.
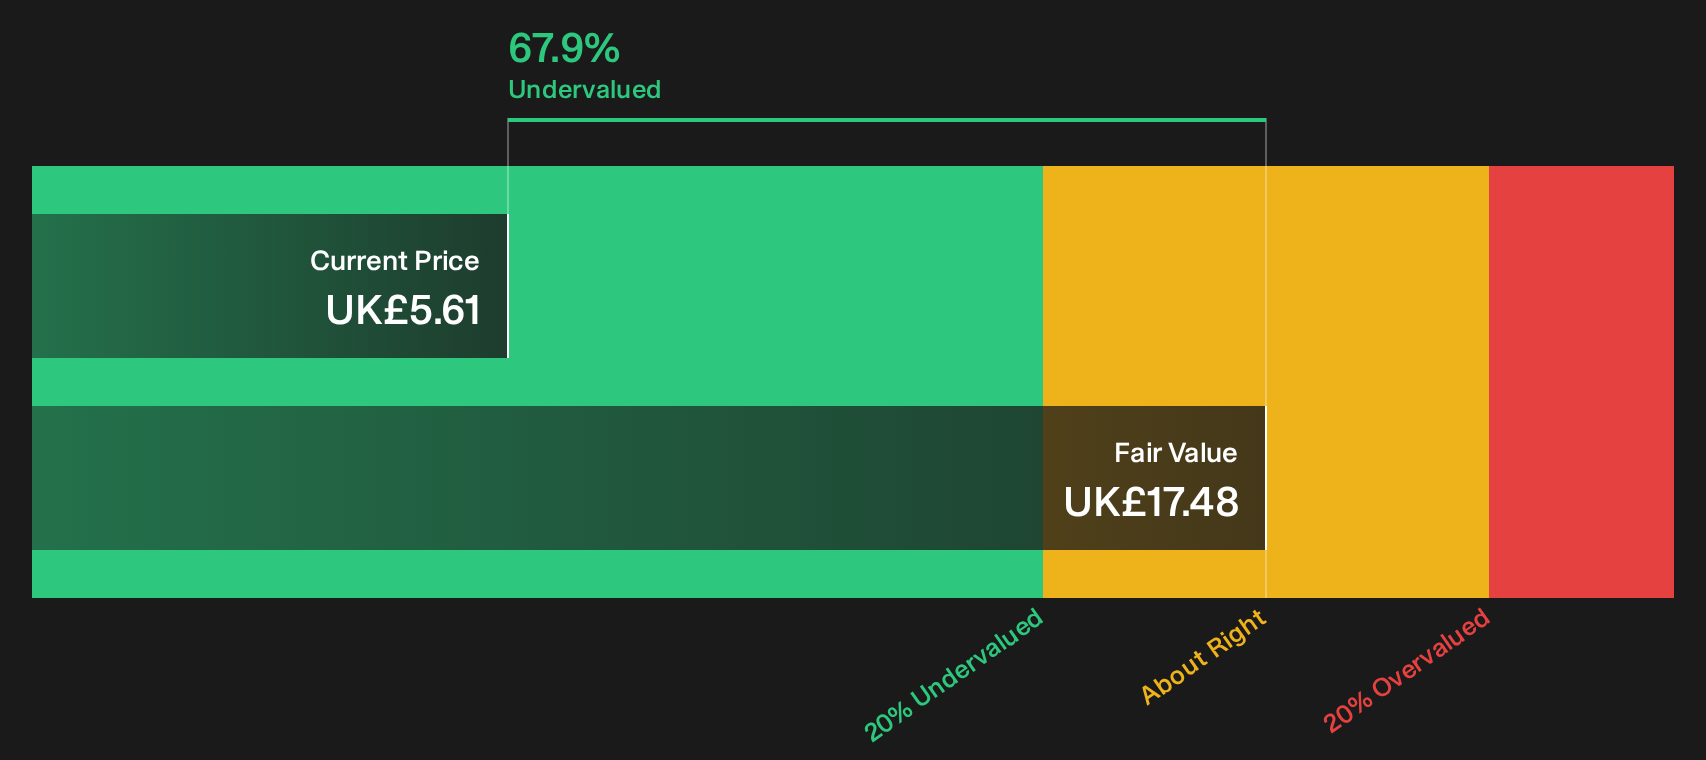
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tate & Lyle for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Tate & Lyle’s value can either paralyse you or push you to check the data yourself and move fast. To weigh the upside against the potential downsides in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more Tate & Lyle style ideas?
If you like how Tate & Lyle blends defensiveness with a clear story, do not stop here. Fresh opportunities often appear where most investors are not yet looking.
- Target income first by scanning a curated set of dependable payers through the 1 dividend fortresses.
- Filter for sturdier balance sheets and cleaner fundamentals with the focused list of solid balance sheet and fundamentals (9 results).
- Hunt for underfollowed opportunities with strong underpinnings using the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com