


The European market has experienced volatility recently, influenced by renewed Middle East tensions, a hawkish stance from the European Central Bank, and mixed economic data across major economies. Despite these challenges, small-cap stocks in Europe present intriguing opportunities for investors seeking value amid broader market fluctuations. Identifying promising small caps often involves looking at companies with strong fundamentals that can navigate the current economic landscape effectively.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Truecaller | 27.7x | 4.1x | 46.95% | ★★★★☆☆ |
| Volati | 9.7x | 0.2x | 38.61% | ★★★★☆☆ |
| Hanza | 31.5x | 1.3x | 38.08% | ★★★★☆☆ |
| Franchise Brands | 27.2x | 2.0x | 47.32% | ★★★★☆☆ |
| Saniona | 6.8x | 2.9x | 36.81% | ★★★★☆☆ |
| Nyab | 19.8x | 0.9x | 28.66% | ★★★☆☆☆ |
| Domino's Pizza Group | 14.6x | 1.2x | -0.33% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 21.48% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -202.58% | ★★★☆☆☆ |
| Linc | 11.9x | 12.3x | 35.57% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
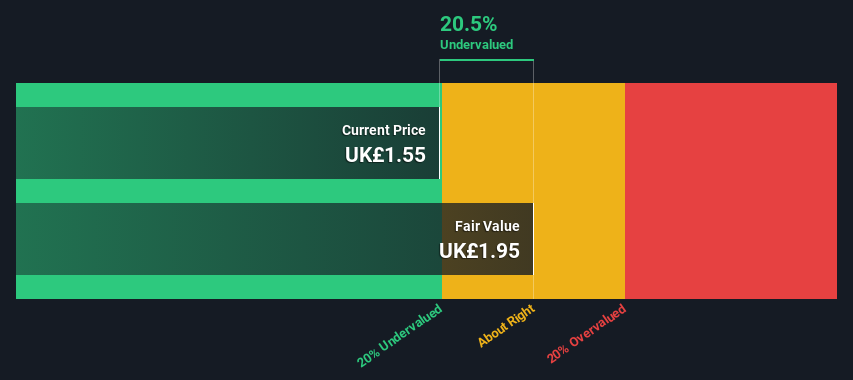
Franchise Brands (AIM:FRAN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Franchise Brands is a company that operates in various sectors including B2C services, software solutions through Azura, hydraulic hose replacement via Pirtek, and international filtration services with Filta International, alongside water and waste services; it has a market capitalization of £0.32 billion.
Operations: The company generates revenue primarily from Pirtek (£63.99 million), Filta International (£36.50 million), and Water & Waste Services (£44.57 million). Gross profit margin has shown variability, peaking at 62.90% in recent periods, indicating shifts in cost management or pricing strategies over time.
PE: 27.2x
Franchise Brands, a European small-cap company, recently reported strong financials for the half year ending June 2026, with sales increasing to £75.6 million from £70.37 million and net income rising to £6.13 million from £4.25 million year-on-year. This growth is complemented by insider confidence; Stephen Hemsley purchased 72,500 shares valued at approximately £84,200 in July 2026. The company also announced a 9% increase in its interim dividend to 1.25 pence per share, reflecting optimism in future earnings potential despite relying solely on external borrowing for funding.
- Click here and access our complete valuation analysis report to understand the dynamics of Franchise Brands.
Gain insights into Franchise Brands' past trends and performance with our Past report.
Inwido (OM:INWI)
Simply Wall St Value Rating: ★★★★★☆
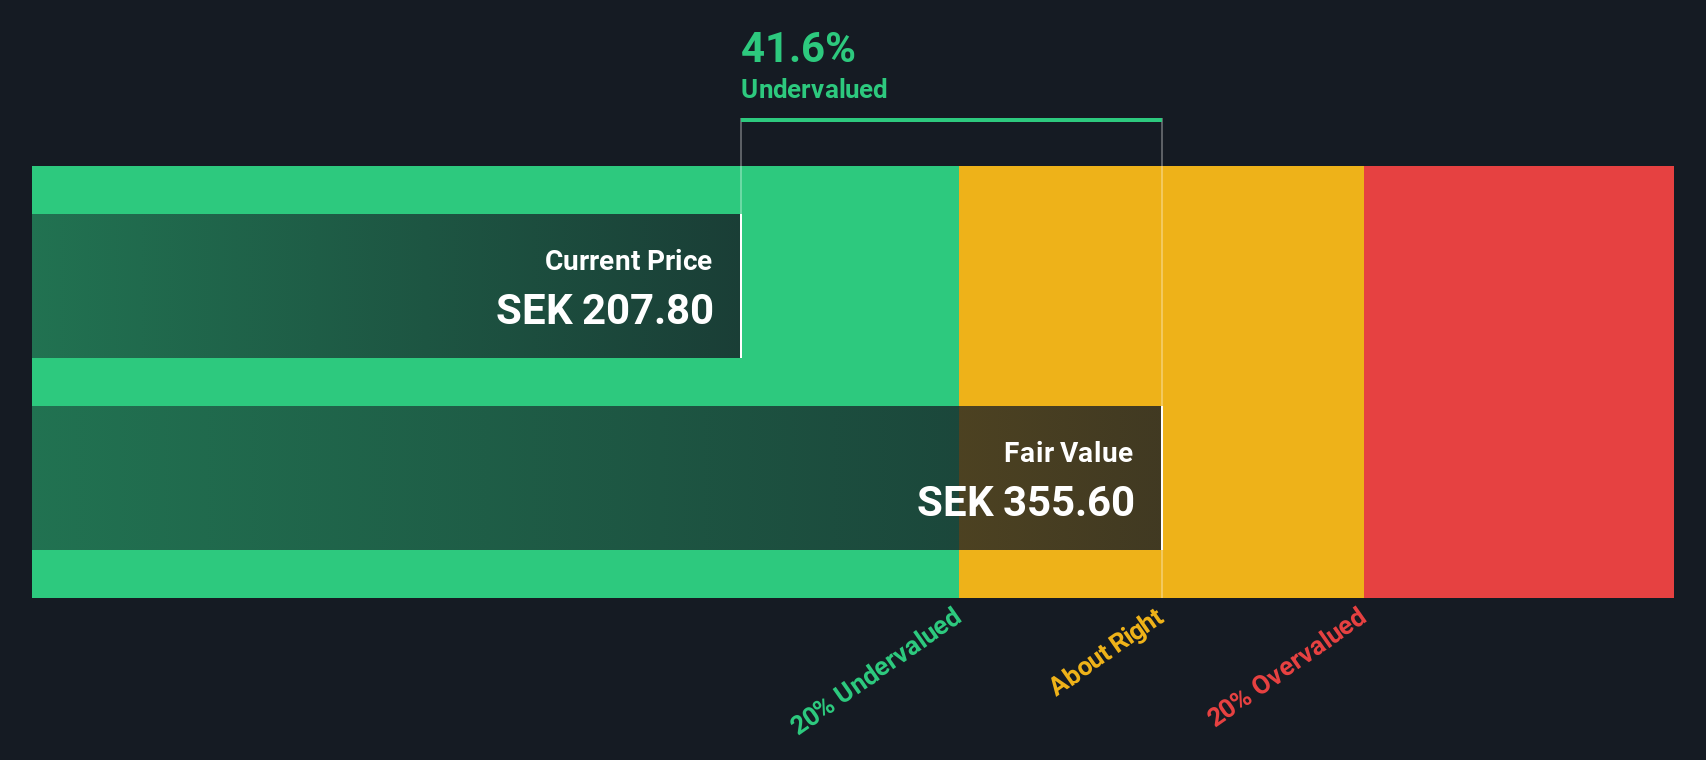
Overview: Inwido is a leading European provider of windows and doors, operating across various segments including East, West, E-Commerce, and Scandinavia with a market capitalization of approximately SEK 6.20 billion.
Operations: The company's revenue streams are primarily derived from its operations in East, West, E-Commerce, and Scandinavia. Over recent periods, the gross profit margin has shown fluctuations between 24.31% and 28.32%. Operating expenses have consistently included sales & marketing and general & administrative costs as significant components.
PE: 20.8x
Inwido, a company with a focus on external borrowing for funding, presents an intriguing investment case in the European small-cap space. Their earnings have shown growth, with second-quarter sales reaching SEK 2.72 billion and net income rising to SEK 197 million. Insider confidence is evident as Anders Wassberg significantly increased their holdings by 215% recently. Despite high debt levels, Inwido's forecasted earnings growth of over 18% per year suggests potential for future expansion.
- Unlock comprehensive insights into our analysis of Inwido stock in this valuation report.
Gain insights into Inwido's historical performance by reviewing our past performance report.
Linc (OM:LINC)
Simply Wall St Value Rating: ★★★☆☆☆
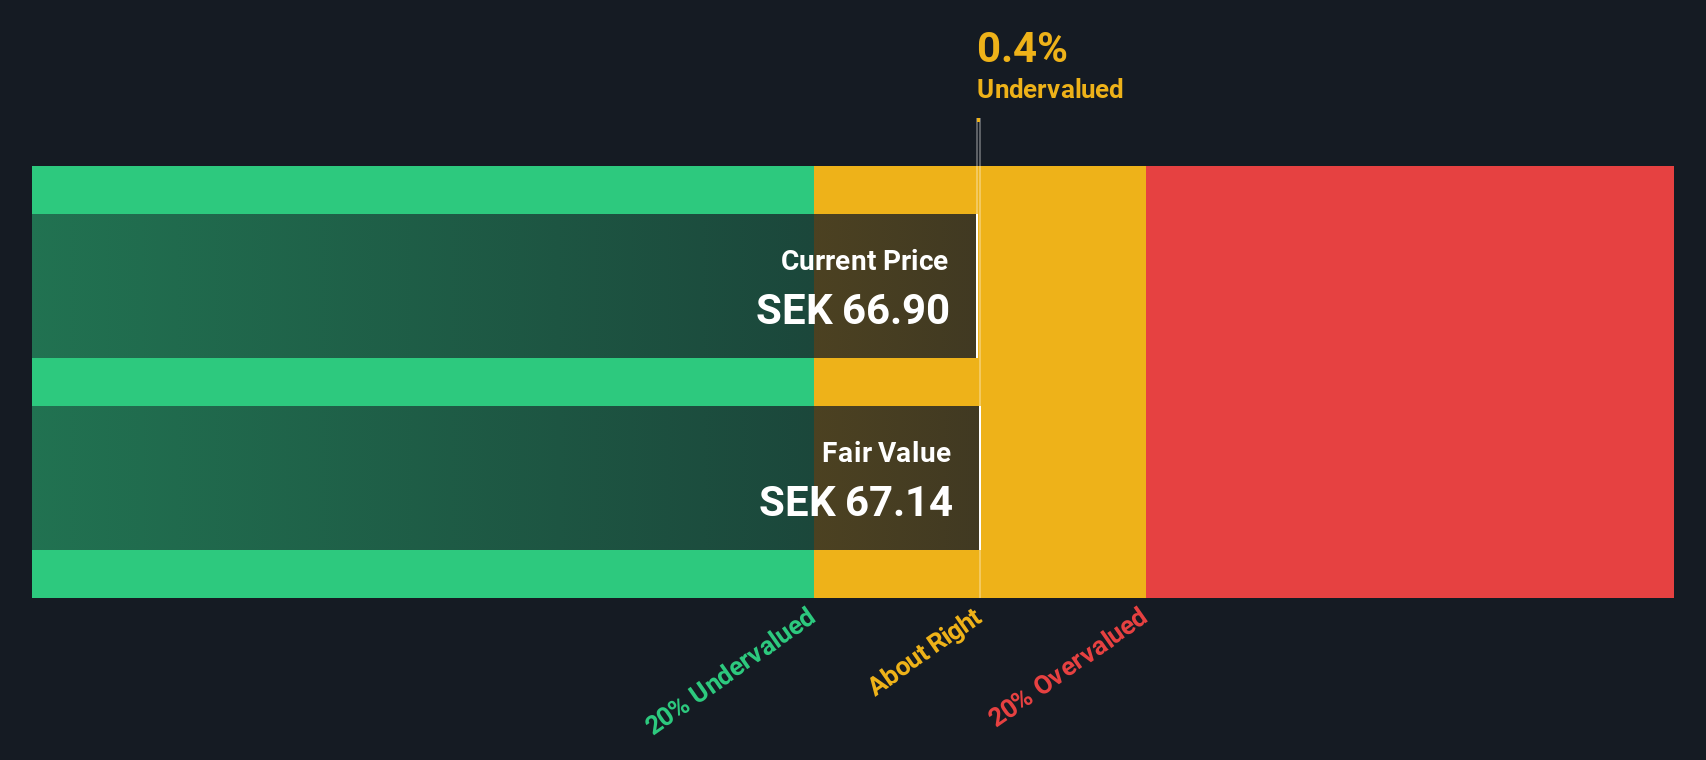
Overview: Linc is a company involved in managing both listed and unlisted holdings, with a market capitalization of approximately SEK 6.23 billion.
Operations: The company's revenue model includes significant contributions from listed holdings, while unlisted holdings show a negative impact. The gross profit margin has consistently been 100%, indicating that all reported revenues translate directly into gross profit. Operating expenses and non-operating expenses vary across periods, affecting net income margins which have fluctuated over time.
PE: 11.9x
Linc, a small European company, recently reported a decline in second-quarter revenue to SEK 244.49 million from SEK 367.59 million last year, but turned around its six-month performance with SEK 82.1 million revenue compared to a negative figure previously. Insider confidence is evident as the CEO purchased 10,000 shares valued at approximately SEK 750,000 in early October. Despite relying on external borrowing for funding, this insider activity suggests potential optimism about future growth prospects.
- Dive into the specifics of Linc here with our thorough valuation report.
Evaluate Linc's historical performance by accessing our past performance report.
Where To Now?
- Investigate our full lineup of 41 Undervalued European Small Caps With Insider Buying right here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com