


Frontdoor (FTDR) slipped after Goldman Sachs began coverage with a Neutral stance, pointing to the company's strong home-services footprint but cautioning that recent share gains and soft home sales may limit near term upside.
Frontdoor now trades at US$77.98, and despite the dip on Goldman’s Neutral call, the 90-day share price return of 4.77% and year-to-date gain of 36.71% point to momentum that has built over time, backed by a 3-year total shareholder return of about 150.74%.
Spot similar momentum and home-service plays by scanning our hand picked 20 high quality undiscovered gems that share Frontdoor’s mix of scale, recurring revenue, and under-the-radar interest.Goldman’s Neutral tag hit sentiment more than it rewrote the Frontdoor story. The real question now is whether the latest pullback matches business fundamentals or just mood music, and what that implies for valuation next.
Most Popular Narrative: 19.9% Undervalued
On the most followed view, Frontdoor’s fair value of $97.40 sits well above the last close at $77.98. This puts the recent pullback against a thesis built on execution in higher margin services and digital channels rather than short term sentiment.
Expansion of non warranty offerings, with the HVAC upgrade program scaling from US$13 million to an expected US$170 million of annual revenue in four years and non warranty revenue growing more than 19% year over year in early 2026, gives Frontdoor a template to add further trades and increase total revenue and EBITDA.
See why 7 investors see Frontdoor as 20% undervalued.
Result: Fair Value of $97.40 (UNDERVALUED)
Still, the Frontdoor narrative can wobble if housing transaction volumes stay sluggish or if heavier marketing and discounting drag on margins for longer than analysts expect.
Find out about the key risks to this Frontdoor narrative.
Another View: Frontdoor Through The P/E Lens
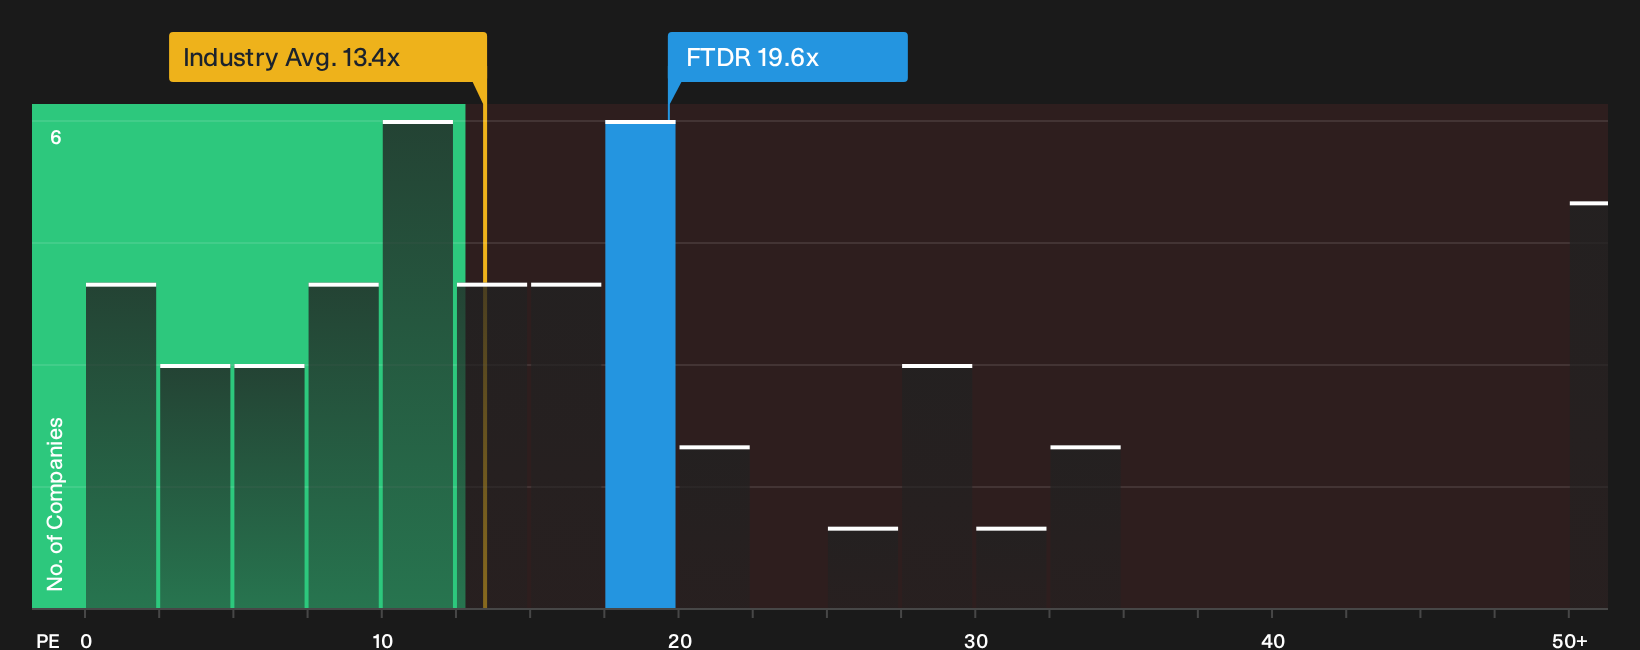
There is a very different read on Frontdoor when you step away from fair value estimates and look at the P/E ratio. The stock trades on roughly 19.6x earnings, above the US Consumer Services group at 14.3x and ahead of the 16.2x peer average. The fair ratio sits lower again at 18.9x.
That gap suggests the market is already paying a premium for Frontdoor against both its sector and its own fair ratio. This tilts this second lens toward a richer pricing picture rather than a clear bargain and leaves you asking whether earnings delivery can keep justifying that mark up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Frontdoor often make the story feel more complicated than it needs to be. Pull the numbers, move quickly, and weigh both the upside and the red flags with 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Frontdoor?
If Frontdoor has you thinking about what else might be hiding in plain sight, use the Simply Wall St Screener to surface fresh ideas before others get there.
- Target value with discipline by scanning for companies that combine quality fundamentals with discounted prices through the 29 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by tracking lesser known quality plays via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com