


Why Matson’s New Ships Matter For Investors
Matson (MATX) just christened Makua, the first of three new Aloha Class containerships tied to its China Long Beach Express and Hawaii routes. This marks a US$1b fleet upgrade centered on LNG-ready and fuel efficient designs.
Investors have already been reacting to this mix of new vessels and stronger quarterly results, with Matson’s share price delivering a 7.9% return over the past 90 days and an 84.0% share price return year to date, while the 1 year total shareholder return sits at 155.0%. This points to strong momentum off both recent earnings and expectations for future cash generation from the upgraded fleet.
Capitalize on Matson’s momentum and shipping tailwinds by scanning a curated set of resilient transport and logistics stocks in our 31 resilient stocks with low risk scores.Matson now trades close to analyst targets and above some intrinsic value estimates after its sharp run. So where does a reasonable fair value zone actually fall within that range?
Most Popular Narrative: 13% Undervalued
Matson last closed at $227.68, while the most followed narrative pegs fair value near $261.25 using a 7.47% discount rate and longer term earnings forecasts.
The main thing that has to go right is that Matson continues to fill its higher priced China and Southeast Asia services while funding its roughly $1b vessel renewal and equipment program largely from internal cash and its Capital Construction Fund.
The current narrative that Matson is undervalued holds that the share price does not fully reflect the raised 2026 earnings outlook, the growth in Southeast Asia volumes, and the scale of ongoing dividends and buybacks.
See why 10 investors see Matson as 13% undervalued.
Result: Fair Value of $261.25 (UNDERVALUED)
Still, Matson’s sizeable US$1b LNG vessel and equipment program, combined with ongoing global trade uncertainty, could quickly challenge the current “undervalued” narrative.
Find out about the key risks to this Matson narrative.
Another View: Matson Through The P/E Lens
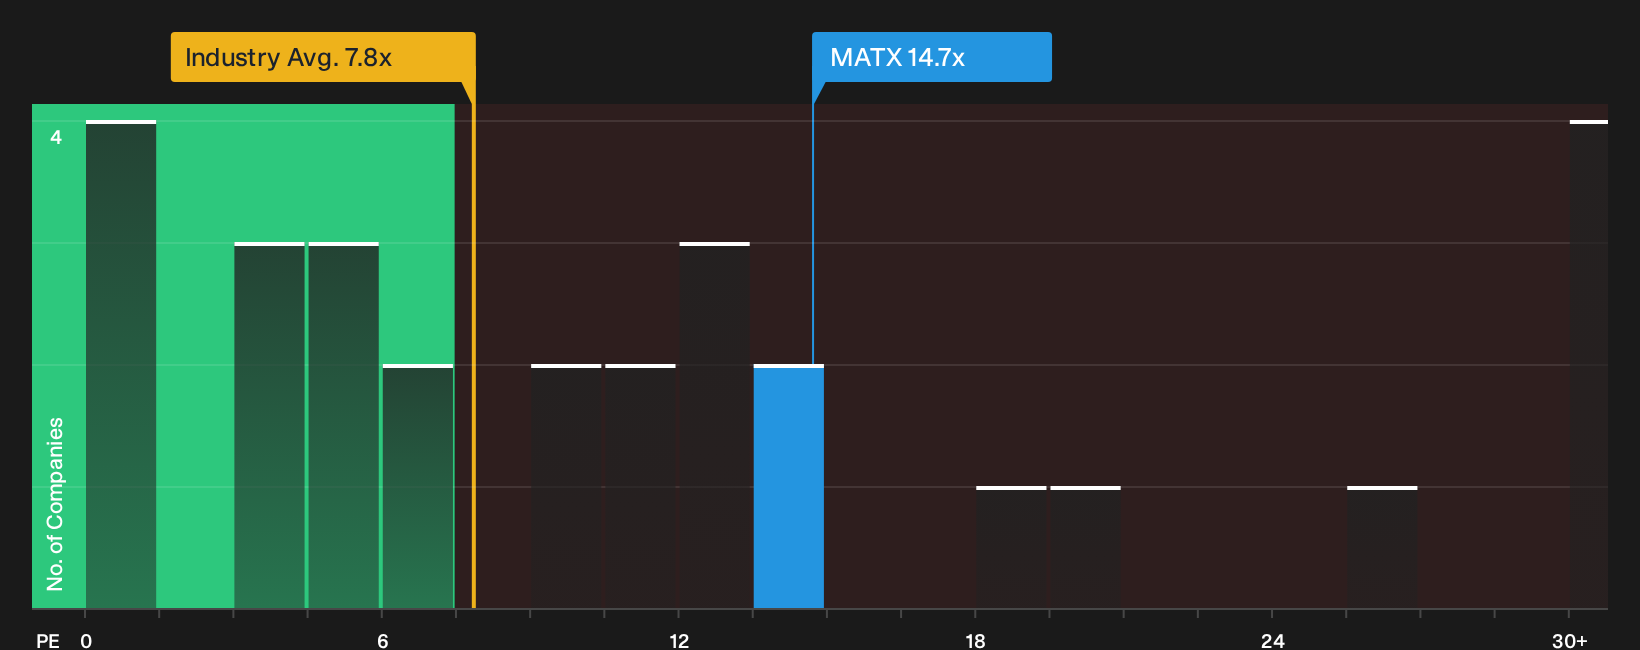
Looking beyond the DCF work changes the picture. On a P/E of 14.7x, Matson trades at a premium to the US Shipping industry on 7.8x, yet below peers at 16.2x and above a fair ratio of 13.3x. This raises the question of whether this reflects a reasonable quality markup or a valuation risk that is building in.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Matson story after such a strong run and busy investment program. If you want to make your own call quickly, weigh both sides of the argument with 1 key reward and 1 important warning sign.
Looking For More Investment Ideas Beyond Matson?
If Matson has sharpened your focus on quality opportunities, do not stop here. Use the screener tools below to uncover fresh ideas before the crowd moves.
- Target quality at a discount by scanning a carefully filtered pool of potentially mispriced companies through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding opportunities using the 8 dividend fortresses.
- Protect your portfolio’s foundation by filtering for financially resilient businesses through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com