


- Waste Connections reported second quarter 2026 earnings and revenue that came in ahead of expectations, with management citing contributions from global waste markets, recent acquisitions and AI driven pricing tools as key supports.
- The company highlighted AI based price optimization and an above average acquisition pipeline as important drivers of recent profitability improvements and potential future revenue upside as these tools and deals are integrated.
- We will now look at how Waste Connections’ improved quarter and AI driven pricing focus reshape the broader investment narrative.
Scan how Waste Connections is using AI driven pricing and acquisitions, then size up peers using similar playbooks with our curated list of 20 high quality undiscovered gems.
Waste Connections Investment Narrative Recap
For an investor to own Waste Connections, the core belief is that pricing discipline, AI tools and steady acquisitions can offset known headwinds like fuel, Chiquita Canyon remediation and a fairly high debt load. The latest quarter supports that narrative. Earnings and revenue came in ahead of expectations, while AI driven pricing and recently acquired businesses contributed meaningfully to profitability.
The short term swing factor remains execution on AI and digital projects that are expected to lift EBITDA margins over time. Chiquita related cash outflows still look like the biggest risk to cleaner free cash flow. The quarter does not remove that issue, but it does not appear to materially worsen it either.
The most relevant piece of context for this update is management’s broader AI and digital programme. Waste Connections is spending about US$100 million across seven projects, including the commercial pricing tool that already supports solid waste core pricing of 5.6% in Q2 2026 and visibility on full year core price at or above 5.5%. The beat this quarter leans on that same toolkit.
Those initiatives are expected by management to eventually add around 100 basis points of EBITDA margin uplift as routing and customer service pilots scale through 2028 and 2029. That makes execution on these systems a key catalyst. If they roll out smoothly, they help offset fuel cost pressure and Chiquita related drag. If they disappoint, the risk section of the thesis moves back to the foreground.
Waste Connections’ current analyst narrative ties to revenues of US$11.6b and earnings of US$1.6b by 2029, built on forecast revenue growth of 5.8% per year and an earnings step up from US$1.1b today. This implies a US$0.5b increase in profit over the period.
Uncover why Waste Connections' fair value indicates a 31% potential upside to its current price that could narrow quickly.
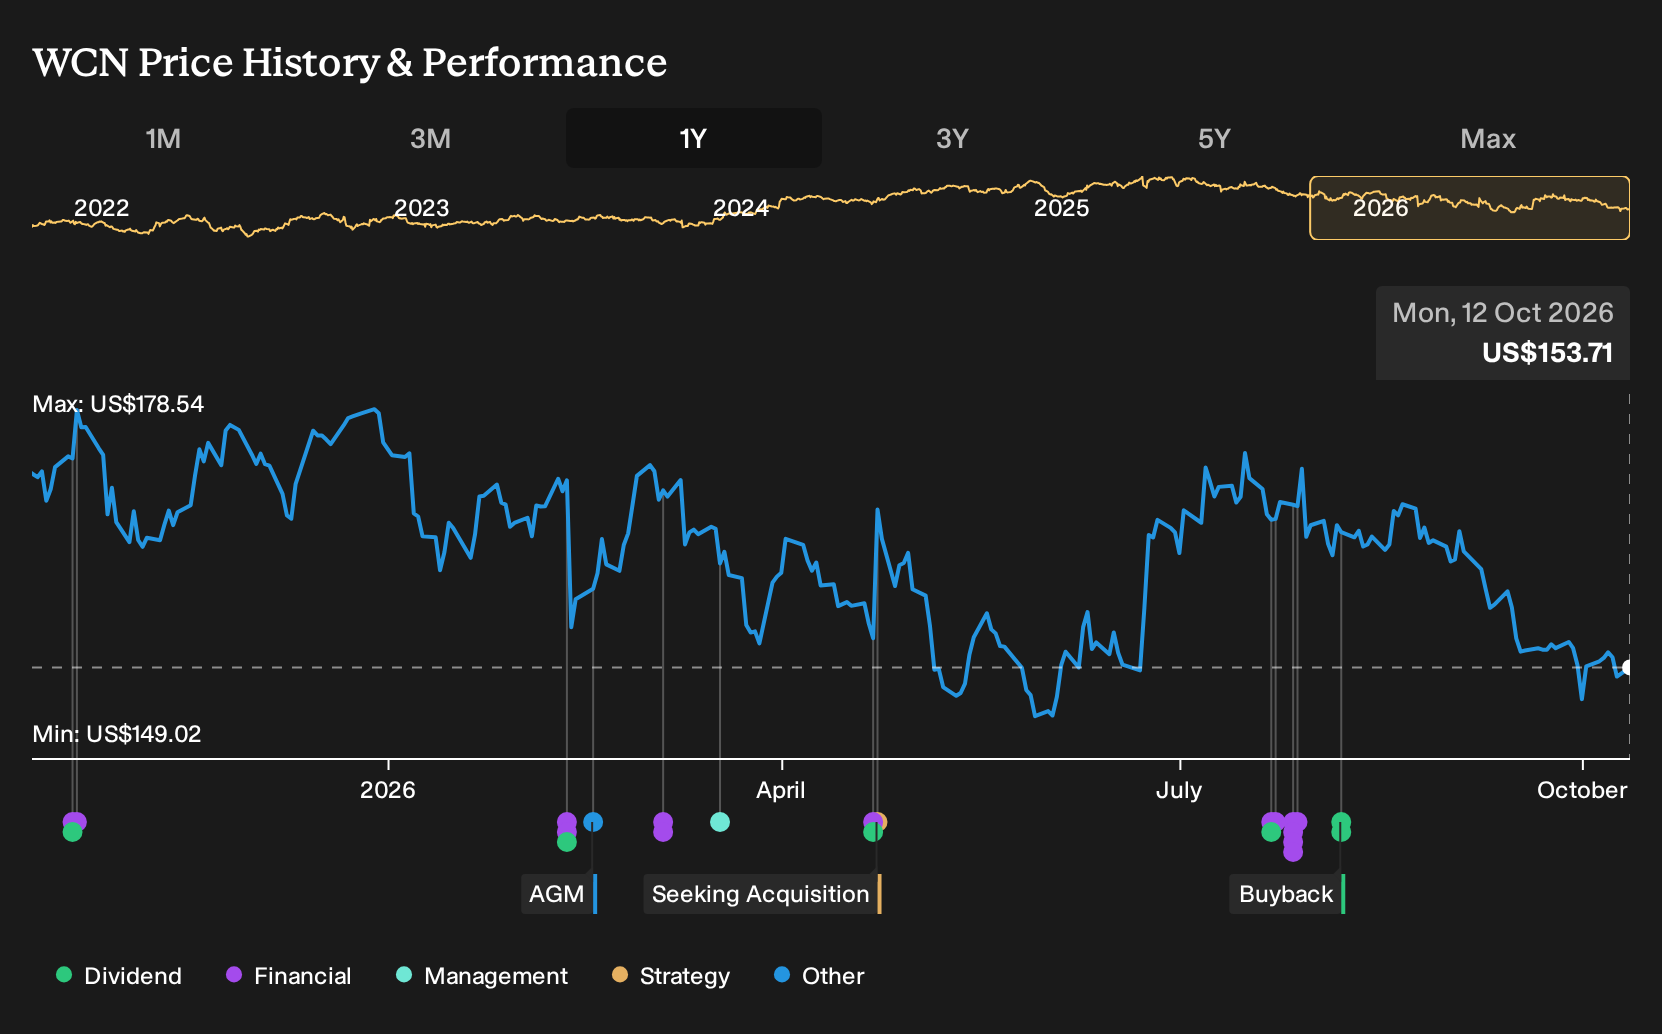
Exploring Other Perspectives
Some of the most optimistic analysts focus on Waste Connections’ renewable natural gas build out as the swing factor. They were already modeling revenue of about US$11.9b and earnings near US$1.8b by 2029. After this earnings beat and AI pricing update, those projections might shift. It therefore makes sense to compare several viewpoints.
Explore 2 other Waste Connections fair value estimates, including one that suggests as much as 79% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Waste Connections research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Waste Connections. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waste Connections' overall financial health at a glance.
Looking for more investment ideas beyond Waste Connections?
If this update on Waste Connections sharpened your thinking, use that momentum to size up a wider field of opportunities with the Simply Wall St Screener. Start with focused shortlists that already filter for quality traits, then apply your own judgement on price, risk and fit with your portfolio.
- If you want a margin of safety built into balance sheets, start with companies screened for resilient finances using our list of solid balance sheet and fundamentals (25 results).
- For readers who care most about durable cash flows and stability, consider income focused opportunities through a curated set of 8 dividend fortresses.
- When the goal is to keep risk contained while still aiming for reasonable upside, begin with a carefully filtered pool of 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com