


Maplebear (CART) is back in focus after Instacart struck two partnership deals, one with Skip in Canada and another with Unite Us in the United States, widening its reach across consumer and healthcare channels.
Against this backdrop, Maplebear’s recent deals sit alongside a share price that has delivered an 8.93% year to date share price return and a 23.5% one year total shareholder return. A 30 day share price decline of 1.85% contrasts with a 92.47% three year total shareholder return, hinting at momentum that has cooled in the short run but stayed strong over a longer stretch.
Scan beyond Maplebear and spot other platform plays that connect consumer reach to real-world services with a handpicked list of 20 high quality undiscovered gems
After Maplebear’s recent run and pullback, analyst targets and intrinsic value estimates now sit well above the US$47.83 share price. Is the gap a genuine margin of safety, or a warning signal before the valuation work begins?
Most Popular Narrative: 18% Undervalued
On the most followed view of Maplebear, a fair value of about $58.14 sits above Friday’s $47.83 close. That gap rests on a specific picture of how the business scales its partnerships and technology over time.
Deepening enterprise partnerships and a growing suite of omnichannel retailer integrations (such as Storefront, Carrot Ads, Caper Carts, Carrot Tags) are increasing stickiness with major retail chains, creating new recurring revenue streams and driving higher-margin, non-transaction-based revenues (e.g., advertising, in-store tech). This is making the business model less volatile and supporting sustainable margin expansion and earnings resilience.
See why 20 investors see Maplebear as 18% undervalued.
Result: Fair Value of $58.14 (UNDERVALUED)
Still, the Maplebear story could change quickly if gig worker rules increase labor costs or if retailers and rivals reduce fees in online grocery.
Find out about the key risks to this Maplebear narrative.
Another View: What Maplebear’s P/E Is Saying
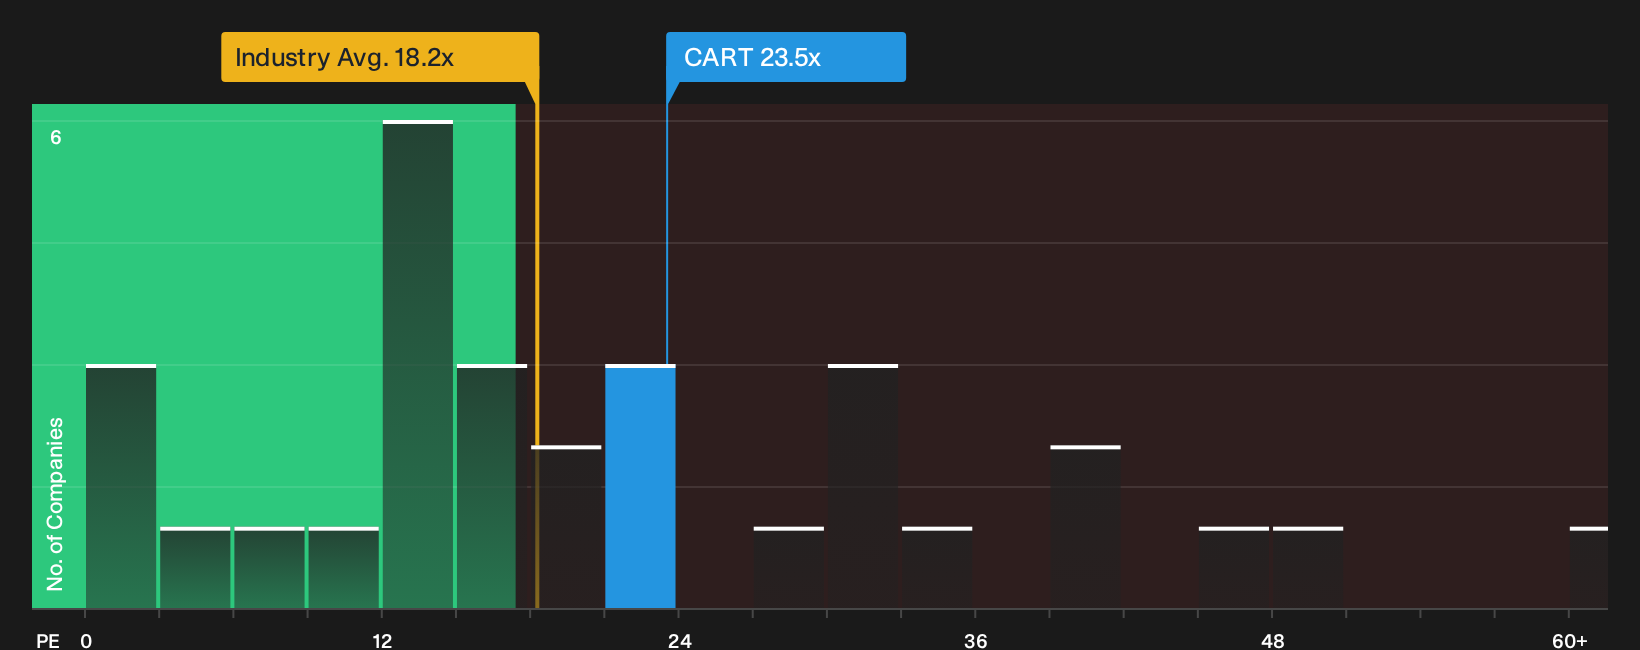
The analyst narrative suggests Maplebear is undervalued, yet the current P/E of 23.5x tells a more cautious story. It is richer than the US Consumer Retailing average of 18.1x, even though it sits below a 42.4x peer average and a fair ratio of 25.9x.
That mix points to potential valuation upside if the market leans toward the fair ratio or peer group. It also points to downside risk if sentiment drifts back toward the broader industry. Which way you lean depends on how much weight you give to those growth and margin assumptions.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The debate around Maplebear’s value will not wait for you. Pull up the data, stress test the story, and weigh both the upside and the red flags in 3 key rewards and 1 important warning sign.
Looking for more Maplebear investment ideas?
If Maplebear has your attention, do not stop here. Broaden your watchlist with other compelling setups that could sharpen your overall portfolio decisions.
- Spot potential mispricings early by reviewing a curated 29 high quality undervalued stocks that filters for quality first, not hype.
- Reinforce your income stream by scanning a focused 8 dividend fortresses designed for investors who care about yield and staying power.
- Dial down portfolio stress by hunting in a 31 resilient stocks with low risk scores that tilts toward resilience when sentiment turns jumpy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com