


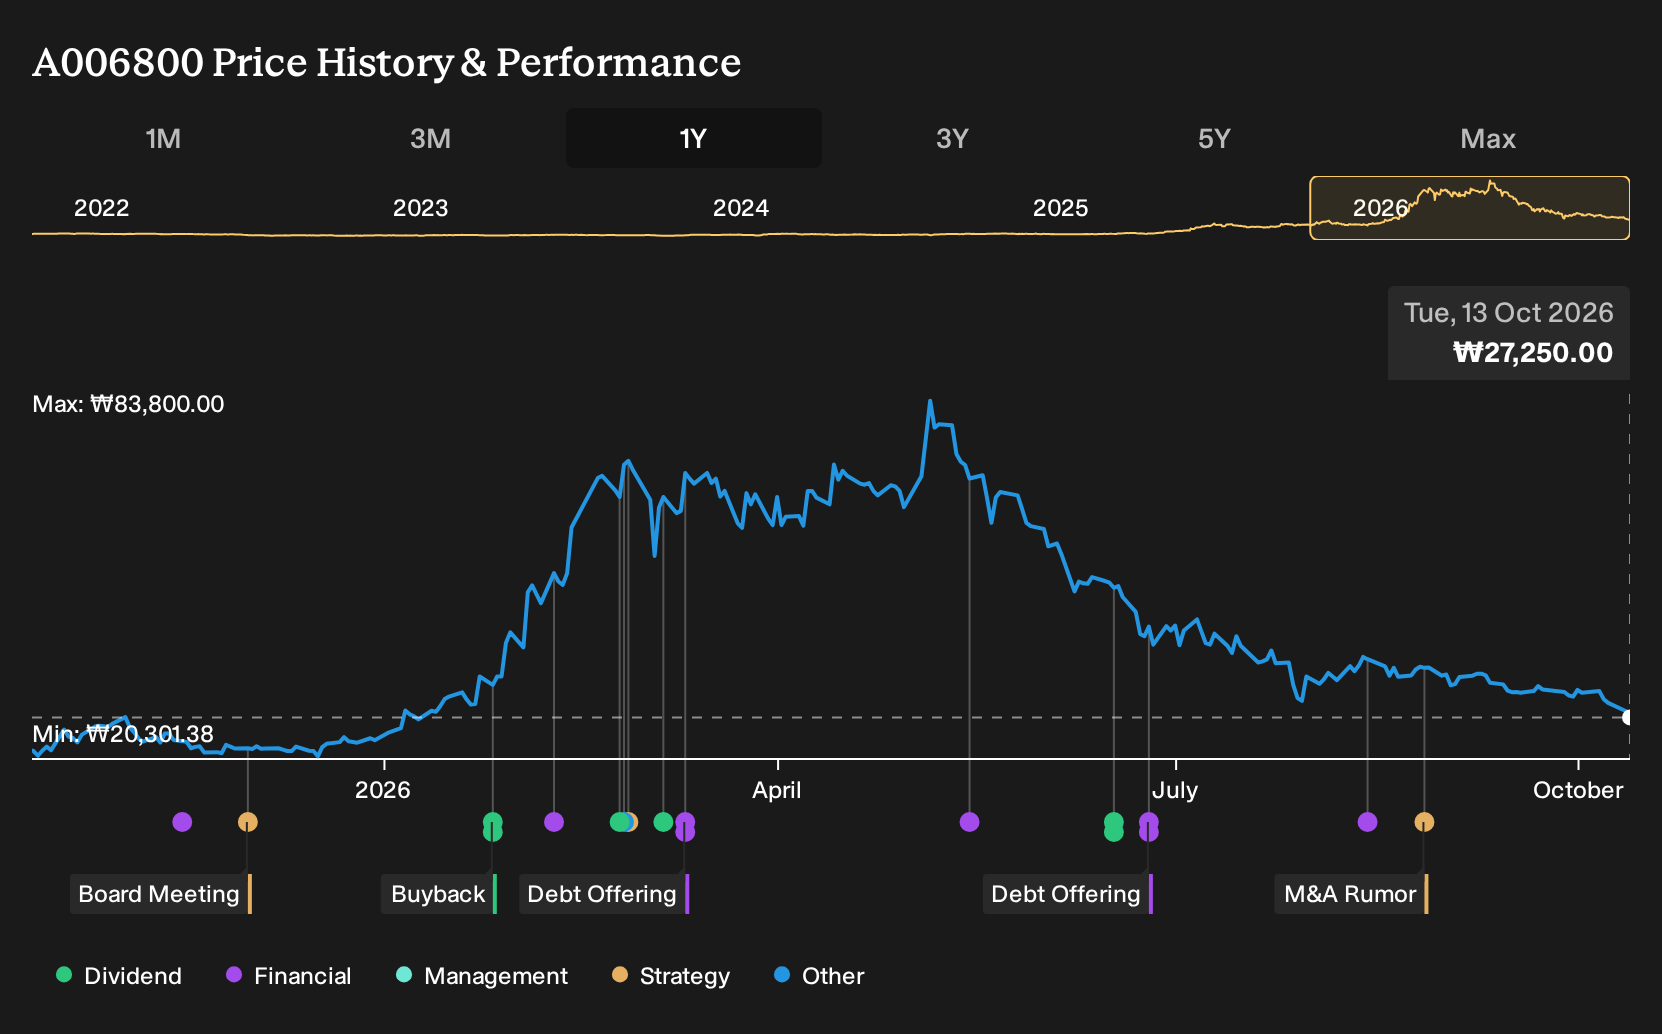
If Mirae Asset Securities sat on your watchlist instead of in your account, the past year might feel like a missed call. Holding Mirae Asset Securities over the past year would have returned 34.2%, including dividends. That outcome lands against a backdrop where bullish analysts framed the WealthSpot and Sharekhan tie up as a way to capture Asia’s wealth shift. If that AI driven India bet was the key assumption, how could you have judged its credibility back in October 2025?
Mirae Asset Securities has already moved. See which of 180 high quality undervalued stocks still trade below our estimates.
The Argument Mirae Asset Securities Investors Faced
The shares cost ₩21,400 at the start of the period, and investors weighing Mirae Asset Securities had to choose between two very different stories built on AI, India, and fee income.
The bullish view pointed to a Fair Value of ₩28,000, a price that would only make sense if aggressive international expansion and the Sharekhan integration in India rapidly scaled revenue and fee based earnings across a 1.4b person market.
The more cautious narrative put Fair Value at ₩20,273, assuming revenue would decline 57.8% a year and that dependence on overseas investments and commercial real estate could strain future profitability and add volatility.
What The Results Changed For Mirae Asset Securities
The clearest data point arrived with Q2 2026 results. Mirae Asset Securities reported revenue of ₩19,261,353m against ₩5,124,543m in Q2 2025, while net income moved to ₩1,458,620m from ₩403,295m. That outcome backed the optimistic focus on scale and earnings growth, although the slip in net margin from 7.9% to 7.6% kept the potential profitability improvement only partly confirmed.
The main lesson is where to look first. When a story leans on AI platforms and cross border expansion, it is useful to track whether revenue and absolute profit move with it, then check if the margin trend justifies any richer P/E investors are being asked to accept.
What Mirae Asset Securities' Price Already Bakes In
Mirae Asset Securities trades today at ₩27,250. The selected Narrative places its Fair Value above that figure and links the gap to how investors judge expansion, technology spend, and earnings mix.
The argument leans on overseas growth, AI driven efficiency, and capital returns. A buyer now would need confidence that AI and digital tools genuinely translate into persistently stronger margins and more durable fee income.
"The company's active investment in AI-driven technology and digitalization, including robotics advisory and automated investment tools, enhances operational efficiency and broadens its service capabilities, which may lead to improved cost control and higher net margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 22% below our estimate - targets chronic prescription volumes and larger loyalty-driven baskets as pharmacies open.
- Company 2 - 48% below our estimate - locks in service work through long-term vessel agreements on dual fuel engines.
- Company 3 - 28% below our estimate - relies on data centre customers scaling GPU racks as power infrastructure expands.
That is three of the list. See the full list of 202 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com