


Fagron (ENXTBR:FAGR) moved into focus after its Q3 2026 sales and trading update, as management paired the call with fresh 2026 revenue guidance of €1,125 million to €1,150 million.
Fagron’s updated 2026 revenue guidance comes as the share price trades at €22.4, with a 30‑day share price return of 6.67% but a 90‑day decline of 6.28%. Total shareholder return of 8.16% over one year and 51.30% over five years suggests momentum that has developed over time rather than following a straight line.
Compare Fagron’s guidance-driven story with other healthcare names showing strong fundamentals using the hand picked list of solid balance sheet and fundamentals (202 results) for potential ideas beyond a single stock.
The share price now trades at a clear discount to both analyst targets and some fair value estimates. Is that caution around Fagron justified, or has the recent guidance reset the bar too low?
Most Popular Narrative: 21% Undervalued
Fagron’s most followed narrative points to a fair value of €28.25 per share, compared with the latest close at €22.4. This frames today’s discount around long term expansion and efficiency projects that need time to play out.
The ongoing expansion into new regions, including the recent entry into the APAC market via the Bella Corp acquisition and direct presence in the UK and Serbia, positions Fagron to tap into growing global demand for personalized pharmaceuticals, supporting future revenue acceleration as demographic trends (aging populations, more chronic conditions) drive higher prescription volumes.
Regulatory emphasis on drug quality and safety is driving consolidation and higher barriers to entry in the compounding sector. This is strengthening Fagron's position as a compliant, vertically integrated multinational and supporting long term growth in both revenue and net margins.
See why 13 investors see Fagron as 21% undervalued.
Result: Fair Value of €28.25 (UNDERVALUED)
Still, the Fagron narrative depends on the smooth integration of recent acquisitions and on compounding volumes holding up if GLP 1 related shortages do not reappear.
Find out about the key risks to this Fagron narrative.
Another View: What Fagron’s P/E Is Really Telling You
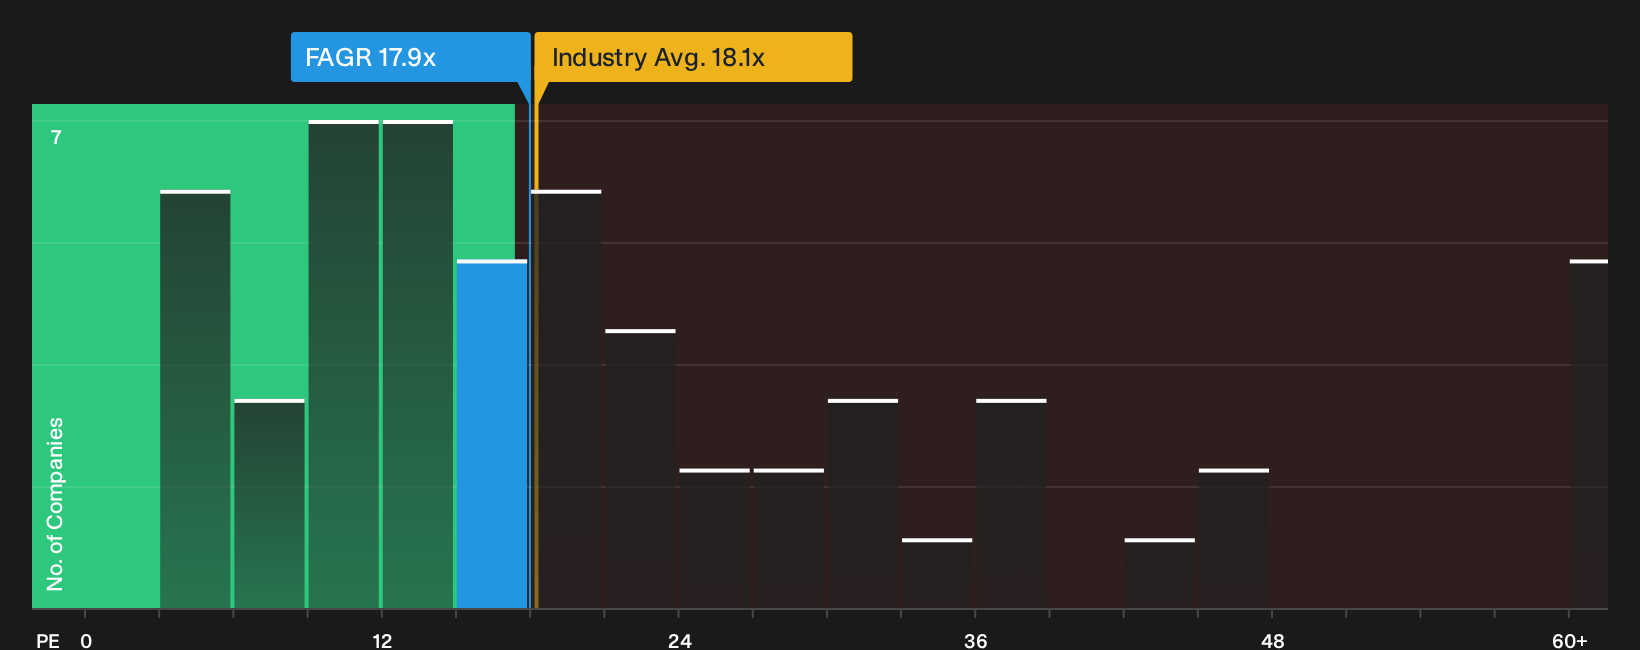
There is a twist once the share price is viewed through earnings. Fagron trades on a P/E of 17.9x, slightly above its own fair ratio of 17.1x and higher than a 16x peer group, yet a touch below the wider European Healthcare average of 18.3x.
That mix points to a stock that screens as cheap on some models but not obviously mispriced on simple earnings comparisons. This raises a practical question for investors: Is the bigger opportunity in the discount to fair value, or in making sure you are not overpaying for growth that still needs to be delivered?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Fagron’s valuation and future execution can feel messy, so move quickly, test the numbers yourself, then weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Fagron?
If Fagron has sharpened your thinking on valuation and risk, do not stop there. A broader watchlist can reveal opportunities you would otherwise never see.
- Expand your hunting ground for quality at a discount by reviewing the 180 high quality undervalued stocks.
- Prioritize resilience and holdings that help you sleep better at night by checking the 225 resilient stocks with low risk scores.
- Hunt for overlooked opportunities with solid fundamentals by scanning the 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com