


The Zhitong Finance App learned that Cui Dongshu, Secretary General of the Passenger Transport Federation, published an article stating that in September 2026, the national passenger car market retailed 1.618 million vehicles, down 28.0% year on year and up 5.0% month on month; from January to September, passenger cars sold a total of 13.334 million units, a decrease of 21.7% year on year. The most prominent characteristic of the September car market is the “poor peak season”, and the traditional “Golden Nine” is seriously underdeveloped. In previous years, the “Golden Nine” market generally rose and was released together with the first purchase and exchange. This year, under the stock game, this year, demand for fuel vehicles continued to shrink sharply.
September became a month with an unusually prominent decline in retail sales in the current wheel car market, due to a combination of factors: first, the Mid-Autumn Festival holiday was brought forward to late September, and sales declined markedly during the Mid-Autumn Festival; second, subsidies were withdrawn in some provinces in September last year, spawning a concentrated subsidy market, forming a high comparison base; third, high fuel prices continued to curb fuel vehicle consumption: gasoline increased by 2,375 yuan/ton during the year since the end of September. Consumption intentions for fuel vehicles have continued to decline, and the retail penetration rate of new energy sources has climbed to a high level of 67%, replacing “oil and electricity” Accelerating progress; fourth, the price of AI-driven memory and chips has skyrocketed and supply is tight Factors such as these have led to the recent slow growth of new energy products, etc. This is the result of a combination of factors.
1. Passenger car retail trends in the narrow sense of the word in recent years
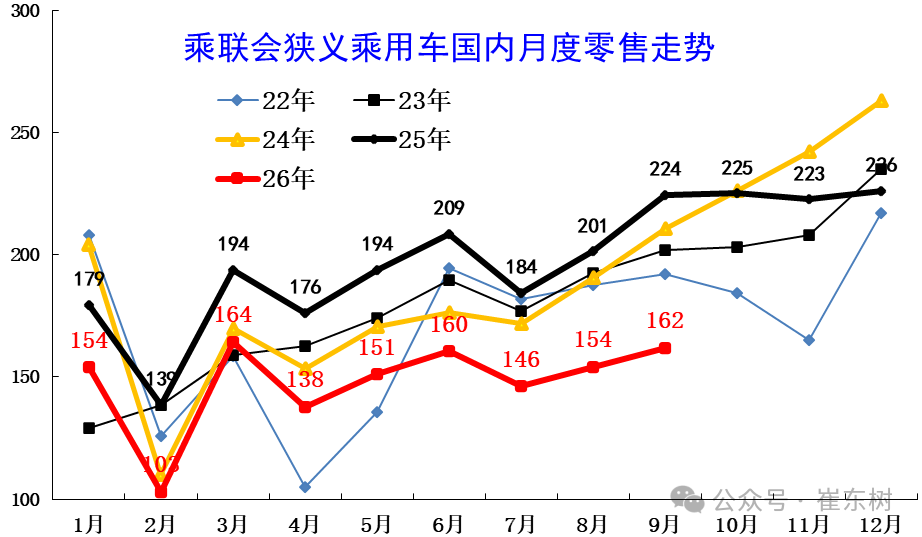
In September, the national passenger car market retailed 1.62 million vehicles. The month-on-month growth performance was weak, leaving the normal growth season trend line. There are many reasons for the continued downturn in September. The first was the impact of high oil prices, followed by the Mid-Autumn Festival holiday. The year-on-year decline was due to the strong regulatory nature of the new trade-in policy and the reduction in passenger car subsidies. Coupled with the sharp impact of upstream price increases, the root cause was low consumption capacity and willingness.
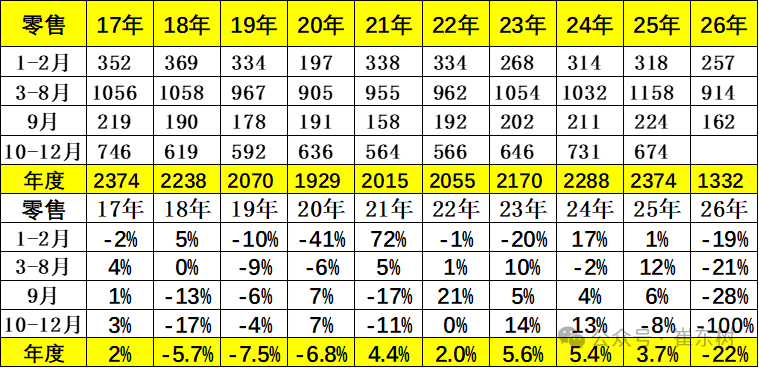
In September 2026, the national passenger car market retailed 1.618 million vehicles, down 28.0% year on year and up 5.0% month on month; from January to September, the total retail sales of passenger cars was 13.334 million units, down 21.7% year on year.
In September 2026, the domestic passenger car market showed a trend of continuous total pressure, month-on-month weakening, and extreme structural differentiation. The downturn in the off-season was highlighted, and the structural adjustment of the industry was further deepened.
2. Passenger car wholesale trends in the narrow sense of the word in recent years
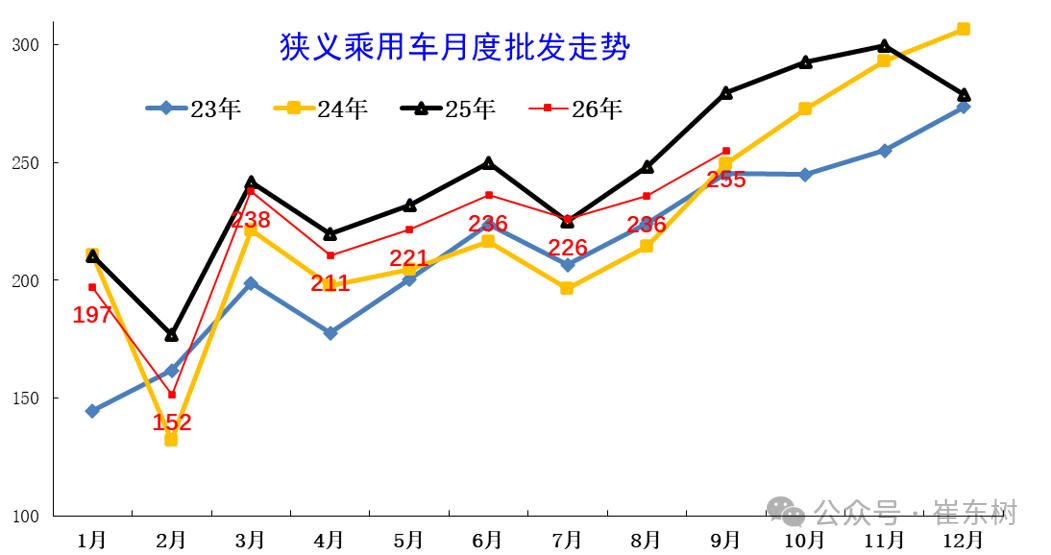
Passenger car manufacturers across the country wholesale 2.55 million vehicles in September, a significant decline over the same period. The trend in September of previous years was relatively strong. The domestic economy was sluggish but export growth was high this year, so the overall return was stable. Due to strong exports, few domestic wholesalers, and good inventory removal results, channel pressure has improved markedly.
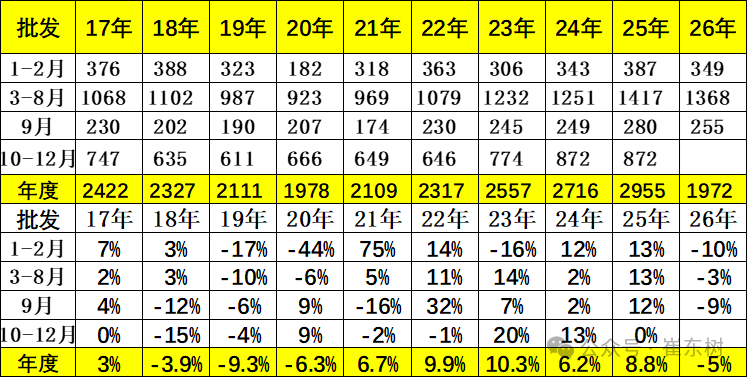
In September, the country's passenger car manufacturers wholesale 2,549 million vehicles, down 8.9% year on year and up 8.1% month on month; encouraged by the surge in exports, the year-on-year growth rate of passenger car wholesale in September was 19 percentage points higher than the retail growth rate.
3. Passenger car production trends in the narrow sense of the word in recent years
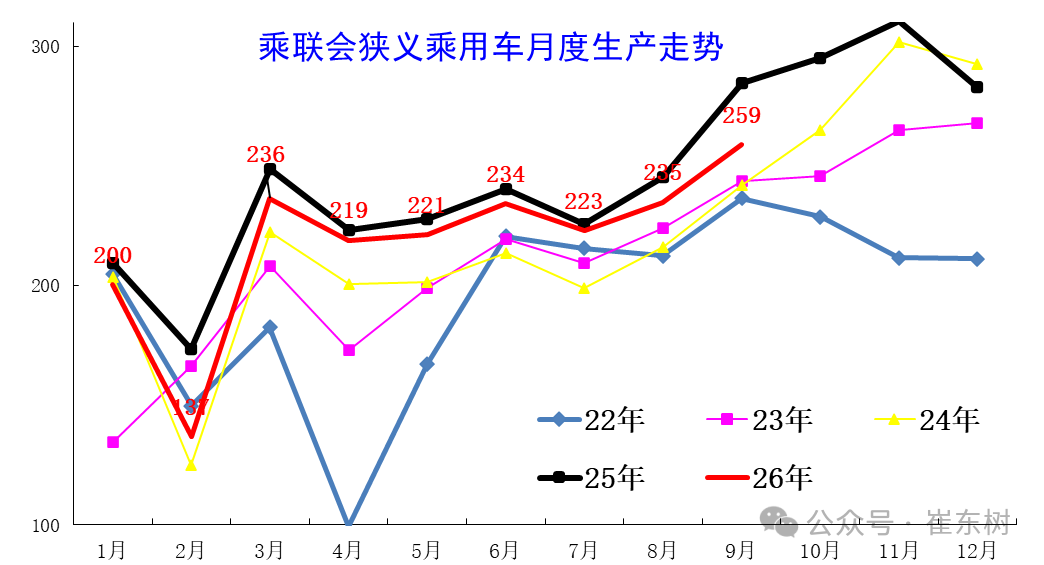
Passenger car production will be drastically reduced in 2026. The month-on-month increase in September was 10.3%, and the trend was strong. Exports continued to strengthen, leading to a relatively high in September production during the year, but the year-on-year trend declined significantly.
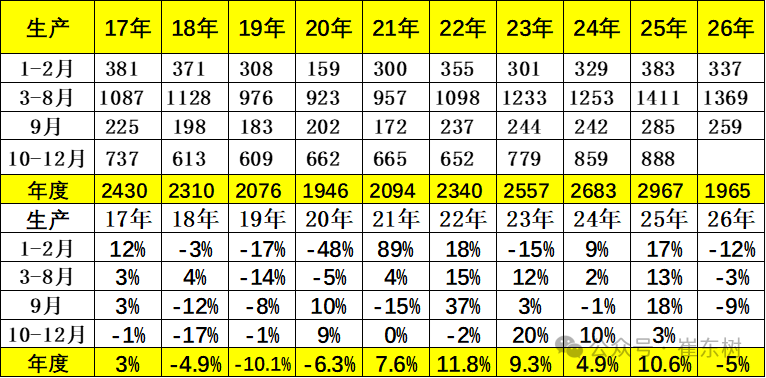
Passenger car production in September was 2.59 million units, down 9.1% year on year, with a cumulative decrease of 5% in 2026, with a significant impact on domestic demand.
4. Passenger car export trends in the narrow sense of the word in recent years
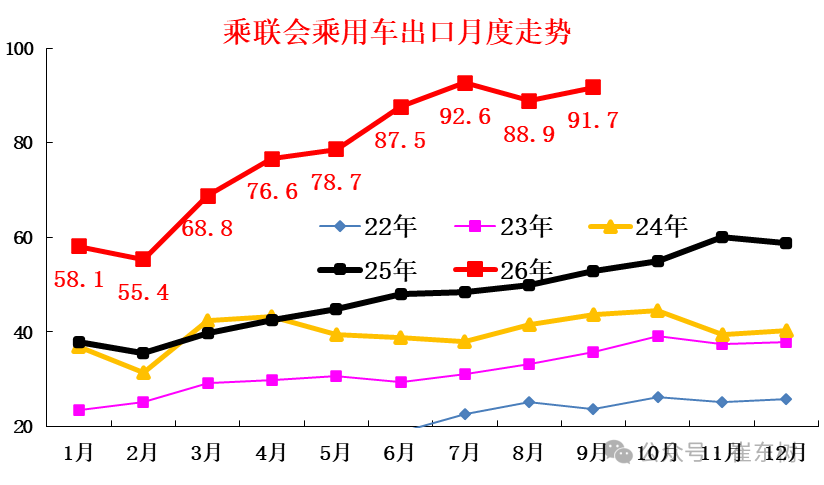
Exports rebounded slightly in September compared to August, but did not break through the July peak for two consecutive months. The rapid month-on-month upward trend changed, and the market gradually entered a stable period.
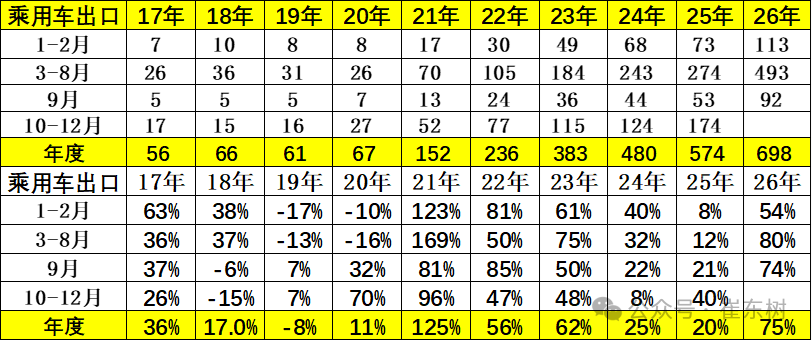
Passenger car exports (including complete vehicles and CKD) were 917,000 units in September, up 73.7% year on year and 3.2% month on month, accounting for 36% of passenger car manufacturers' sales volume (38% last month, 19% in the same period in 2025). New energy vehicles accounted for 60.8% of total exports in September, a sharp increase of 21 percentage points over the same period.
5. Characteristics of monthly changes in production and sales inventory
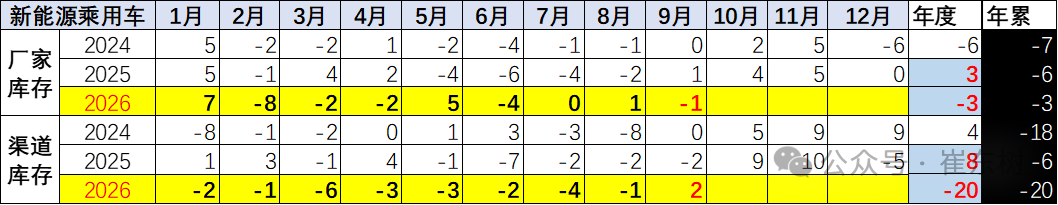
Due to the high operating pressure of the domestic retail market in September, manufacturers' wholesale sales fell below 41,000 units in September, while the monthly domestic wholesale volume of manufacturers was higher than domestic retail sales of 14,000 units. The characteristics of inventory removal are prominent this year. The overall inventory of the passenger car industry fell by 680,000 units in January-September (250,000 units in the same period in 2025, 880,000 units in the same period in 2024, and 130,000 units in the same period in 2023).
6. Growth characteristics of passenger cars in the narrow sense of the word
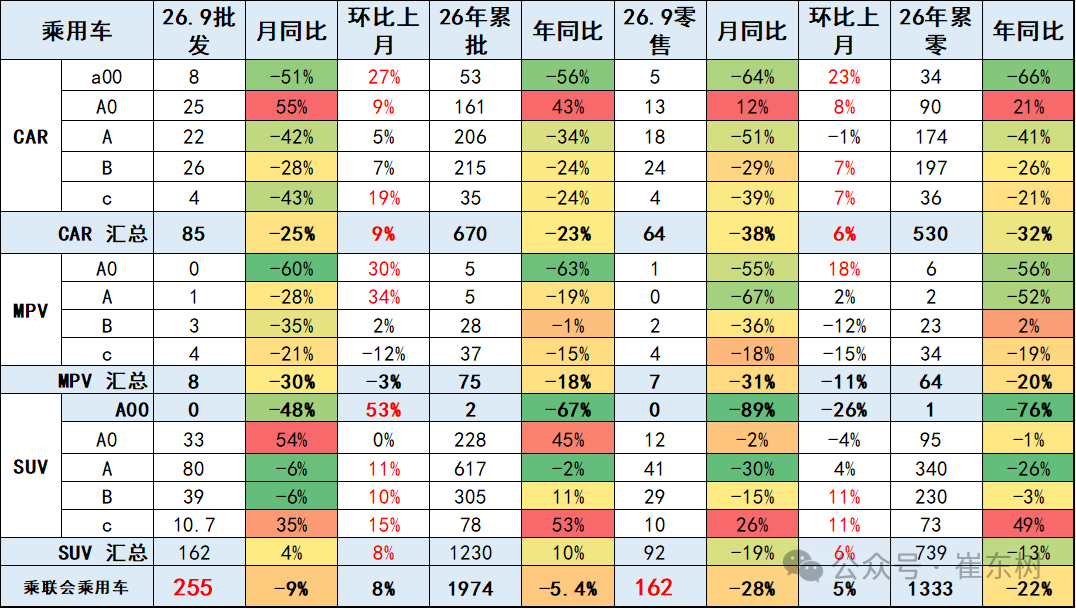
Passenger car retail sales fell 28% and wholesale fell 9% in September 2026. The retail growth rate was much weaker than the wholesale growth rate, forming a pattern of internal cooling and external heat.
Entry-level consumption has been hit hard. Due to the impact of high fuel prices and the suspension of subsidies, retail sales of A-class cars and A00-class cars were both lower in September. A0 class cars and high-end models became the main retail forces in September. The high-end performance of SUVs was strong, and sales of mainly A0 class cars rebounded.
7. Growth characteristics of passenger cars by country in the narrow sense
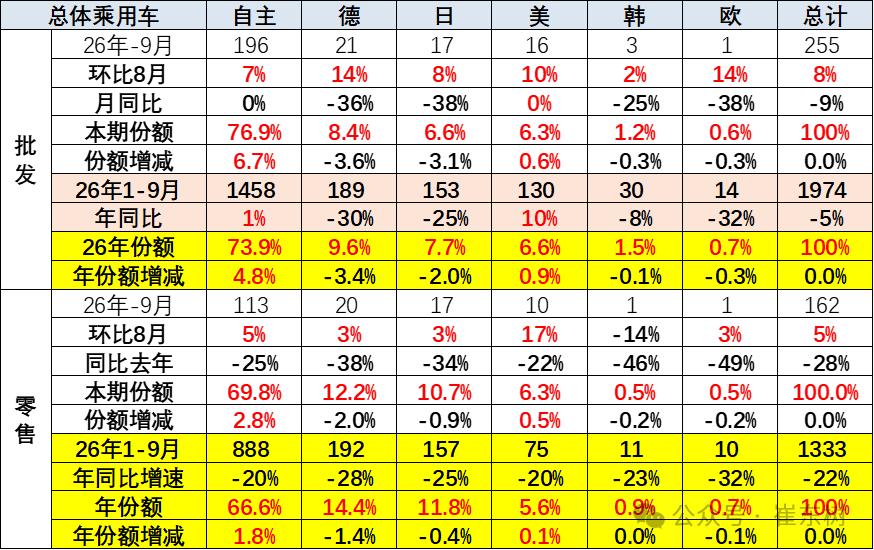
In September, retail sales of 1.13 million vehicles under independent brands were recorded, down 25% year on year and up 5% month on month. The domestic retail share of independent brands in the same month was 69.8%, an increase of 2.8 percentage points over the previous year. Overall, the performance of independent brands in the new energy market and export market is relatively stable.
Mainstream joint venture brands retailed 310,000 vehicles in September, down 36% year on year and up 2% month on month. In September, the retail share of German brands was 12.2%, down 2.0 percentage points from the previous year; the retail share of Japanese brands was 10.7%, down 0.9 percentage points from the previous year; the retail share of the American brand market was 6.3%, up 0.5 percentage points from the previous year. Low-volume joint ventures are gradually recovering their vitality.
8. 2026 Brand Production and Sales Characteristics
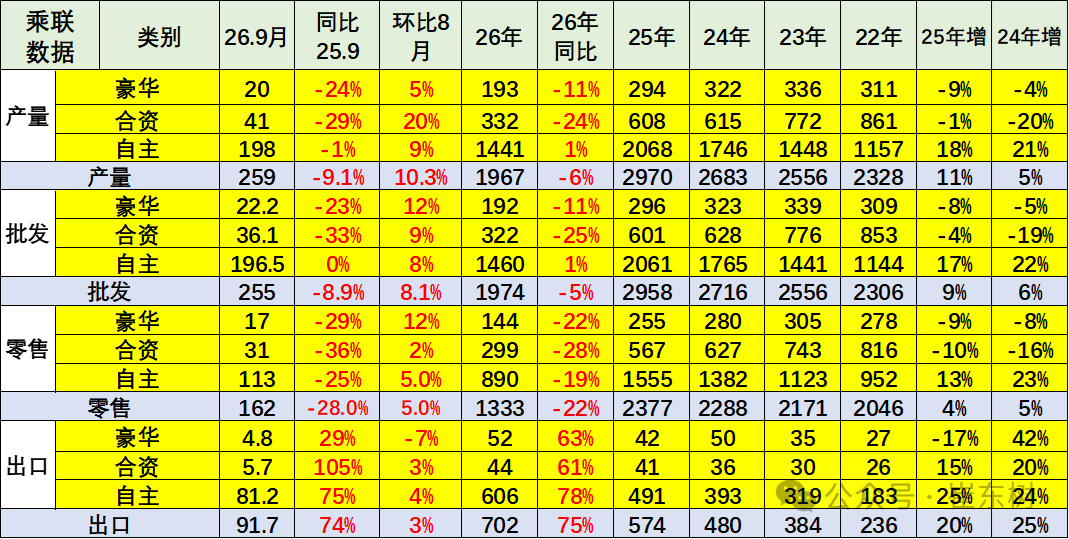
The original brand value system has changed, and the pressure on luxury brands has continued to increase recently. The production and sales trend pressure of joint ventures continues to be strong, and the advantages of the independent brand industry chain are obvious.
Demand differentiation pressure was strong in September, and the trend of the fuel vehicle market was poor month-on-month, leading to a deterioration in the trend of joint venture brands. Independence from new energy sources and exports performed relatively well.
10. National New Energy Permeability Rate - Wholesale
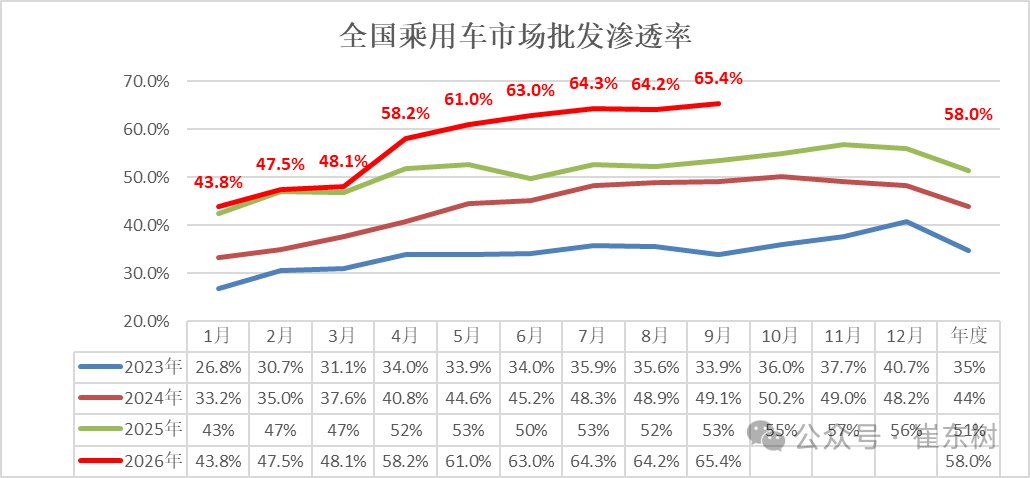
In September, the wholesale penetration rate of NEV manufacturers was 65.4%, up 12 percentage points from September 2025.
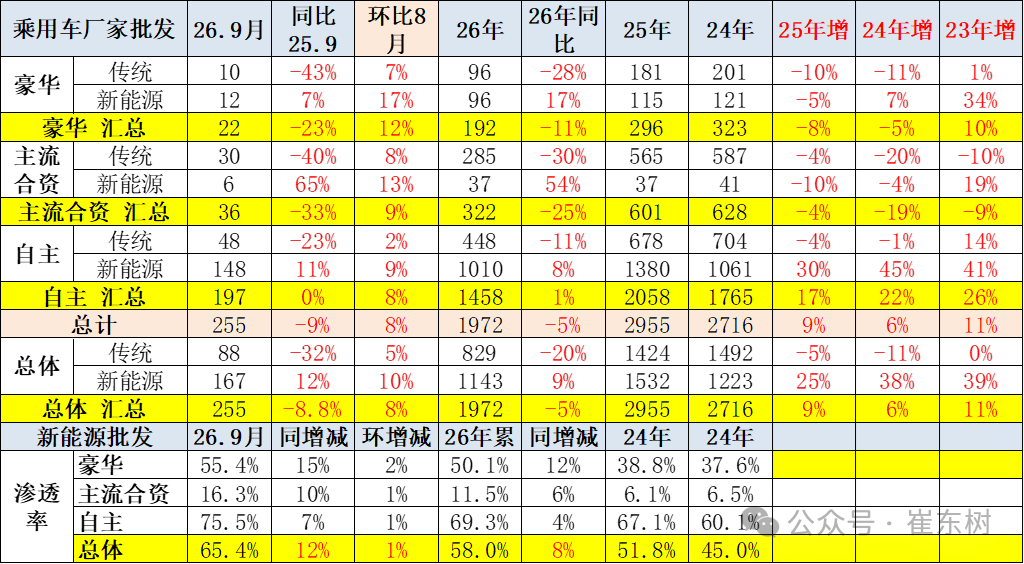
In September, the penetration rate of own-brand new energy vehicles was 75.5%; the penetration rate of new energy vehicles among luxury cars was 55.4%; the penetration rate of mainstream joint venture brand NEVs rose to 16.3%.
In September, wholesale sales of traditional car manufacturers fell 32% year on year, while new energy vehicles increased 12% year on year, with a growth gap of 44 percentage points. The fuel vehicle market continued to be sluggish, and new energy exports contributed greatly.
11. National New Energy Penetration Rate - Retail
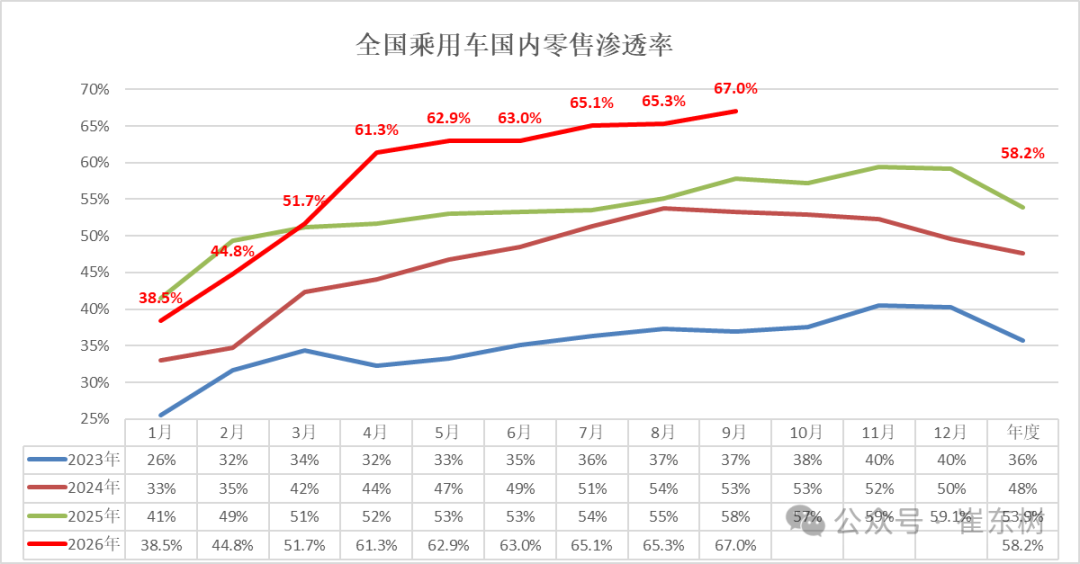
In September, the overall retail sales penetration rate of new energy vehicles in China was 67.0%, an increase of 9.1 percentage points over the same period last year, and an increase of 1.7 percentage points over the previous year.
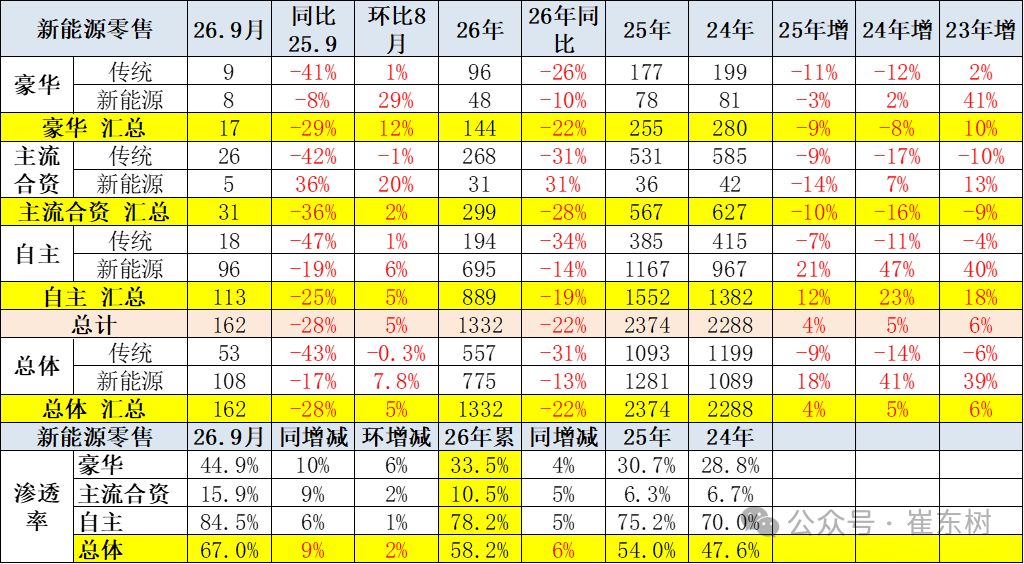
In domestic retail sales in September, the penetration rate of new energy vehicles among independent brands was 84.5%; the penetration rate of new energy vehicles among luxury cars was 44.9%; while the penetration rate of new energy vehicles in mainstream joint venture brands only rose to 15.9%.