


In October 2026, global markets are navigating a landscape marked by mixed performances across major indices, with the S&P 500 showing gains while small-cap stocks like those in the Russell 2000 face declines amid volatility in energy prices and geopolitical tensions. As investors grapple with these uncertainties, discovering undiscovered gems requires a keen eye for companies that demonstrate resilience and potential growth despite broader market challenges.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
W&B Technology (TPEX:7744)
Simply Wall St Value Rating: ★★★★★★
Overview: W&B Technology Ltd. specializes in the manufacture and assembly of mechanical components, with a market capitalization of NT$16.23 billion.
Operations: W&B Technology Ltd. generates revenue primarily from the sales and services of its EMS Electronic Professional Supply Chain, amounting to NT$3.30 billion. The company's market capitalization stands at NT$16.23 billion.
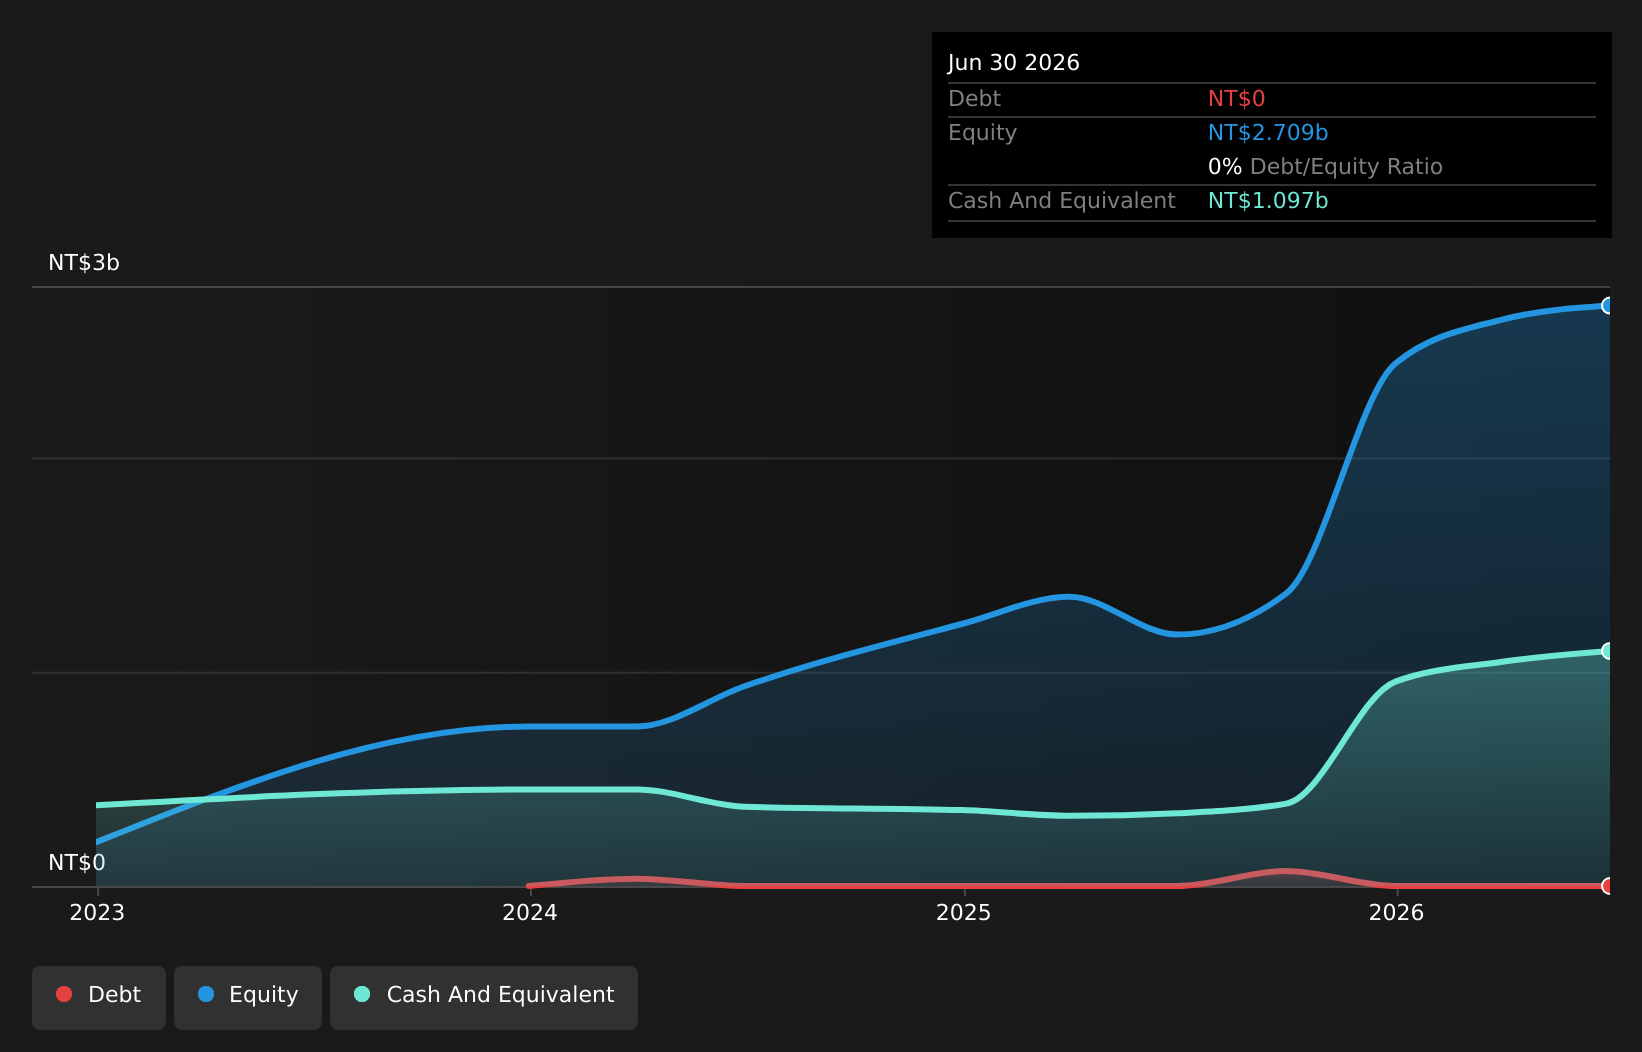
W&B Technology, a promising player in the tech space, has shown impressive performance with earnings growth of 73% over the past year, outpacing its industry. Trading at 76.2% below estimated fair value suggests potential for upside. The company reported significant sales growth for Q2 2026 at TWD 1.11 billion compared to TWD 528 million last year, with net income jumping to TWD 250 million from TWD 92 million. With no debt concerns and high-quality non-cash earnings, W&B's inclusion in the S&P Global BMI Index highlights its growing recognition and potential future prospects in the market.
- Take a closer look at W&B Technology's potential here in our health report.
Examine W&B Technology's past performance report to understand how it has performed in the past.
Yahagi ConstructionLtd (TSE:1870)
Simply Wall St Value Rating: ★★★★★★
Overview: Yahagi Construction Co., Ltd. operates in Japan's construction, civil engineering, and real estate sectors with a market capitalization of approximately ¥88.35 billion.
Operations: Yahagi Construction generates revenue primarily from its construction, civil engineering, and real estate activities in Japan. The company has a market capitalization of approximately ¥88.35 billion.
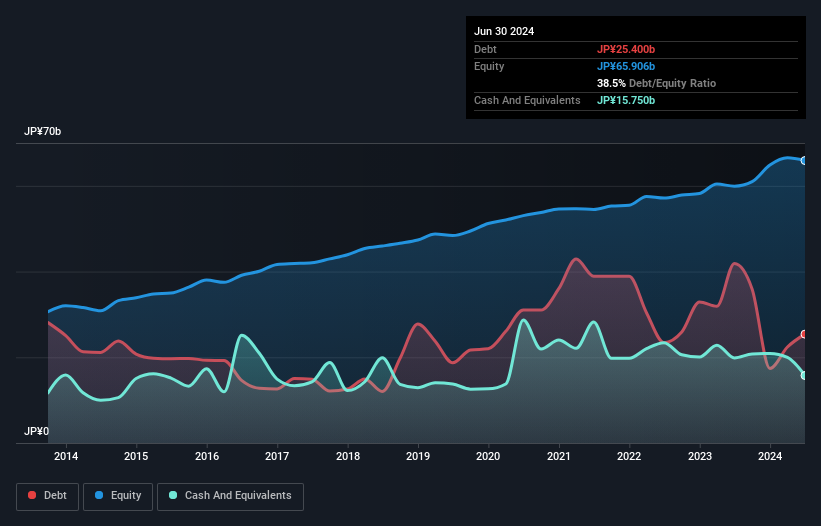
Yahagi Construction seems to be carving a solid niche with its robust financial health and strategic moves. Over the past five years, earnings have grown at an impressive 22.3% annually, while the debt-to-equity ratio has significantly decreased from 71.4% to 19.2%, reflecting prudent financial management. The company also boasts a strong EBIT coverage for interest payments at 103.9 times, indicating sound operational efficiency. Recent guidance revisions highlight enhanced profitability prospects with expected net sales of ¥68,600 million for the upcoming six months and an annual dividend increase to ¥110 per share, showcasing commitment to shareholder value enhancement through strategic asset reallocation and improved capital efficiency.
Akatsuki (TSE:3932)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Akatsuki Inc. operates in the entertainment, lifestyle, and solutions sectors both in Japan and internationally, with a market cap of approximately ¥46.75 billion.
Operations: Akatsuki Inc. generates revenue from its entertainment, lifestyle, and solutions sectors. The company's market cap stands at approximately ¥46.75 billion.
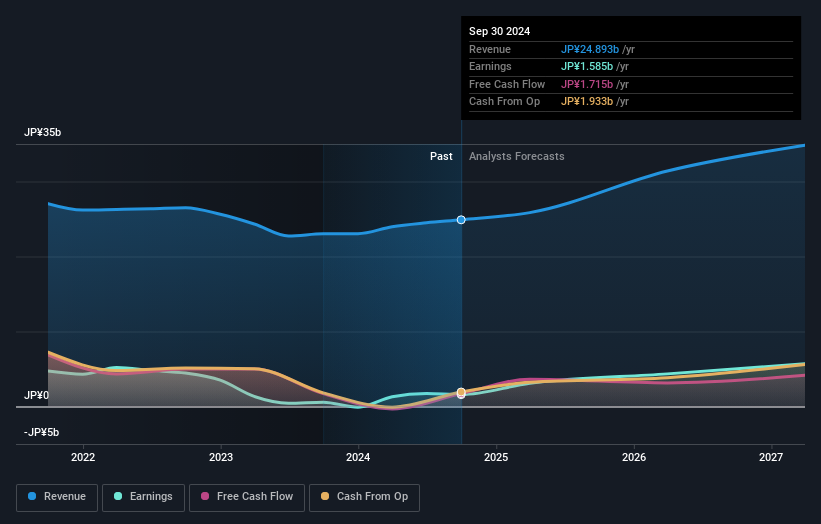
Akatsuki, a nimble player in the entertainment sector, has been making waves with its impressive financial performance. Over the past year, earnings skyrocketed by 914%, outpacing the industry's 24.8% growth rate. Despite a volatile share price recently, Akatsuki trades at an attractive 62.7% below estimated fair value and boasts high-quality earnings. The company's strategic decisions include a significant stock split and amendments to its Articles of Incorporation to increase authorized shares from approximately 45 million to over 135 million, signaling ambitious growth plans ahead. With more cash than debt and positive free cash flow, Akatsuki seems poised for continued success.
Make It Happen
- Explore the 166 names from our Global Undiscovered Gems With Strong Fundamentals screener here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com