


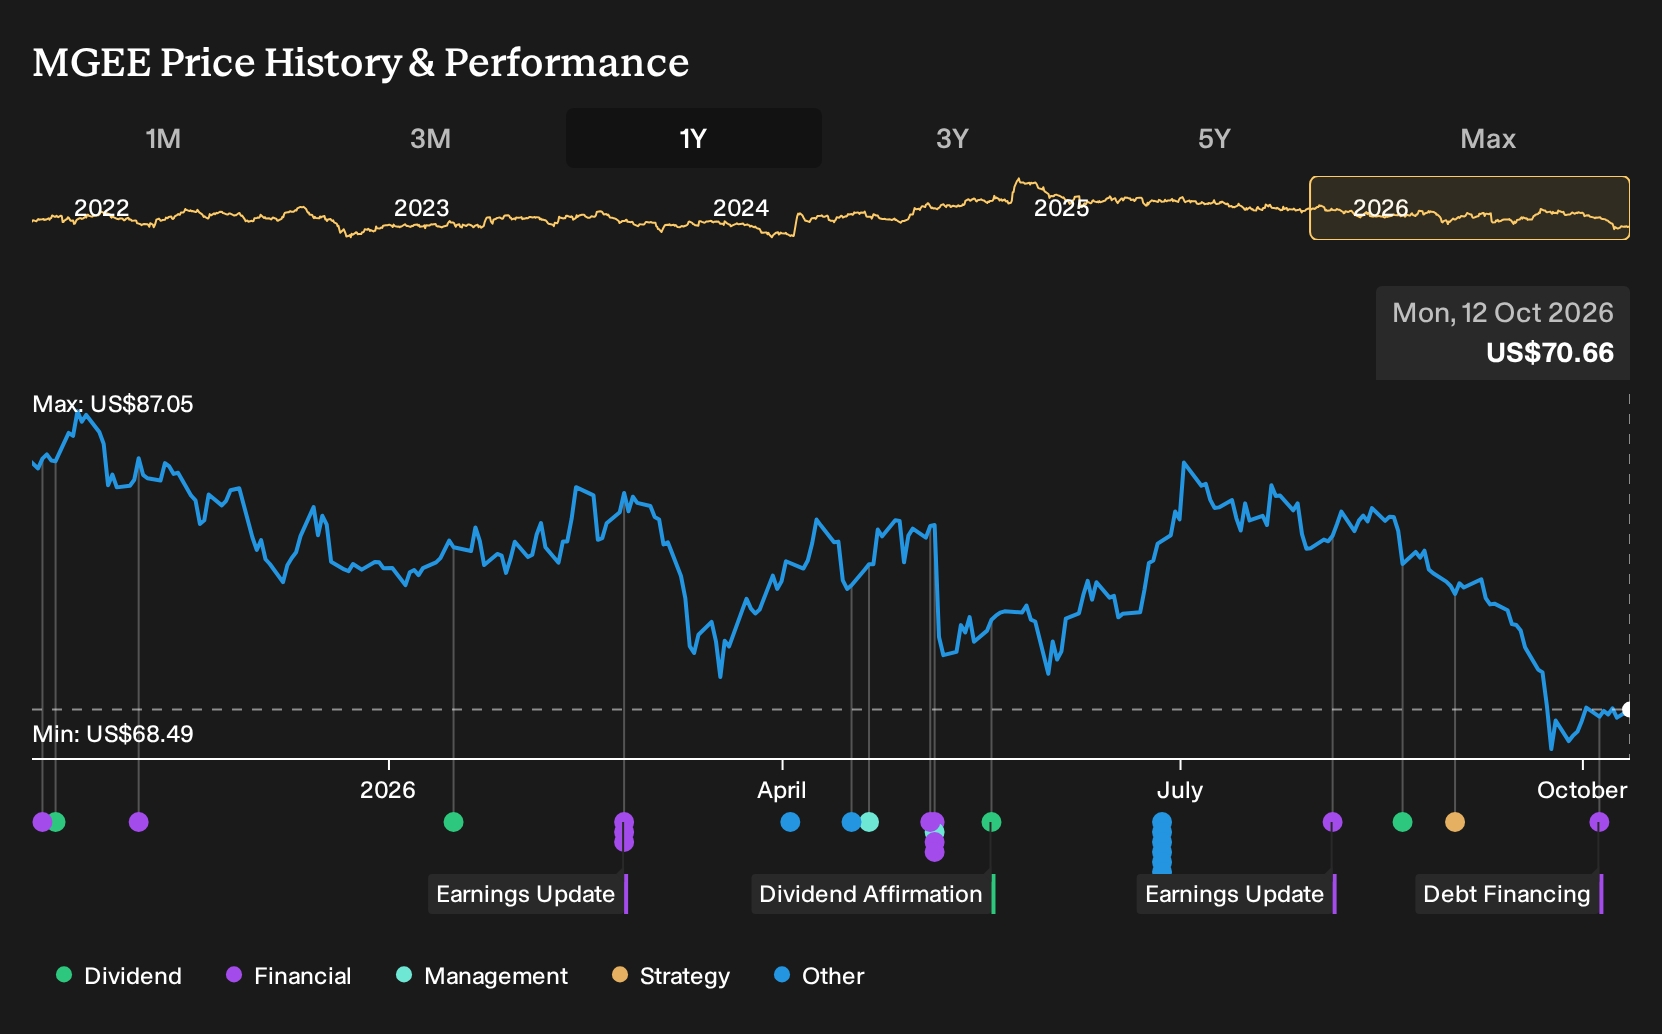
- MGE Energy and Madison Gas and Electric Company amended and restated multiple credit agreements in October 2026, extending maturities to 2031 and expanding key revolving facilities, including a JPMorgan-led line for Madison Gas and Electric Company that provides up to $210 million and a $50 million revolver for MGE Energy.
- The longer terms, higher aggregate commitments and shared 65% leverage covenant may affect how MGE Energy manages liquidity, funds future projects and handles temporary funding needs without relying solely on short term capital markets.
- The expanded revolving credit capacity and longer debt maturities are also relevant to how market participants may view MGE Energy's overall investment profile.
What Is MGE Energy's Investment Narrative?
MGE Energy’s pitch is ultimately about a regulated utility with steady electricity and gas demand, meaningful capital needs and a management team that has kept earnings growing at 6.8% a year over five years. The amended credit agreements fit directly into that story. Larger, longer dated revolving lines give the utility more room to fund grid upgrades, renewables and storage projects without depending on short term markets for every dollar of working capital.
In the short term, the new facilities do not change the core debates around MGEE. You still have a business with high debt, a dividend that is not well covered by free cash flow and forecast earnings growth of 6.8% a year that trails the wider US market. The appeal for a shareholder is a regulated model, high quality earnings and a P/E of 17.8x that screens below both the US market and electric utility peers, balanced against...
There's only one way to know the right time to buy, sell or hold MGE Energy. Head to Simply Wall St's company report for the latest analysis of MGE Energy's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value views on MGE Energy, with estimates ranging from about $60.83 to more than $200,000 per share, which shows how far opinions can spread. You are seeing these before the expanded credit lines filter into those models, so treat them as starting points and compare several perspectives.
Explore another MGE Energy fair value estimate, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your MGE Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MGE Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MGE Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond MGE Energy?
Once you have a handle on MGE Energy, it often helps to compare it with other businesses that share traits you care about, whether that is value, income or balance sheet strength. The Simply Wall St Screener lets you move from this single stock to a wider watchlist that fits your own risk and return preferences.
- If you are hunting for companies that the market may be pricing conservatively, use the screener to check out 29 high quality undervalued stocks that match your quality and valuation filters.
- If income reliability matters to you, sort through 8 dividend fortresses that align with your yield targets and payout preferences.
- If capital preservation is front of mind, focus on list of solid balance sheet and fundamentals (25 results) to see which businesses pair sturdy finances with the kind of resilience you want in a downturn.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com