


Lincoln Electric’s earnings beat puts mixed quarter in focus
Lincoln Electric Holdings (LECO) kicked off a fresh round of investor debate after quarterly results combined a 12% year-on-year revenue gain with a strong adjusted operating income beat and softer organic sales.
The welding and industrial automation specialist also moved higher in the market after the release, with the stock up 1.2% and recently trading around US$261.14, as investors weighed the stronger profitability against the mixed underlying demand picture.
In the short term, Lincoln Electric’s share price has slipped 5.6% over the past week even after the earnings beat. By contrast, the 1-year total shareholder return of 12.9% and 5-year total shareholder return of around 100% show a much stronger longer-run picture as investors reassess growth potential and risk after a steady year-to-date gain.
Scan for other industrials showing similar earnings momentum and mixed demand signals by checking the curated list of 92 robotics and automation stocks alongside the latest move from Lincoln Electric.
After a soft week for the share price, Lincoln Electric now trades at a clear discount to both analyst targets and estimated fair value. Is that a bargain or a warning that the market’s caution is justified?
Most Popular Narrative: 15% Undervalued
Against the last close of $259.69, the most widely followed narrative for Lincoln Electric points to a fair value of about $304.91. This frames the current discount as a test of whether the automation and margin story plays out as expected.
Ongoing growth in Lincoln Electric Holdings automation backlog, with 6 to 9 months of visibility and management guidance for high single-digit organic growth in the segment, points to further demand for higher value cells and cobots that can support revenue growth and a move toward mid-teens EBIT margins.
See why 5 investors see Lincoln Electric Holdings as 15% undervalued.
Result: Fair Value of $304.91 (UNDERVALUED)
Still, the bullish story around Lincoln Electric meets some clear tripwires if input cost inflation erodes pricing power or if automotive related demand remains weak.
Find out about the key risks to this Lincoln Electric Holdings narrative.
Another View: Lincoln Electric on earnings multiples
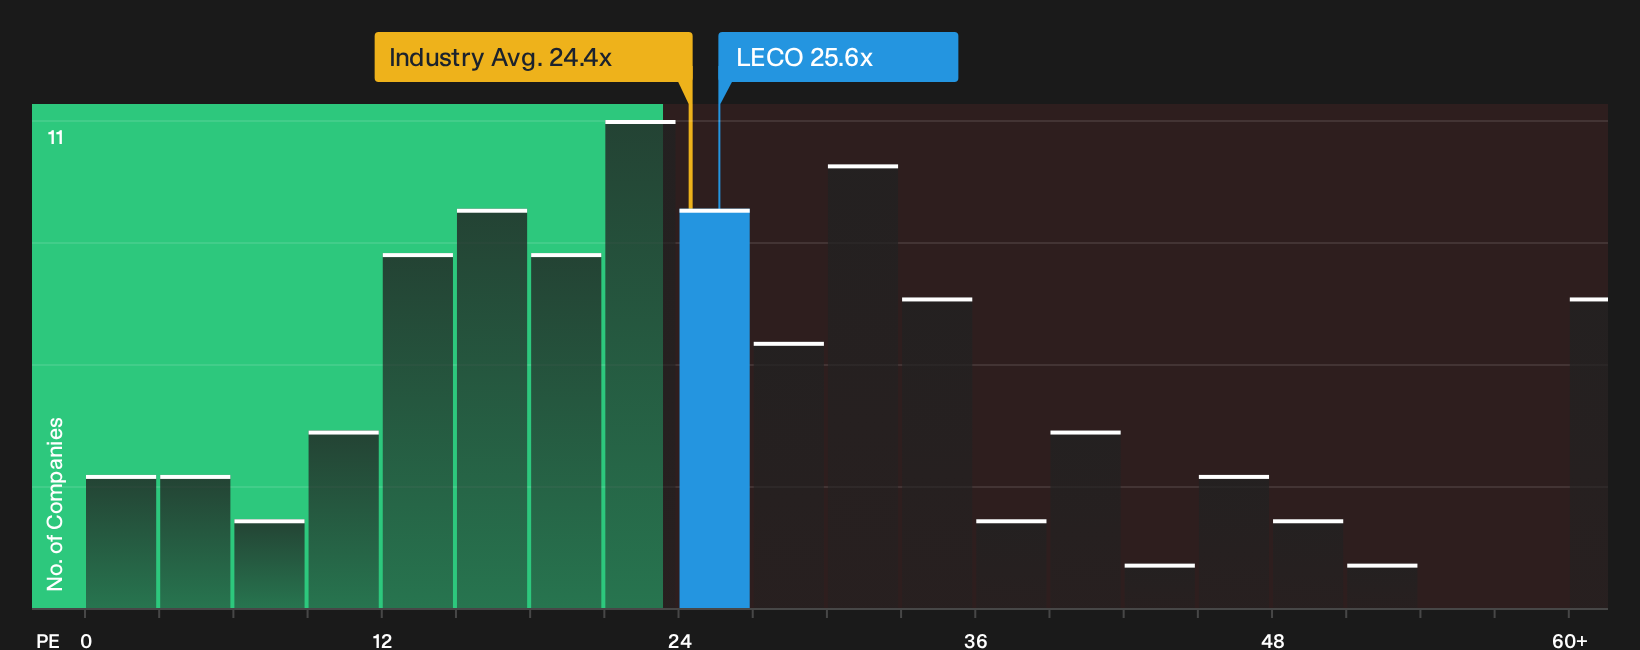
The story shifts when you swap fair value models for a straight P/E check on Lincoln Electric. At about 25.6x earnings, the stock trades above the US Machinery group on 24.5x and above a fair ratio closer to 21.8x, which points to less room for error if expectations slip.
For investors who prefer to anchor on simple earnings multiples rather than cash flow models, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed mood around Lincoln Electric has you on the fence, move quickly from headlines to hard numbers and pressure test the bullish and cautious angles for yourself by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lincoln Electric?
If Lincoln Electric has sharpened your focus on quality, do not stop here. Broaden your watchlist with other clear, numbers based ideas that might suit your style.
- Target potential mispricings by scanning a curated set of 29 high quality undervalued stocks that pair robust cash generation with conservative balance sheets.
- Lock in potential income streams by reviewing 8 dividend fortresses that combine higher yields with an emphasis on resilience.
- Strengthen capital preservation by filtering for 31 resilient stocks with low risk scores where financial risk scores tilt toward stability over speculation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com