


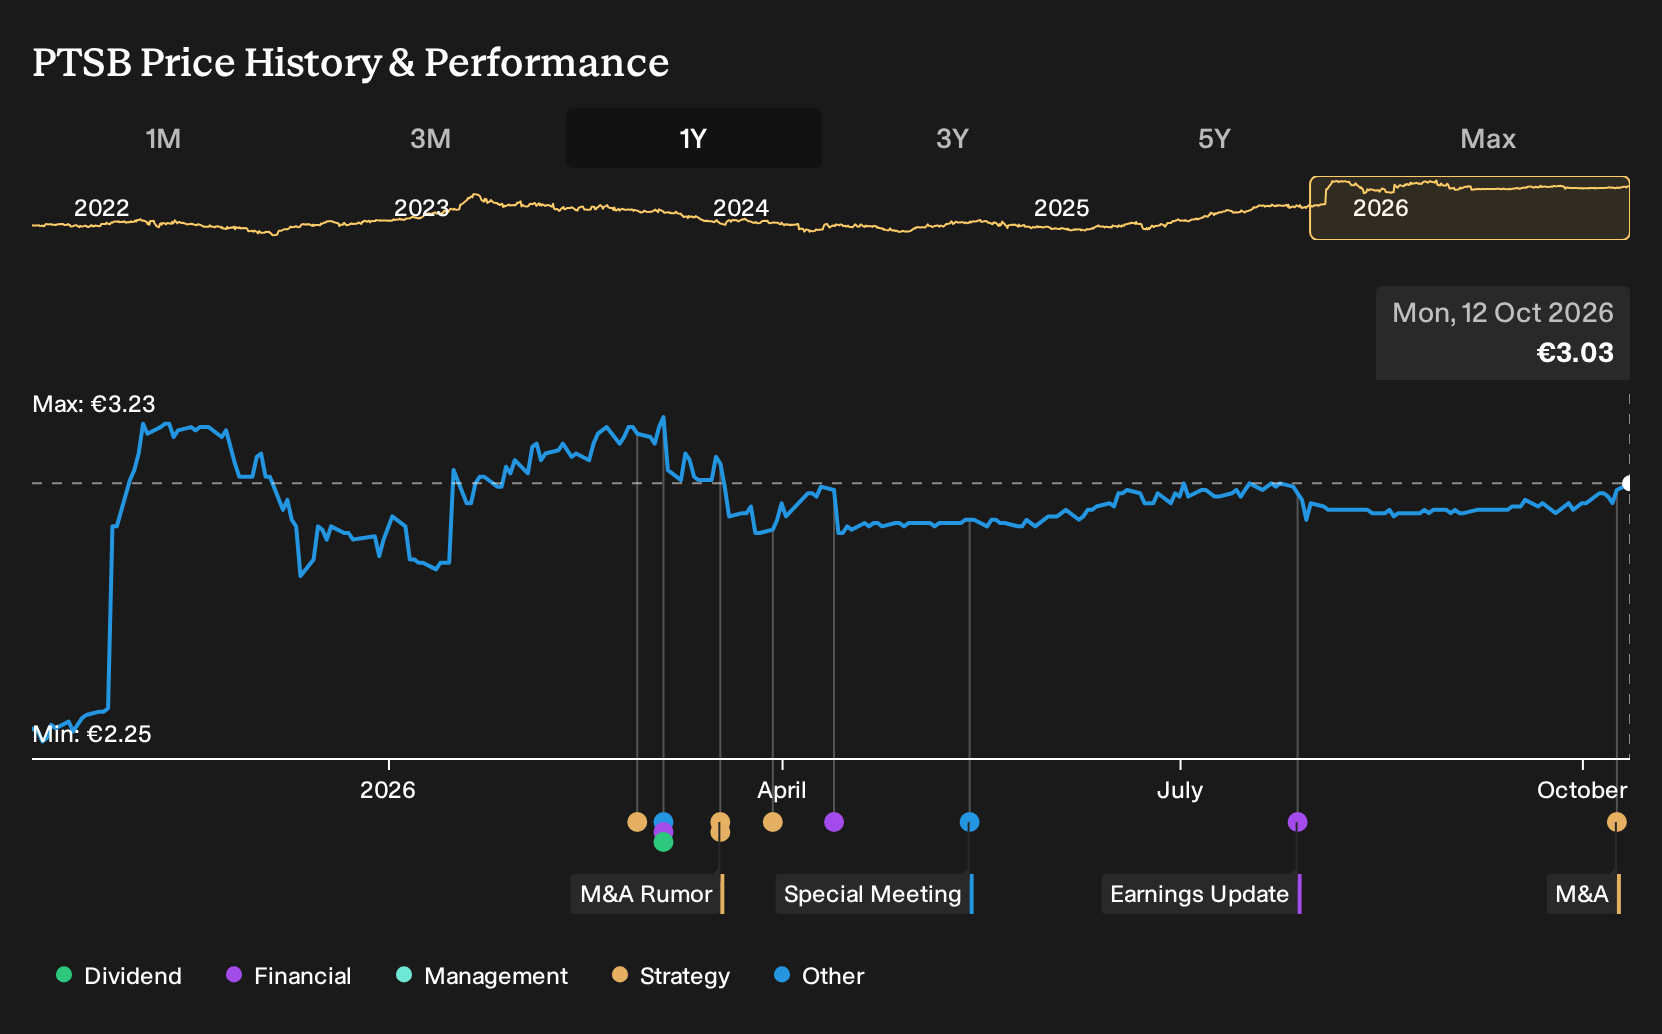
If you had bought Permanent TSB Group on 12 October 2025, the past year did not punish your patience. For Permanent TSB Group shareholders, the return over the past year was 33.7%, including dividends. That figure looks straightforward today, yet early buyers were weighing very different stories about mortgage concentration, digital execution and Ireland’s banking reshuffle. Were they really paying for transformation, or mostly for the chance that someone else might eventually bid?
The easy part of this move is behind Permanent TSB Group. Zero in on 181 high quality undervalued stocks for companies trading below our estimates.
The Argument Investors Faced On Permanent TSB Group
The shares cost €2.3 at the start of the period, and anyone looking at Permanent TSB Group had to decide which story felt more realistic.
The bullish narrative pointed to a Fair Value of €3, a price that would only make sense if digital transformation and new deposit channels really did lift fee income and allow the Ulster Bank assets to drop the cost to income ratio sharply.
The bearish side argued for a Fair Value of €1.31 based on the idea that mortgage overexposure, demographic risk, and pressure on net interest margins could cap loan growth and squeeze profitability despite all the promised digital upgrades.
What The Evidence Did To The Permanent TSB Group Argument
The clearest development for Permanent TSB Group was BAWAG agreeing to acquire the bank in a €1.62b cash deal, backed by Ireland’s Minister for Finance. That outcome tilted toward the bullish takeover angle, while the move from a €6m loss in H1 2025 to a €25m profit and a net margin shift from -1.9% to 7.4% gave both sides fresh numbers. Overall, the evidence cut both ways.
The lesson is simple. When a thesis hinges on either earnings power or a potential bid, track both. Watch profit and margin trends in the accounts and, in parallel, any formal deal proposals or regulatory filings that change who might own the business.
What Permanent TSB Group's Price Seems To Assume Now
Permanent TSB Group changes hands at €3.03 today, and the selected Narrative places its Fair Value below that level. The gap rests on a view that mortgage concentration, cost to income and rate sensitivity still weigh heavily on long term economics despite capital relief and the agreed BAWAG deal.
For you as a buyer, the live question is whether Permanent TSB Group can turn capital headroom, cost programs and lending diversification into steadier earnings. The central assumption to test is that this bank can do that while keeping Irish mortgage risk contained enough that one product line does not dominate future volatility.
"Although Permanent TSB Group Holdings has secured approval for new mortgage risk models that cut risk weighted assets and lift capital ratios, the benefit depends on converting that capital into lending at acceptable spreads, and the recent 3 to 4% fall in total operating income as rates eased suggests that redeployment could come with weaker revenue and earnings resilience."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 48% below our estimate - builds recurring overhaul work as dual fuel engines reshape service lifecycles.
- Company 2 - 31% below our estimate - converts a sizeable resource inventory into longer operations while managing extraction challenges.
- Company 3 - 17% below our estimate - extends an omni channel setup as new sites reinforce everyday product demand.
Those are three of them. See every one of the 202 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com