


- Victory Capital Holdings reported total client assets of $355.5b as of 30 September 2026, with third quarter long term net inflows of $11.7b and plans to release full financial results in early November.
- The combination of fresh inflows and a larger asset base gives investors more timely insight into how Victory Capital Holdings is attracting and retaining client money ahead of earnings.
- We will now examine how Victory Capital Holdings' $11.7b long term net inflows could influence its broader investment narrative.
Scan how Victory Capital Holdings' inflow story compares to other asset managers by running the curated list of solid balance sheet and fundamentals (25 results) that screens for firms with resilient financial footing.
Victory Capital Holdings Investment Narrative Recap
To own Victory Capital Holdings, you need to be comfortable with an asset manager that leans on scale, product breadth and acquisitions in a fee pressured industry. The latest figure of US$355.5b in client assets with US$11.7b long term net inflows puts the spotlight back on organic traction. The near term swing factor remains whether those inflows are broad based and repeatable across channels and products.
The biggest risk still looks tied to fee compression and any return to sustained outflows, which would test earnings resilience against rising costs and acquisition integration. If the inflows prove temporary or are concentrated in lower fee strategies, that could dilute revenue yield on assets and limit how much operating leverage Victory Capital Holdings can extract from its larger platform.
With full third quarter financials due after the close on 4 November 2026, the upcoming report is a clear check on how these US$11.7b of net inflows translate into revenue, margins and cash generation. Investors will be able to see whether flows skew toward higher fee active mandates, ETFs or lower fee products, and how that mix interacts with any ongoing fee pressure disclosed by management.
The call on 5 November also matters for the overall risk framework. Management commentary on client retention, realized fee rates and the integration progress of prior acquisitions will help frame how durable this quarter's inflows might be. For anyone tracking catalysts, the combination of flow data, fee trends and expense discipline around acquisitions is likely to shape views on Victory Capital Holdings' earnings quality heading into 2027.
Victory Capital Holdings' narrative projects US$1.9b revenue and US$1.0b earnings by 2029. This implies 7.1% yearly revenue growth and an earnings increase of roughly US$644.5m from US$355.5m today.
Uncover why Victory Capital Holdings' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
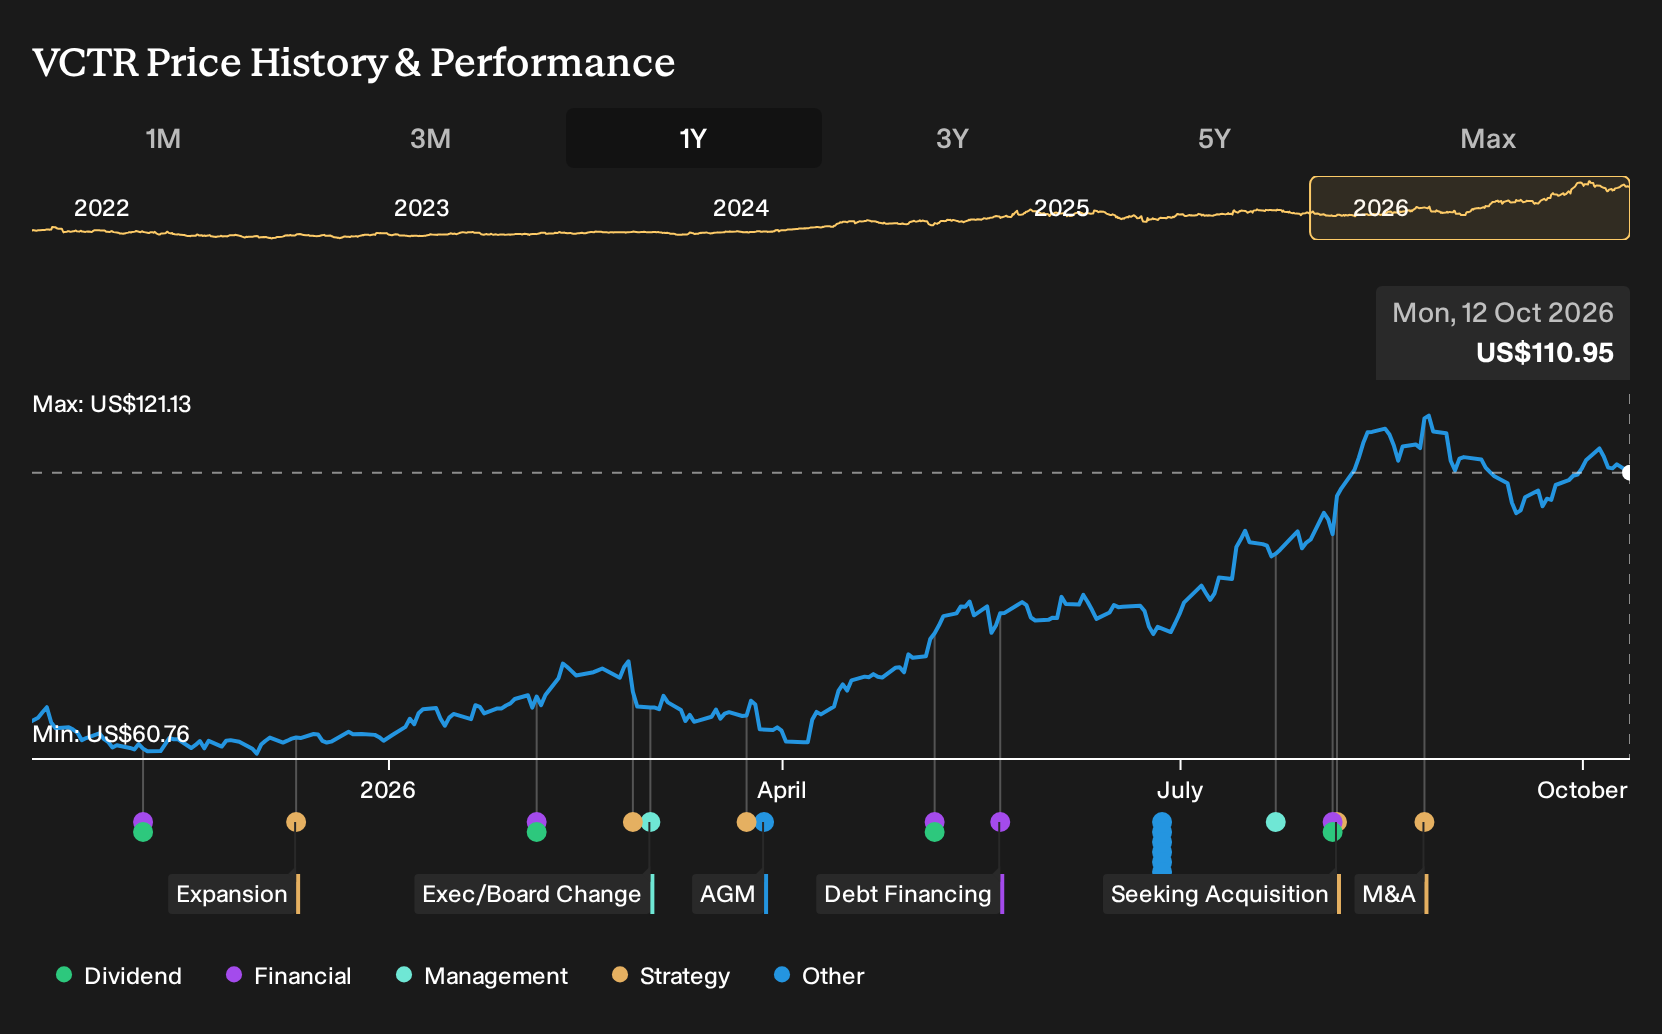
Exploring Other Perspectives
One alternate view focuses less on inflows at Victory Capital Holdings and more on whether fee pressure and the tilt to passive products cap long run upside. The most cautious analysts were pencilling in US$1.9b revenue and about US$974.4m earnings by 2029. That is still growth, yet meaningfully below the more optimistic narrative. These estimates all pre date the latest US$11.7b net inflow number, so you may want to compare both perspectives and decide which assumptions feel closer to how you see the business.
Explore 2 other Victory Capital Holdings fair value estimates, including one that suggests there could be as much as 25% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Victory Capital Holdings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Victory Capital Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Victory Capital Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Victory Capital Holdings?
If Victory Capital Holdings is already on your radar, it can help to compare it with a wider set of opportunities that share some of the qualities you care about most. Use the Simply Wall St Screener to line up alternatives side by side and stress test your own thesis against other options.
- If you want income resilience, start with companies that combine higher yields with balance sheet strength by reviewing 8 dividend fortresses.
- If value is your focus, contrast Victory Capital Holdings with businesses that screen as potentially mispriced on quality and fundamentals through 29 high quality undervalued stocks.
- If capital preservation matters most, filter for businesses with sturdier finances and more measured risk profiles using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com