


Valued at a market cap of $31.8 billion, San Diego, California-based DexCom, Inc. (DXCM) is a medical device company that focuses on the design, development, and commercialization of continuous glucose monitoring (CGM) systems for the management of diabetes and metabolic health in the United States and internationally.
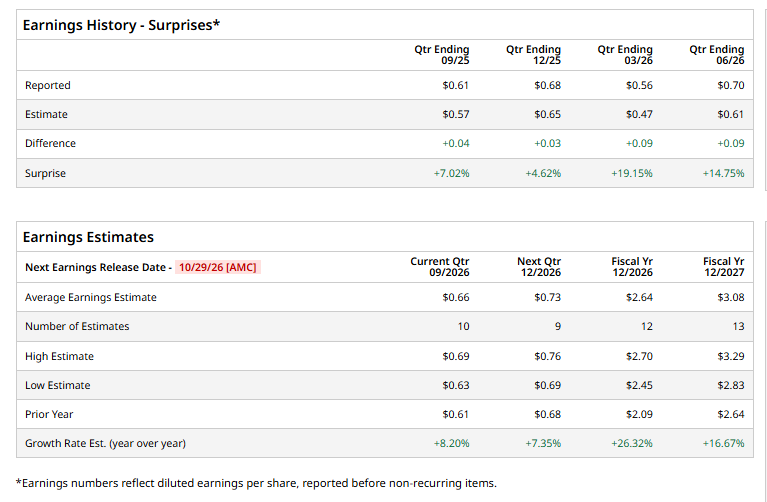
DXCM is expected to release its Q3 2026 earnings after the market closes on Thursday, Oct. 29. Ahead of the event, analysts expect the company’s EPS to be $0.66 on a diluted basis, up 8.2% from $0.61 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in each of its last four quarters.
For fiscal 2026, analysts project the company’s EPS to be $2.64, up 26.3% from $2.09 in fiscal 2025. Moreover, its EPS is expected to rise 16.7% year over year to $3.08 in fiscal 2027.
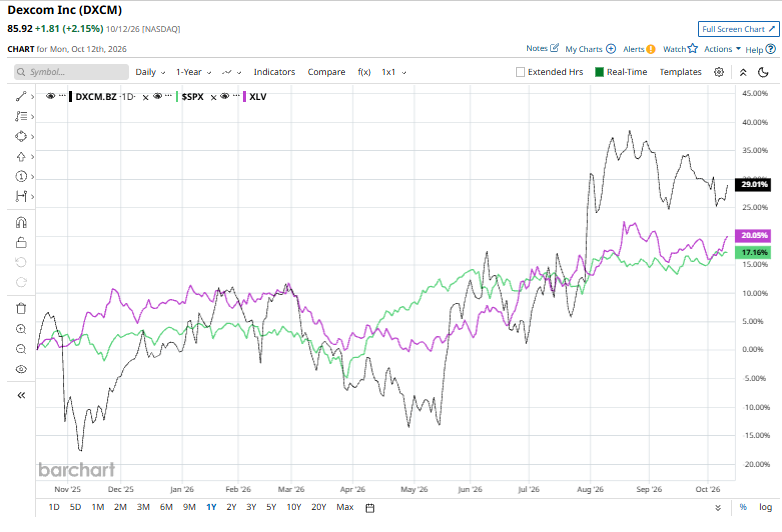
DXCM stock has surged 31.9% over the past 52 weeks, outpacing the S&P 500 Index’s ($SPX) 19.2% rise and the State Street Healthcare Select Sector SPDR ETF’s (XLV) 21% rise during the same time frame.
DexCom has outpaced the broader market over the past year, supported by steady organic revenue growth, improving cash flow generation, and stronger returns on invested capital. The company’s organic revenue growth averaged 12% over the past two years, highlighting sustained demand for its continuous glucose monitoring systems without relying on acquisitions.
Meanwhile, its free cash flow margin expanded by 20.2 percentage points over the past five years, strengthening its financial flexibility to fund growth initiatives and shareholder returns. Improving capital efficiency has further bolstered investor confidence in DexCom’s ability to capitalize on the expanding diabetes-care market.
Analysts are highly optimistic about DXCM, with the stock having a “Strong Buy” rating overall. Among the 29 analysts covering the stock, 25 are recommending a “Strong Buy,” one suggests a “Moderate Buy,” and three recommend a “Hold.” DXCM’s average analyst price target is $96.26, indicating an upside of 12% from the current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.