


Vistra has seen its share price move sharply over recent years, and that kind of track record naturally raises a question about whether the current US$158.13 level is supported by the company’s earnings power. With fresh headlines around government support for its nuclear fleet, the issue now is how much of that story is already embedded in the valuation.
- Over the past 5 years, Vistra has delivered a very large share price gain, which puts a lot of weight on the question of whether its current earnings profile can carry that kind of performance.
- The planned US$4b to US$4.2b federal loan package for upgrades at several nuclear plants may support expectations around longer term earnings, capital intensity and the timing of cash flows for the business.
- There is a second opinion on Vistra worth weighing. See what analysts think Vistra's shares could be worth.
The stock's next move may depend on whether Vistra's current earnings justify the price that investors are paying today.
If you want to stress test this same earnings question beyond Vistra and its nuclear story, you can line it up against 43 power grid technology and infrastructure stocks.
Does Vistra Look Fairly Valued on Earnings?
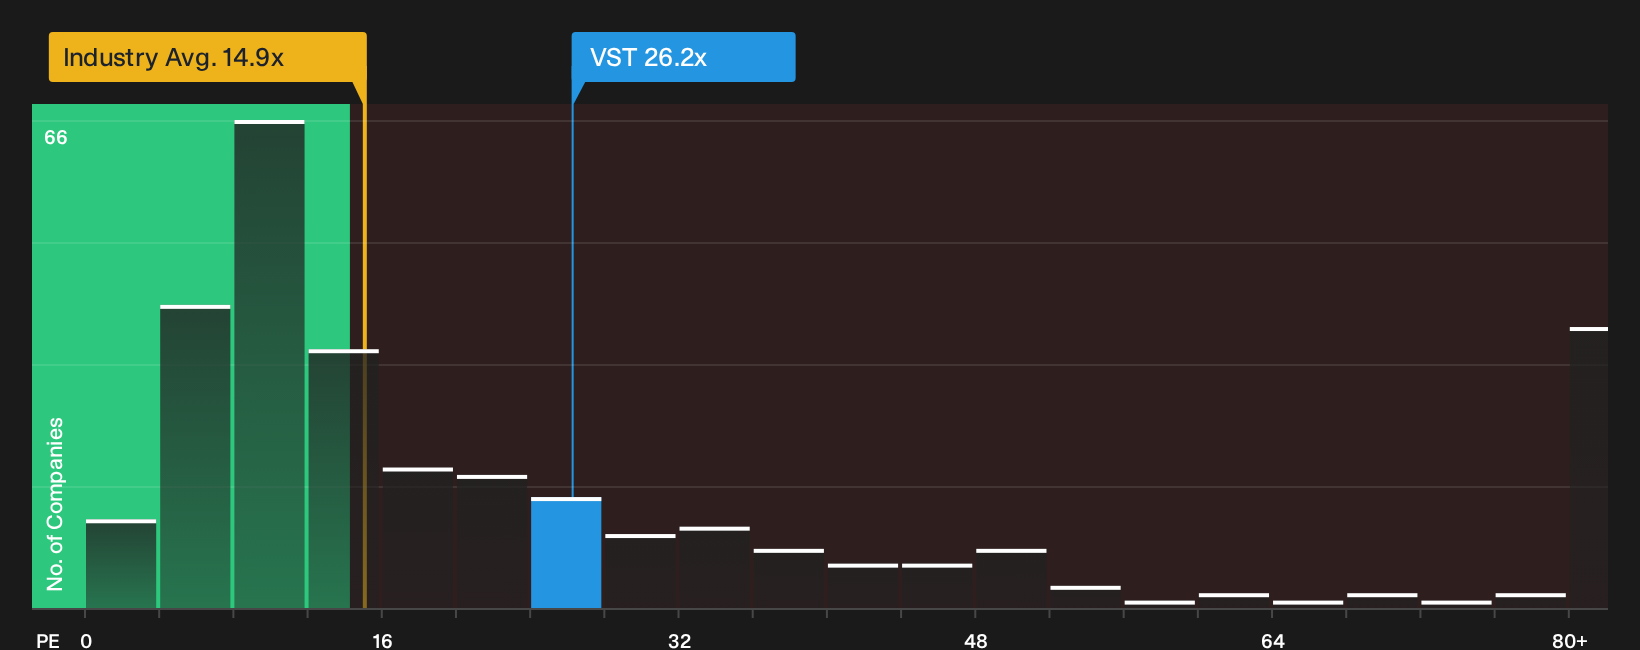
The P/E ratio works reasonably well for Vistra because earnings are a key lens investors use when thinking about regulated and contracted power assets. At the current price, the stock trades on about 26.2x earnings, compared with a Renewable Energy industry average near 14.9x and a peer group closer to 19.2x, so investors are paying a visibly higher price for each dollar of profit.
That premium lines up with a Fair Ratio that points to a level in the same broad zone as today’s multiple. This suggests the current earnings valuation is about right rather than extremely low or overly stretched. Despite the fresh attention from the planned US$4b to US$4.2b federal loan support for its nuclear fleet, the market is already assigning Vistra a P/E that reflects elevated expectations relative to many utilities, so you would want to be comfortable with that earnings profile before relying on this metric alone. Explore the numbers behind Vistra's P/E valuation.
The Vistra Narrative: What Would Justify Today's Price?
Narratives on Vistra pick up where the P/E debate leaves off and outline which paths for earnings, margins and reinvestment would need to occur for the stock to be worth materially more or less than today’s price on Simply Wall St’s Community page. Each story links Vistra's potential catalysts and key risks to a specific view of fair value so you can track over time which version of events is actually unfolding.
Vistra brings out two very different readings from the community, with one group seeing a sizeable discount and another flagging a valuation stretch.
Bull case: 26% undervalued
"Current earnings guidance, cash generation plans and the track record of more than $6.5b in buybacks at an average share price of about $38, alongside analyst targets mostly in the $169 to $298 range, together imply that the market price still assumes a significant discount to the cash returns and growth already visible in Vistra’s plan…"
Discover why this Narrative puts Vistra at 26% undervalued.
Bear case: 22% overvalued
"At $200, investors can convince themselves a company is destined to dominate the next decade…"
Explore why this Narrative puts Vistra at 22% overvalued.
One last Vistra check that sits beyond today’s share price
You have the snapshot on Vistra’s current multiple and the stories around it, but there is still the question of where professionals expect this business to be a few years from now. Explore where analysts expect Vistra to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com