


In the last week, the U.S. market has stayed flat, yet over the past 12 months, it has experienced a notable rise of 14%, with earnings expected to grow by 17% annually. In such an environment, growth companies with strong insider ownership can be particularly appealing as they often reflect confidence from those closest to the business in its potential for future success.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 64.2% |
| Sable Offshore (SOC) | 11.4% | 76% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.4% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.2% |
Let's explore several standout options from the results in the screener.
Esquire Financial Holdings (ESQ)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Esquire Financial Holdings, Inc. is the bank holding company for Esquire Bank, National Association, offering commercial banking products and services to legal professionals, small businesses, and retail customers in the United States with a market cap of $1.42 billion.
Operations: The company generates revenue primarily from its community banking segment, which amounted to $149.31 million.
Insider Ownership: 11.5%
Return On Equity Forecast: N/A (2029 estimate)
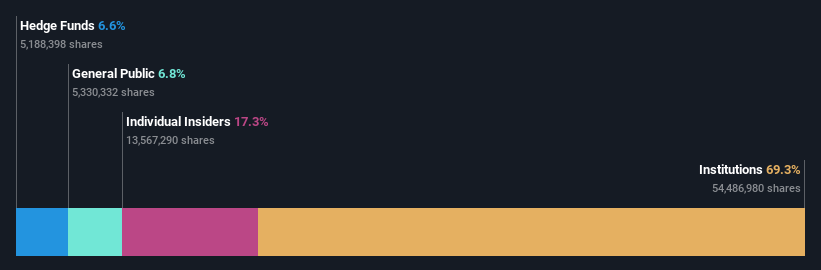
Esquire Financial Holdings has seen significant earnings growth, projected at 51.5% annually over the next three years, outpacing the US market. Despite this robust forecast, insider selling was notable in recent months. The company's merger with Signature Bancorporation could enhance its strategic positioning. However, shareholders faced dilution last year and no substantial insider buying occurred recently. Esquire trades at a significant discount to estimated fair value and reported strong Q2 financial results with increased net interest income and net income year-over-year.
- Delve into the full analysis future growth report here for a deeper understanding of Esquire Financial Holdings.
- Our valuation report unveils the possibility Esquire Financial Holdings' shares may be trading at a premium.

Starling Oncology (STLN)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Starling Oncology, Inc. is an oncology company that offers a range of oncology services in the United States with a market cap of $705.26 million.
Operations: The company's revenue is derived from Patient Services ($237.95 million), Specialty Pharmacy ($343.46 million), and Clinical Trials & Other ($5.84 million).
Insider Ownership: 12.8%
Return On Equity Forecast: N/A (2029 estimate)
Starling Oncology is poised for substantial growth with expected revenue increases of 26.1% annually, outpacing the US market. Despite a volatile share price and recent significant insider selling, the company is set to become profitable within three years. Recent developments include its addition to the S&P Health Care Services Select Industry Index and launching Starling Nexus, a platform aimed at streamlining oncology care processes. The company trades at favorable value compared to industry peers.
- Unlock comprehensive insights into our analysis of Starling Oncology stock in this growth report.
- Our expertly prepared valuation report Starling Oncology implies its share price may be lower than expected.

Commerce.com (CMRC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Commerce.com, Inc. operates an artificial intelligence-driven commerce ecosystem globally, with a market cap of $289.18 million.
Operations: The company generates revenue from its Internet Information Providers segment, totaling $346.90 million.
Insider Ownership: 10.8%
Return On Equity Forecast: 41% (2029 estimate)
Commerce.com is experiencing strong earnings growth, with a 33.4% annual increase over the past five years and forecasts of 132.32% per year moving forward. Despite its high volatility and slower revenue growth projection compared to the market, it trades at a good value relative to peers. Recent product enhancements in AI-driven catalog enrichment aim to boost merchant capabilities significantly. The company has initiated a US$50 million share buyback program, highlighting confidence in its financial position.
- Dive into the specifics of Commerce.com here with our thorough growth forecast report.
- In light of our recent valuation report, it seems possible that Commerce.com is trading behind its estimated value.
Seize The Opportunity
- Get an in-depth perspective on all 188 Fast Growing US Companies With High Insider Ownership by using our screener here.
- Contemplating Other Strategies? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com