


Marvell Technology (MRVL) shares have had an outstanding run, gaining around 224% year-to-date. While the rally has made the stock more expensive, its strong growth outlook suggests room for further gains.
The core thesis for buying Marvell stock rests on the staggering acceleration of its addressable market and management’s aggressive yet highly credible multi-year financial targets. At its recent Investor Day event, Marvell’s management laid out a massive long-term growth strategy driven by artificial intelligence (AI) infrastructure demand. Marvell also raised its near-term growth projection, signaling accelerating growth.
As spending on data centers and AI technology continues to increase, Marvell stands to benefit from stronger demand for its products and solutions. Its top and bottom lines are expected to grow rapidly, giving MRVL stock a solid boost.
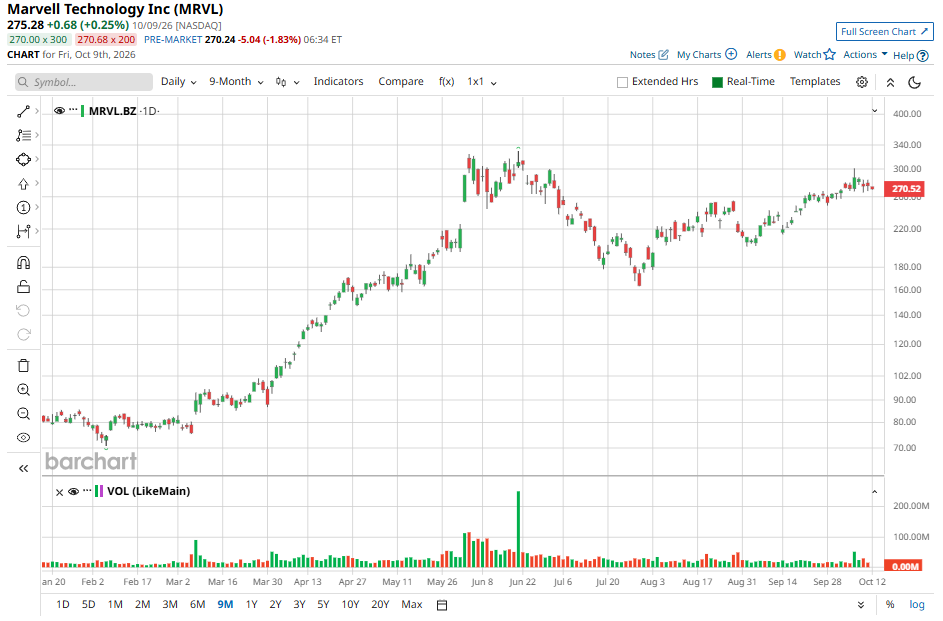
Marvell Set to Deliver Substantial Growth
Marvell appears well-positioned to capitalize on the expanding AI infrastructure market and sustain strong growth through the end of the decade. The company’s decision to increase its revenue outlook highlights stronger demand for AI-related technologies and improving opportunities across the broader semiconductor industry.
In the near term, management expects revenue to reach about $20 billion in fiscal 2028, $2 billion higher than its previous forecast and around 67% YOY. Overall, Marvell projects its revenue to increase at a CAGR of 55% to 60% through fiscal 2031.
The data center segment is expected to remain a major contributor to Marvell’s growth, supported by demand across multiple AI infrastructure applications. Management anticipates that data center revenue will increase at a CAGR of 65% between fiscal 2026 and fiscal 2031, highlighting the strong demand expected over the next several years.
Rising capital expenditures by hyperscale cloud providers are providing a significant tailwind. Marvell’s presence in several essential AI infrastructure markets, including high-speed optical connectivity, networking and switching, and custom silicon, positions the company to benefit from continued investment in AI computing capacity.
Within data centers, interconnect is expected to be a key growth driver. Demand for 800G optical products remains strong, while newer 1.6T solutions could contribute more to revenue starting in fiscal 2028. Marvell expects its interconnect business to grow at a 65% CAGR through fiscal 2031. Its switching and storage businesses are also expected to expand, with revenue projected to grow at a 45% CAGR over the same period.
Custom silicon offers another significant growth opportunity. Marvell expects this business to grow at an 80% CAGR through fiscal 2031, with revenue projected to more than triple in fiscal 2029 compared with fiscal 2028. As demand for custom chips increases, this segment could become an increasingly important contributor to the company’s overall growth and profitability.
Marvell’s expanding custom silicon business and improving operating efficiency could drive significant earnings growth in the coming years. Management expects profits to grow faster than revenue, with EPS potentially surpassing $30 by fiscal 2031. In the near term, analysts forecast MRVL’s EPS to rise to $5.99 in fiscal 2028. This indicates that Marvell’s EPS will likely grow at a solid pace between fiscal 2028 and fiscal 2031.
Time to Load Up on Marvell Stock
Marvell’s accelerating growth outlook, expanding custom silicon business, and strong exposure to AI data center infrastructure provide a compelling case for buying the stock. Management’s improved revenue outlook and projected annual revenue growth of 55%–60% through fiscal 2031 point to significant expansion opportunities. Meanwhile, better operating efficiency could help earnings grow even faster than revenue.
While the stock’s recent rally raises valuation concerns, continued investment in AI infrastructure and rising demand for high-speed connectivity and custom semiconductors could drive further upside.
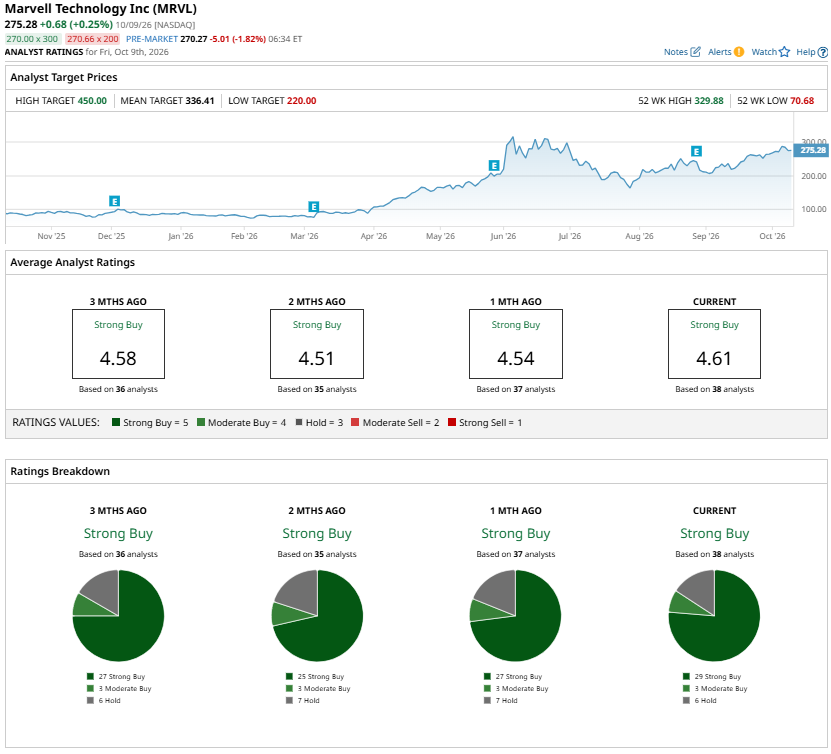
Wall Street analysts remain optimistic about Marvell, with the stock carrying a “Strong Buy” consensus rating. The highest price target of $450 suggests about 63% upside from its recent close of $275.28.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.