


Intapp stock: why a new client go-live is drawing attention
Intapp (INTA) is on investors’ radar after Mauldin & Jenkins went live with Intapp Employee Compliance, shifting from manual, email-based independence checks to an automated, centralized platform ahead of a key 2026 deadline.
Recent trading indicates that investors are paying attention to Intapp. The share price is at US$39.64, with a 90 day share price return of 42.9% and a 1 year total shareholder return of 6.67%. This points to strong short term momentum alongside steadier multi year gains.
Scan beyond Intapp and see how other compliance and workflow specialists are moving by checking the hand picked 20 high quality undiscovered gems in this corner of the market.
Intapp appears to be a solid specialist in compliance and deal software, and the recent Mauldin & Jenkins go-live reinforces that story. After a 42.9% move in 90 days, is that strength already fully reflected in the price, or not?
Most Popular Narrative: 5% Undervalued
Analysts following Intapp see a fair value of about $41.57 against the recent $39.64 close, leaving only a modest valuation gap and placing greater emphasis on whether the AI and workflow strategy develops as anticipated.
Intapp's recent investments in AI capabilities, including the launch of Intapp DealCloud Activator and the transformed Intapp Time product, are designed to drive client engagement and operational efficiencies. These innovations are expected to bolster revenue by enhancing product appeal and encouraging cloud adoption among existing and potential clients.
See why 15 investors see Intapp as 5% undervalued.
Result: Fair Value of $41.57 (UNDERVALUED)
Still, if Intapp’s partner-led delivery stumbles or the shift to cloud and AI tools fails to keep clients engaged, that 5% undervalued narrative could unravel fast.
Find out about the key risks to this Intapp narrative.
Another View on Intapp’s Valuation
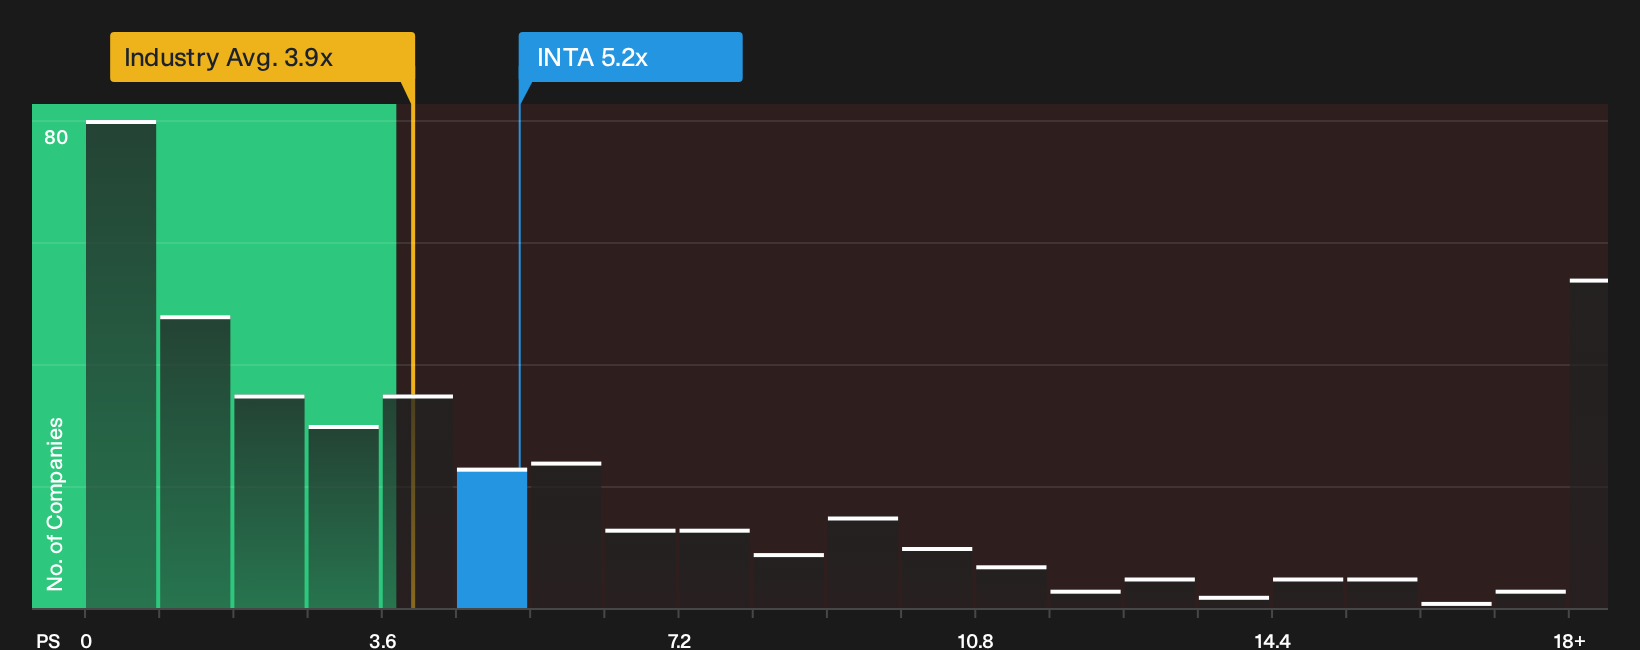
The earlier narrative leans on future cash flows and analyst targets. The P/S tells a slightly different story. Intapp trades around 5.2x sales, richer than the US Software average at 4x and above a fair ratio of 4.5x, although below peers at 6.3x. Is that premium comfort or risk for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling that Intapp’s story leans positive but still unfinished? Act while the data is fresh and weigh the upside yourself with the 2 key rewards.
Looking for more investment ideas beyond Intapp?
Do not stop at Intapp. The best opportunities often sit just outside your current watchlist, so widen the net before prices move without you.
- Target potential mispricing by scanning a curated pool of quality companies that screens for value using the 29 high quality undervalued stocks.
- Build a steadier foundation for your portfolio by hunting for companies with robust finances through the list of solid balance sheet and fundamentals (25 results).
- Balance risk and reward by focusing on businesses with more resilient profiles using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com