


Institutional interest and recent performance set the stage
Intertek Group (LSE:ITRK) has attracted a cluster of Rule 8.3 disclosures from Millennium, Natixis, Balyasny, and Qube, while also delivering a 54.4% total return over three years.
That mix of institutional exposure and prior shareholder gains raises a straightforward question for you: Does the current share price around £58.95, and the market value of roughly £9.0b, fairly reflect the cash the business is expected to generate?
Recent trading has been quiet in the short term, with only modest share price moves over days and weeks. However, the year-to-date share price return of 29.45%, alongside a 24.95% total shareholder return over one year, suggests momentum has been building as investors reassess Intertek Group’s cash flow profile and risk outlook in light of fresh institutional disclosures.
Spot similar institutional interest and cash flow stories to Intertek Group across a curated 5 high quality undiscovered gems that might be flying under most investors' radar.Intertek Group looks like a solid cash generator with revenue and net income growth, and the share price has already moved sharply. Are you paying up for quality, or is there still mispricing in the cash flows?
Most Popular Narrative: 1% Overvalued
Intertek Group’s most followed valuation story puts fair value at £58.49, just below the last close at £58.95, which suggests the market is largely in line with that thesis while still pricing in a small premium.
Ongoing increases in regulatory standards for safety, quality, and especially sustainability are driving more frequent and higher-value product tests (with growing tests per SKU and higher pricing power) in Intertek's core Consumer Products and Electrical divisions, supporting strong like-for-like revenue growth and margin expansion.
See why 39 investors see Intertek Group as 1% overvalued.
Result: Fair Value of £58.49 (ABOUT RIGHT)
Still, Intertek Group’s narrative could be challenged if revenue growth in slower divisions, such as Health and Safety or World of Energy, lags current expectations.
Find out about the key risks to this Intertek Group narrative.
Another view on Intertek Group’s pricing power
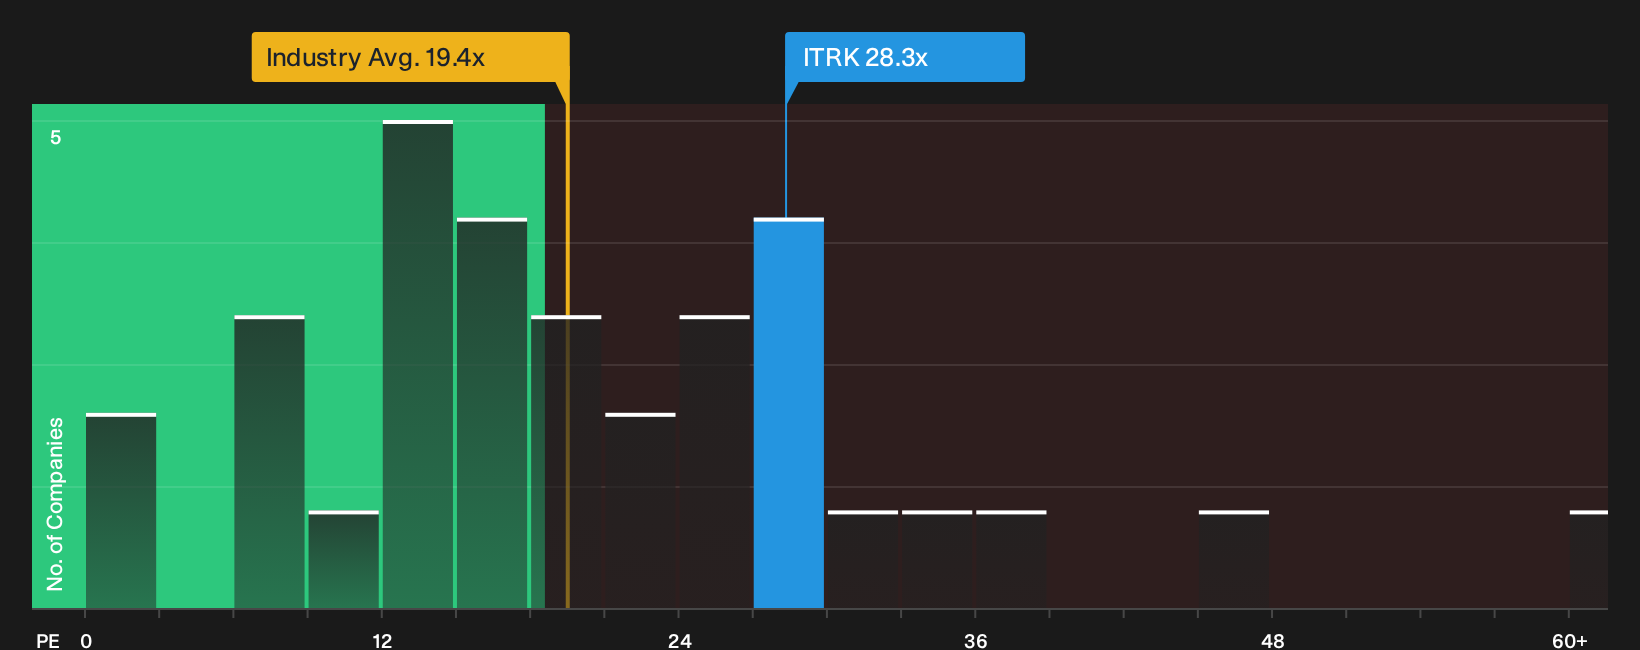
The first narrative leans on analyst targets that frame Intertek Group as roughly fairly valued around £58.49. A different lens uses the current P/E of 28.3x against peers at 17.7x and a fair ratio of 27.7x, which points to a richer tag and limited margin for error. Is the premium worth paying if growth stays moderate rather than exceptional?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Intertek Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals so far for Intertek Group, with both risks and rewards on the table, mean you are better off weighing the evidence yourself and deciding quickly where you stand, then checking the full picture through 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Intertek Group?
If Intertek Group has you thinking harder about price, quality, and risk, it can be useful to line up a few more potential candidates side by side.
Use the Simply Wall Street Screener to quickly compare different types of opportunities that might fit your goals before the market re-prices them.
- Target stability first and let potential upside come second by scanning a 4 resilient stocks with low risk scores that aims to keep unwanted surprises in check.
- Hunt for quality at a discount and look for a 7 high quality undervalued stocks that could offer robust fundamentals at prices the market has not fully recognised yet.
- Build a foundation of financial strength and staying power by combing through a list of solid balance sheet and fundamentals (9 results) that prioritises resilient balance sheets and cleaner leverage profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com