


With a market cap of $20.7 billion, CMS Energy Corporation (CMS) operates across three segments: Electric Utility, Gas Utility, and NorthStar Clean Energy, providing electricity and natural gas to millions of residential, commercial, and industrial customers. It manages extensive infrastructure and generates power from a diverse mix of sources including coal, gas, nuclear, and renewables.
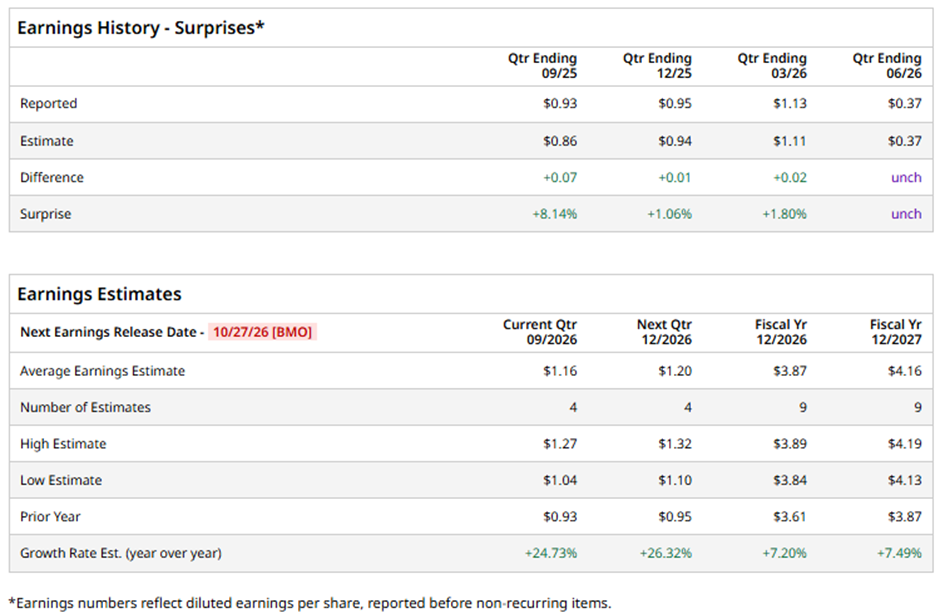
The Jackson, Michigan-based is set to announce its fiscal Q3 2026 results before the market opens on Tuesday, Oct. 27. Ahead of this event, analysts forecast CMS to report an adjusted EPS of $1.16, up 24.7% from $0.93 in the year-ago quarter. It has surpassed or met Wall Street's earnings estimates in each of the last four quarters.
For fiscal 2026, analysts expect the energy company to report an adjusted EPS of $3.87, a rise of 7.2% from $3.61 in fiscal 2025. Moreover, adjusted EPS is anticipated to grow 7.5% year-over-year to $4.16 in fiscal 2027.
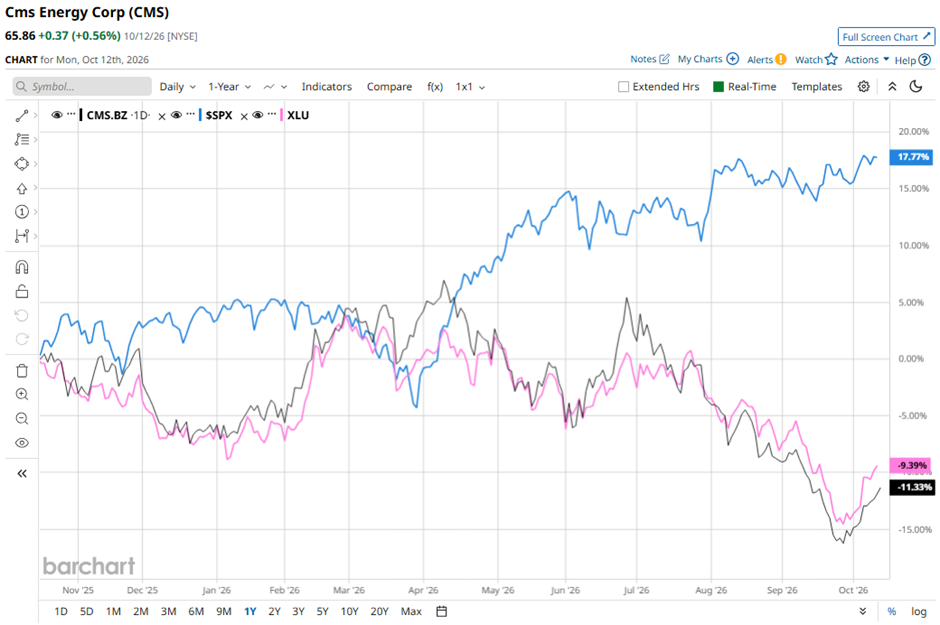
Shares of CMS Energy have declined 11.1% over the past 52 weeks, underperforming both the S&P 500 Index's ($SPX) 19.2% increase and the State Street Utilities Select Sector SPDR ETF's (XLU) 7.7% drop over the same period.
CMS Energy released its Q2 2026 results on Jul. 28. The company decided to exit non-utility renewables development and a weaker-than-expected 2027 earnings outlook. The company forecast 2027 adjusted EPS of $4.08 - $4.17, with the $4.13 midpoint below analysts’ estimate, while restructuring NorthStar Clean Energy and shifting focus toward its regulated utility business. Although Q2 adjusted EPS of $0.37 beat the estimate, net income fell 40.3% to $120 million and operating expenses rose 2.6% to $1.56 billion.
Analysts' consensus view on CMS stock is cautiously optimistic, with a "Moderate Buy" rating overall. Among 16 analysts covering the stock, seven recommend "Strong Buy" and nine suggest "Hold." This configuration is slightly less bullish than three months ago, with eight analysts suggesting a "Strong Buy."
The average analyst price target for CMS Energy is $77.38, suggesting a potential upside of 17.5% from current levels.
On the date of publication, Sohini Mondal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.