


Recent research coverage has pushed ConocoPhillips (COP) into the spotlight after highlighting 10.1% annual revenue growth over the past decade and sizable free cash flow. This has raised fresh questions about what investors are really paying for that profile today.
ConocoPhillips shares have moved to $137.56 after a 2.6% 1-day share price return and a 23.0% 90-day share price return, while the 1-year total shareholder return of 59.8% and 5-year total shareholder return of 120.5% point to strong momentum that recent research coverage is helping keep in focus.
See how ConocoPhillips compares with other cash-generative companies by reviewing our hand picked list of 29 high quality undervalued stocks.
ConocoPhillips now carries a strong growth story and a strong share price run. The real test is whether that mix still leaves investors paying a fair valuation today.
Most Popular Narrative: 6% Undervalued
On the most followed thesis, ConocoPhillips screens on a fair value of $146.08 against the latest $137.56 close, which puts the current share price at a modest discount while still requiring that the cash flow story develops as outlined.
The company’s outlined path to a $7b free cash flow uplift by 2029, supported by a reduction in free cash flow breakevens from the mid US$40s WTI range today to the low US$30s, indicates that potential margin expansion and higher earnings power are not yet fully reflected in recent results.
See why 105 investors see ConocoPhillips as 6% undervalued.
Result: Fair Value of $146.08 (UNDERVALUED)
Still, the whole ConocoPhillips narrative leans on big ticket LNG and conventional projects, so any execution setbacks or higher than planned capital spending could quickly challenge it.
Find out about the key risks to this ConocoPhillips narrative.
Another View: ConocoPhillips On Earnings Multiples
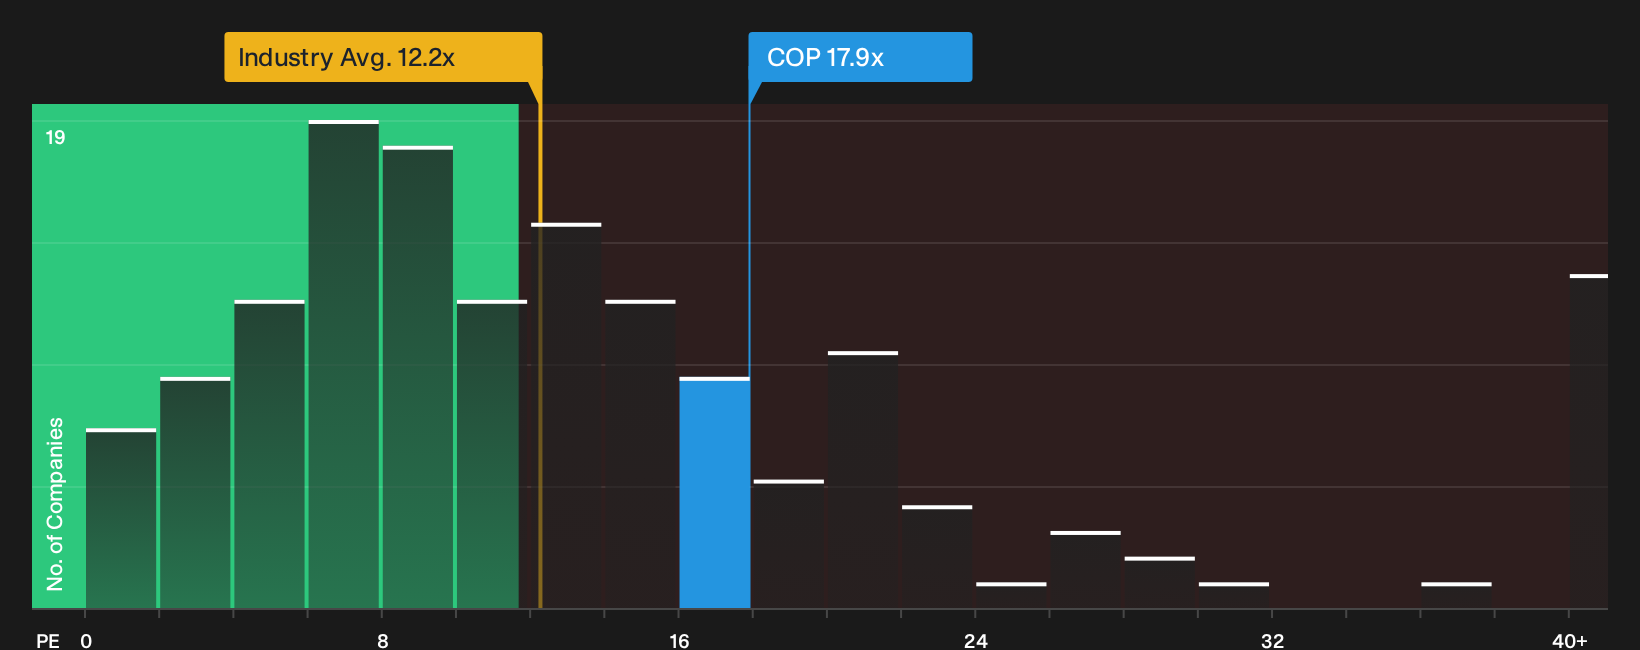
There is a sharp contrast when you look at ConocoPhillips through a simple earnings lens. The stock trades on a P/E of 17.9x, which is richer than the US Oil and Gas industry at 12.2x and only slightly below the peer average of 19x, while the fair ratio sits higher at 19.8x. That mix points to a valuation that already bakes in stronger prospects than the sector but still leaves room for the market to shift closer to the fair ratio. This raises the question of how comfortable investors might be with paying a higher price today for that earnings profile.
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
To visualise how ConocoPhillips trades against peers on this basis, take a look at the P/E comparison chart,
Next Steps
Mixed signals on ConocoPhillips valuation and earnings multiples will mean different things to different investors, so move quickly and interrogate the data yourself before sentiment shifts. To weigh both sides of the story in one place, review the 1 key reward and 2 important warning signs
Looking for more stock ideas beyond ConocoPhillips?
If you stop with ConocoPhillips, you risk missing other opportunities that match your goals. Take a few minutes and widen your radar using these focused screens.
- Target resilience by scanning companies with stronger balance sheets using our curated list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced potential through a data backed shortlist of 20 high quality undiscovered gems.
- Prioritise stability and income by reviewing a focused set of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com