


Alma Media Oyj (HLSE:ALMA) has announced an internal reshuffle, merging its Corporate Communications and Human Resources units into one function led by Executive Vice President Elina Kukkonen to simplify Group Management Team responsibilities.
At a share price of €13.05, Alma Media Oyj has seen its 1-year total shareholder return decline 5.49%, even though the 3-year total shareholder return is up 67.70%. This suggests that long term holders have still experienced strong momentum despite more recent share price softness.
Spot opportunity across the wider media and digital services space by comparing Alma Media Oyj with a hand picked 182 high quality undervalued stocks.The reorganisation and recent share pullback set up a simple tension. Is Alma Media Oyj still pricing in meaningful upside, or has most of the re rating already happened?
Price-to-Earnings of 17x: Is it justified?
On simple earnings terms, Alma Media Oyj trades on a P/E of 17x, while screening work suggests the shares may still sit about 16.2% below an estimated fair value and below analyst targets, at a last close of €13.05.
The P/E ratio compares the current share price with annual earnings per share and gives you a quick sense of how much investors are willing to pay for each euro of profit. For a business built around digital services and media assets, earnings-based measures like P/E often carry weight because cash generation and profitability sit at the center of most investment debates.
Alma Media Oyj is described as good value against an estimated fair P/E of 25.8x, so the market is assigning a lower multiple than that reference level today. That gap suggests investors are applying a discount to its earnings relative to where the fair ratio model indicates pricing could move, even though the stock is described as somewhat expensive versus the broader European Media industry average P/E of 14.9x.
Set against peers, Alma Media Oyj trades on a P/E of 17x compared with a much higher peer group average of 35.1x. With earnings forecast to grow 9.56% per year and Return on Equity estimated to remain high at 25.6%, the current rating appears restrained rather than euphoric.
Explore the SWS fair ratio for Alma Media Oyj.
Result: Price-to-Earnings of 17x (UNDERVALUED)
Still, the story around Alma Media Oyj can change quickly if advertising demand weakens or if its international recruitment platforms face tougher local competition.
Find out about the key risks to this Alma Media Oyj narrative.
Another View: What Does The DCF Say About Alma Media Oyj?
A second lens tells a similar story. Our DCF model values Alma Media Oyj at €15.57 per share, compared with the current €13.05 price. This suggests that the stock is trading below an estimate of future cash flow value. So is the market still underestimating those cash flows, or is the discount deserved?
Look into how the SWS DCF model arrives at its fair value.
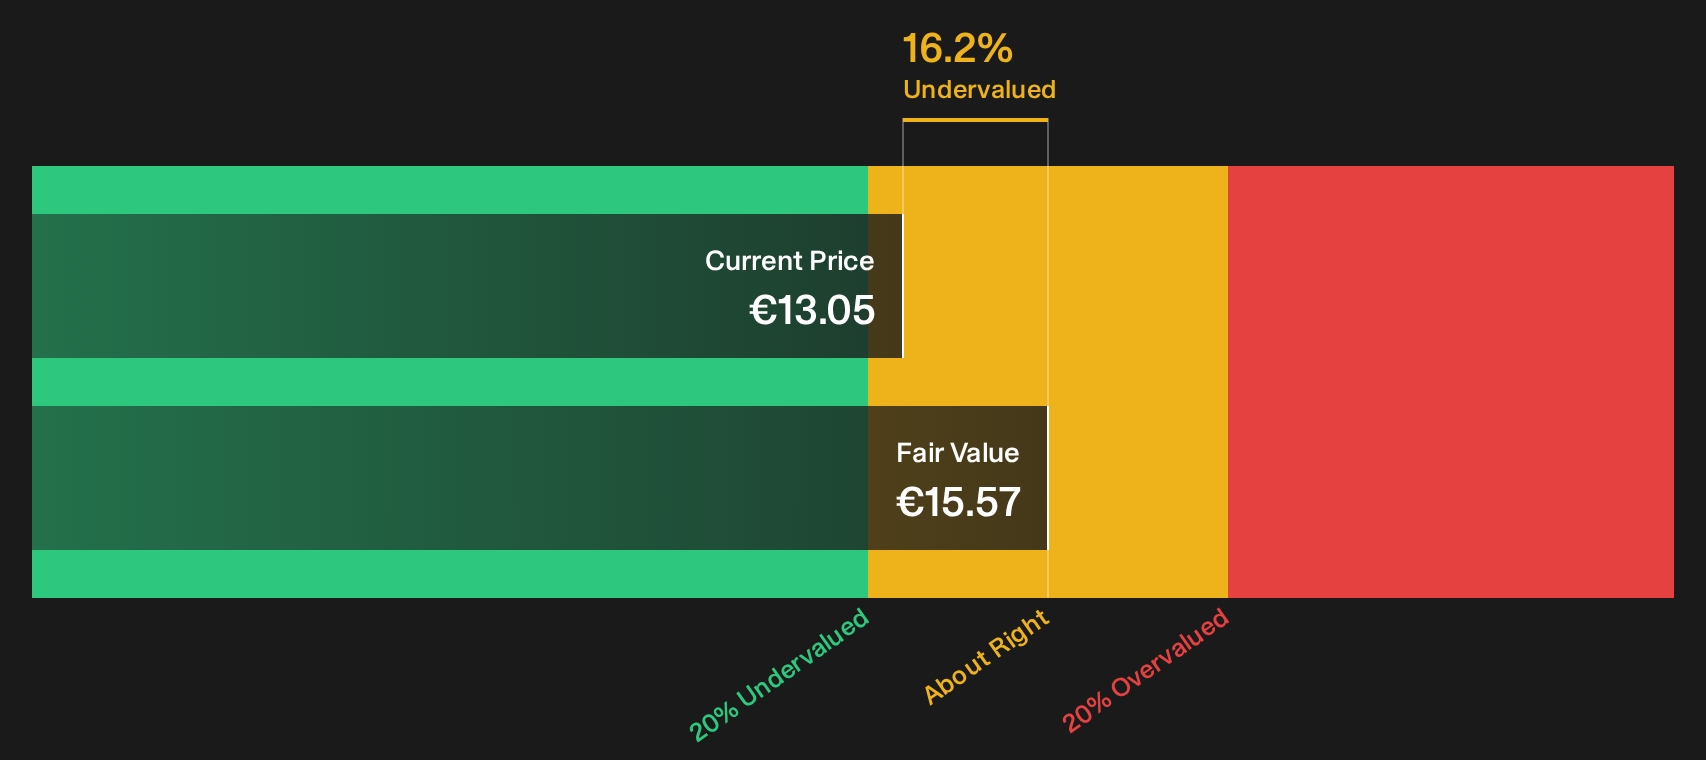
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alma Media Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
After weighing Alma Media Oyj's valuation signals and recent share pullback, the real question is how you interpret the balance between concern and optimism. Act while the facts are fresh and shape your own view by reviewing the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Alma Media Oyj?
If Alma Media Oyj has sharpened your appetite for opportunity, do not stop here. Widen your watchlist now so you are not playing catch up later.
- Target potential mispricing early by scanning a 182 high quality undervalued stocks that filters for quality businesses trading at a discount.
- Strengthen your income focus by reviewing a 219 dividend fortresses built around companies offering higher yields with supporting fundamentals.
- Lower portfolio stress by checking a 225 resilient stocks with low risk scores that highlights resilient stocks with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com