


Avista (AVA) has drawn fresh attention after filing a Bull Trout Monitoring Report with US energy regulators, outlining two September mortality incidents and the operational tweaks the utility made to reinforce its hydro project compliance.
For investors watching Avista, the regulatory filing lands after a mixed stretch in the market, with the share price at US$35.83, a 90 day share price return down 14.32% and a 1 year total shareholder return of 2.07%, supported by a 25.74% total shareholder return over three years. This suggests that longer term holders have still seen momentum build despite recent weakness.
Scan for other regulated utilities facing similar compliance and environmental pressures by reviewing the hand-picked 31 resilient stocks with low risk scores in your watchlist alongside Avista.
Avista looks like a solid regulated utility on the surface, even with the recent share price drop. The real question is whether that stability is already fully reflected in the US$35.83 tag or not.
Most Popular Narrative: 13% Undervalued
Avista's most followed narrative puts fair value at $41.33, above the recent $35.83 close. This frames today’s price against a long, regulated investment plan and a clearly defined capital spend through 2030.
The multiyear capital investment plan for Avista Utilities has been updated from approaching US$3b in 2025 to 2029 to US$3.4b in 2026 to 2030, with additional potential US$350m of incremental investment tied to large-load connections and regional transmission needs, which can increase regulated rate base and support earnings growth if executed within allowed returns.
See why 7 investors see Avista as 13% undervalued.
Result: Fair Value of $41.33 (UNDERVALUED)
Still, the bullish Avista story can unravel if wildfire costs climb faster than regulators allow for recovery, or if heavy capital spending forces equity issuance that dilutes future returns.
Find out about the key risks to this Avista narrative.
Another View: Avista Through A Cash Flow Lens
There is a catch in the Avista story. While the consensus narrative points to a fair value of $41.33, the SWS DCF model puts the future cash flow value at $35.21, slightly below the current $35.83 price and implying the stock is a touch overvalued on this yardstick.
The gap is small in dollar terms, yet it tells you something important. One framework says the current tag leaves upside if earnings and multiples track analyst assumptions. A straight cash flow read, on the other hand, suggests less room for error. Which lens do you trust more when the next wildfire season or rate case arrives?
To understand how that cash flow outcome is built and where your own assumptions might differ, Look into how the SWS DCF model arrives at its fair value.
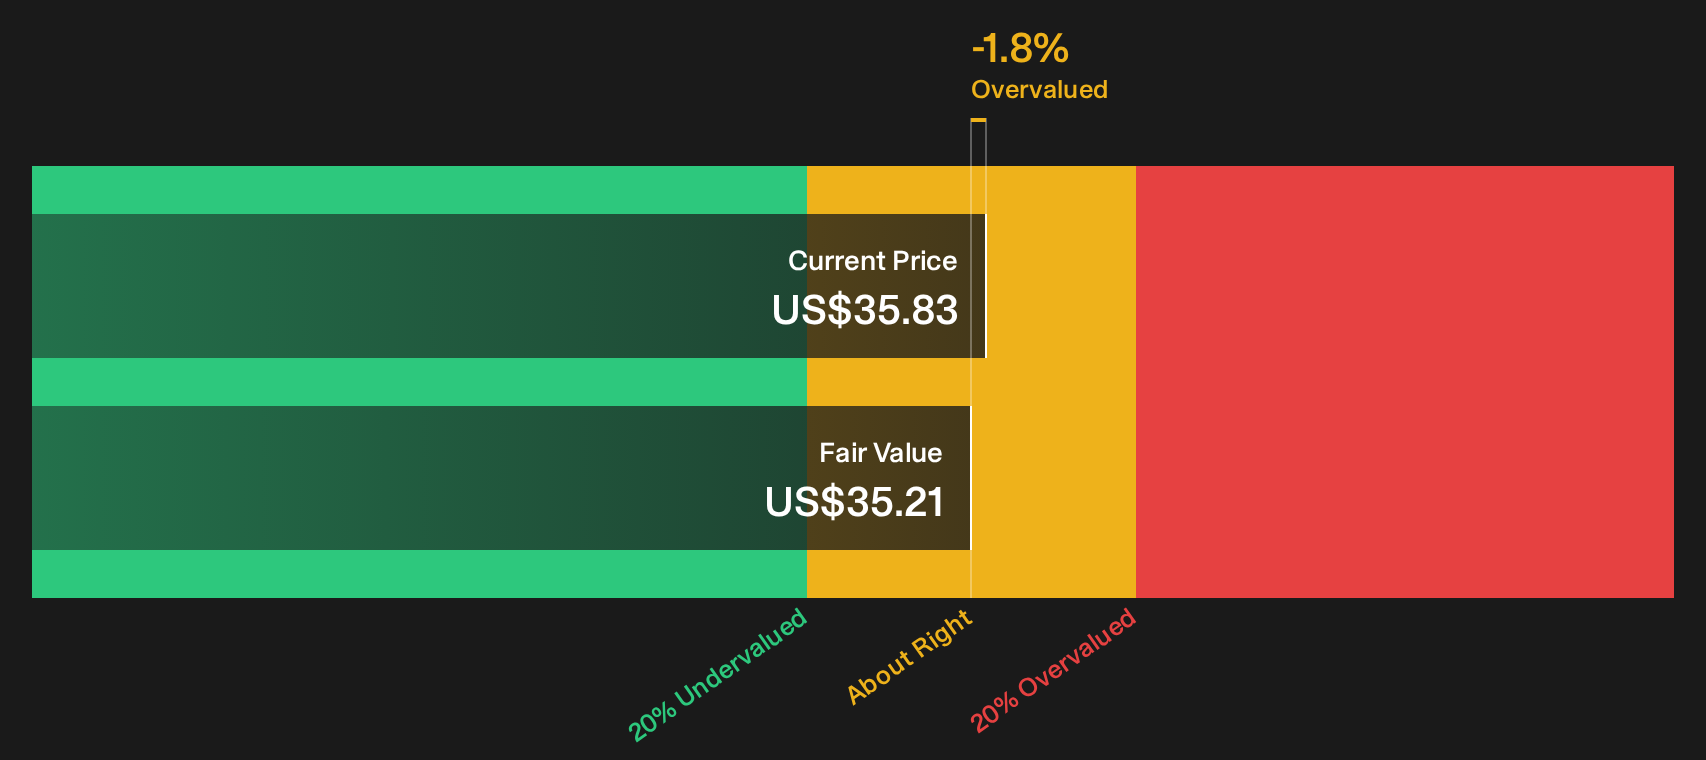
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avista for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Avista so far. If you want to move quickly and build your own stance using the underlying data, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avista?
If Avista has you thinking harder about regulated utilities and risk, broaden your watchlist with a few focused screens that surface different types of opportunities.
- Target stronger balance sheets by scanning companies that show up in the list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps by reviewing the 29 high quality undervalued stocks before the rest of the market catches up.
- Prioritise reliable cash returns by checking out the 8 dividend fortresses while yields remain compelling.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com