


Arthur J. Gallagher & Co. (AJG), headquartered in Rolling Meadows, Illinois, provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services. Valued at $60 billion by market cap, the company's principal activity is the negotiation and placement of insurance for its clients. Gallagher also specializes in furnishing risk management services. The insurance giant is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Thursday, Oct. 29.
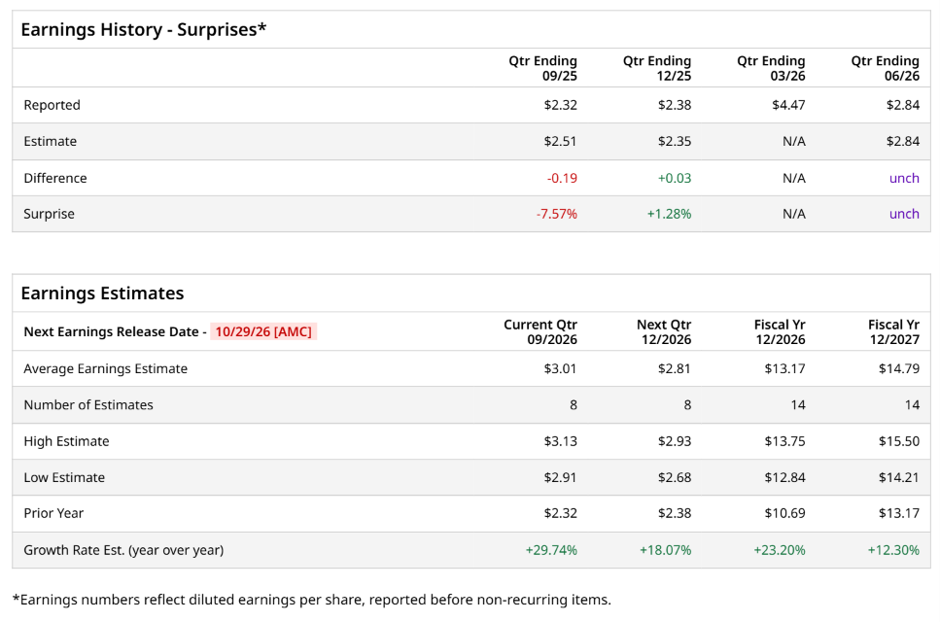
Ahead of the event, analysts expect Arthur J. Gallagher to report a profit of $3.01 per share on a diluted basis, up 29.7% from $2.32 per share in the year-ago quarter. The company beat or matched the consensus estimates in two of the last three quarters while missing the forecast on another occasion.
For the full year, analysts expect Arthur J. Gallagher to report EPS of $13.17, up 23.2% from $10.69 in fiscal 2025. Its EPS is expected to rise 12.3% year over year to $14.79 in fiscal 2027.
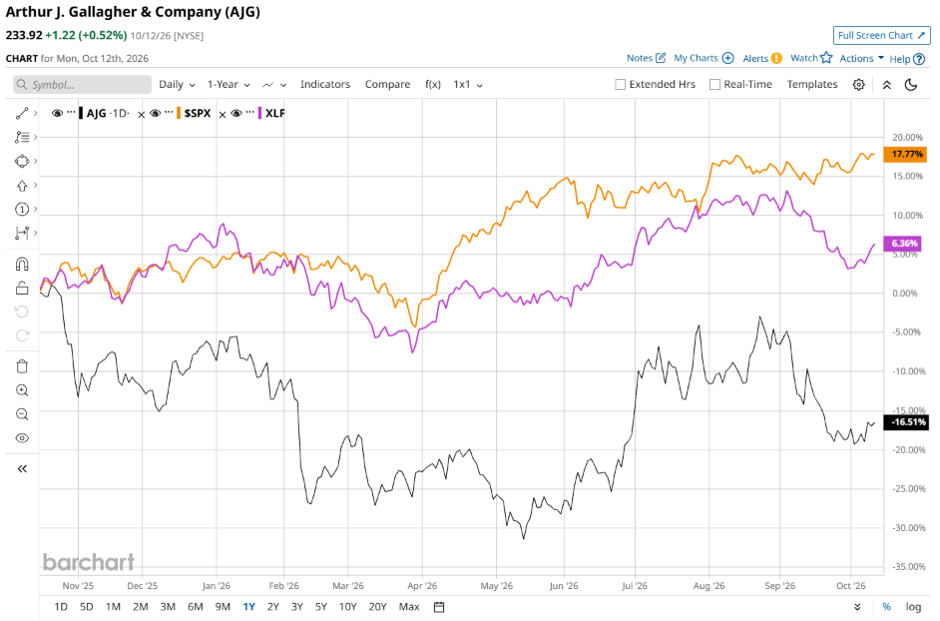
AJG stock has notably underperformed the S&P 500 Index’s ($SPX) 19.2% gains over the past 52 weeks, with shares down 22.5% during this period. Similarly, it underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 5.1% returns over the same time frame.
AJG's recent market lag stems from a classic multiple-contraction setup, where investors are penalizing the stock as slowing organic growth and softer insurance rate hikes catch up to its premium valuation. At the same time, sticky wage inflation and climbing operational overheads are squeezing operating margins. Compounding these cyclical pressures is a growing existential anxiety over how automation and artificial intelligence might eventually reshape traditional, relationship-driven brokerage frameworks. To mask these deceleration trends, management has leaned hard into bolt-on M&A activity, raising the stakes for seamless integration at a time when capital efficiency is under intense scrutiny.
Analysts’ consensus opinion on AJG stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 25 analysts covering the stock, 17 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and seven give a “Hold.” AJG’s average analyst price target is $284.55, indicating a potential upside of 21.6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.