


The IMF has warned that high government borrowing and rising bond yields could trigger sharp moves in global debt markets. That kind of stress can punish companies that rely on cheap credit and short term thinking. Founder led British businesses often run with tighter balance sheets and a longer time horizon, which can appeal when conditions turn. This article highlights three such stocks from the screener worth watching now.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is deeply invested in the outcome. However, if you want the strongest names, these 8 top founder-led companies are the top of the list.
Fevertree Drinks (AIM:FEVR)
Fevertree Drinks builds its premium Fever Tree mixers around the founders’ original vision, which fits the founder led theme where leadership identity and product are closely tied.
Fevertree Drinks develops and sells Fever Tree branded mixer and soft drinks across the UK, US, Europe and other international markets, with a market value of about £995 million.
Fevertree Drinks offers a clear founder story, yet the real test for investors is how one pressure on future profitability ultimately resolves.
"Although Fevertree Drinks is broadening its range beyond tonic and reports that the wider portfolio now represents nearly half of group sales, a further shift in consumer taste away from mixers could leave the company with high exposure to flavours that fail to scale."
The tension between premium ambition and that single pressure on margins and cash returns may influence how the Fevertree Drinks story develops.
That unresolved pressure on profitability is exactly what makes the full narrative for Fevertree Drinks worth reading, as it weighs margin strain against brand strength and any overlooked upside.

Computacenter (LSE:CCC)
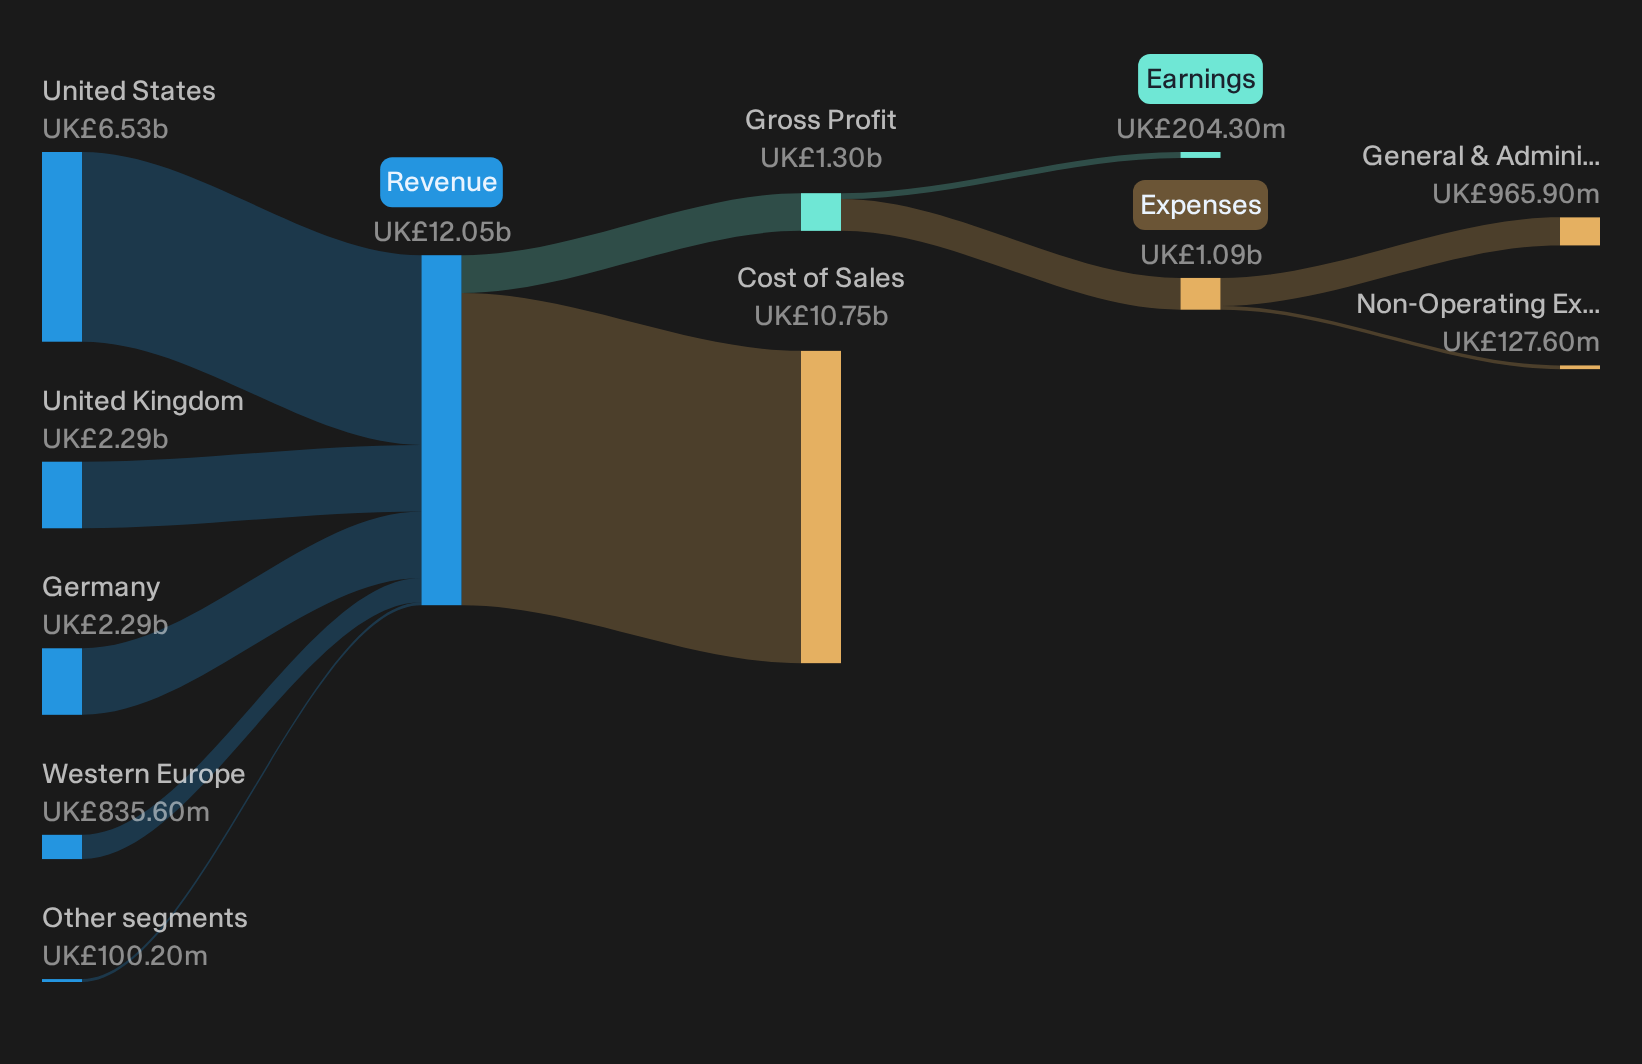
Computacenter runs a global IT services and outsourcing operation, supplying and managing technology for corporate and public sector clients, with all £12.1b of revenue coming from Computer Services and a market value of about £5.9b.
Computacenter fits a founder-led mindset through long-tenured leadership that commits to multi year managed services, from workplace support to secure networking. This gives investors exposure to recurring contracts shaped by executives who think in decades rather than quarters. However, outcomes still depend on how pressure on funding costs and margins ultimately plays out.
If you want to see how that trade off between contract visibility and funding costs could evolve, start with the analysis report for Computacenter for potential signals hiding in plain sight.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings gives you exposure to a listed asset manager that specialises in backing founder run businesses with growth capital, buyouts and governance support, generating £114.8 million from Real Assets, £50.1 million from Private Equity, and carrying a market value of about £486.6 million.
Foresight Group Holdings sits at the heart of this founder led theme because its whole business revolves around backing entrepreneurs directly, then using its own balance sheet and governance playbook to scale them up over time.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
One key test for Foresight Group Holdings is how an untested pressure on future fee resilience eventually feeds through to both earnings and payouts.
That fee resilience question is exactly what the full narrative for Foresight Group Holdings unpacks. It shows where compounding could accelerate or stall as recycling capital and distributions pull in different directions.

Seeking Alternatives Before The Crowd Moves
Fresh opportunities do not wait around. Some stocks build quiet momentum, others are already flying while attention lags. Scan under the radar for now, then act now.
- Spot income workhorses early and review 1 dividend fortresses to help keep your portfolio cash flow ticking even when prices swing.
- Track decisive turns in quality and check the 7 high quality undervalued stocks before potential breakouts are fully caught in the spotlight.
- Search for potential infrastructure leaders by scanning 92 AI infrastructure stocks before additional capital flows in and changes the risk-reward balance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com