


MedinCell shares have moved sharply in recent years, which puts a fresh spotlight on a simple question for investors who care about fundamentals. Does the current price around €28.80 still make sense when you line it up against the company’s sales base?
- Over the past 3 years, MedinCell has delivered a very large share price gain of about 3.5x, which raises the stakes on whether that move is supported by what the business is generating in revenue.
- FDA approval for its Olanzapine long acting injectable and the planned U.S. launch with Teva can shape future sales expectations and may support different views on what a reasonable price to sales multiple looks like today.
- The analysts covering MedinCell have run their own numbers. See what analysts think MedinCell's shares could be worth.
The issue now is whether MedinCell’s current market value is justified by its sales when you compare it with the Fair Ratio benchmark.
If you want to stress test this same price to sales question beyond MedinCell, it helps to compare it with companies from a curated list of 182 high quality undervalued stocks.
Does MedinCell Look Pricey on Sales?
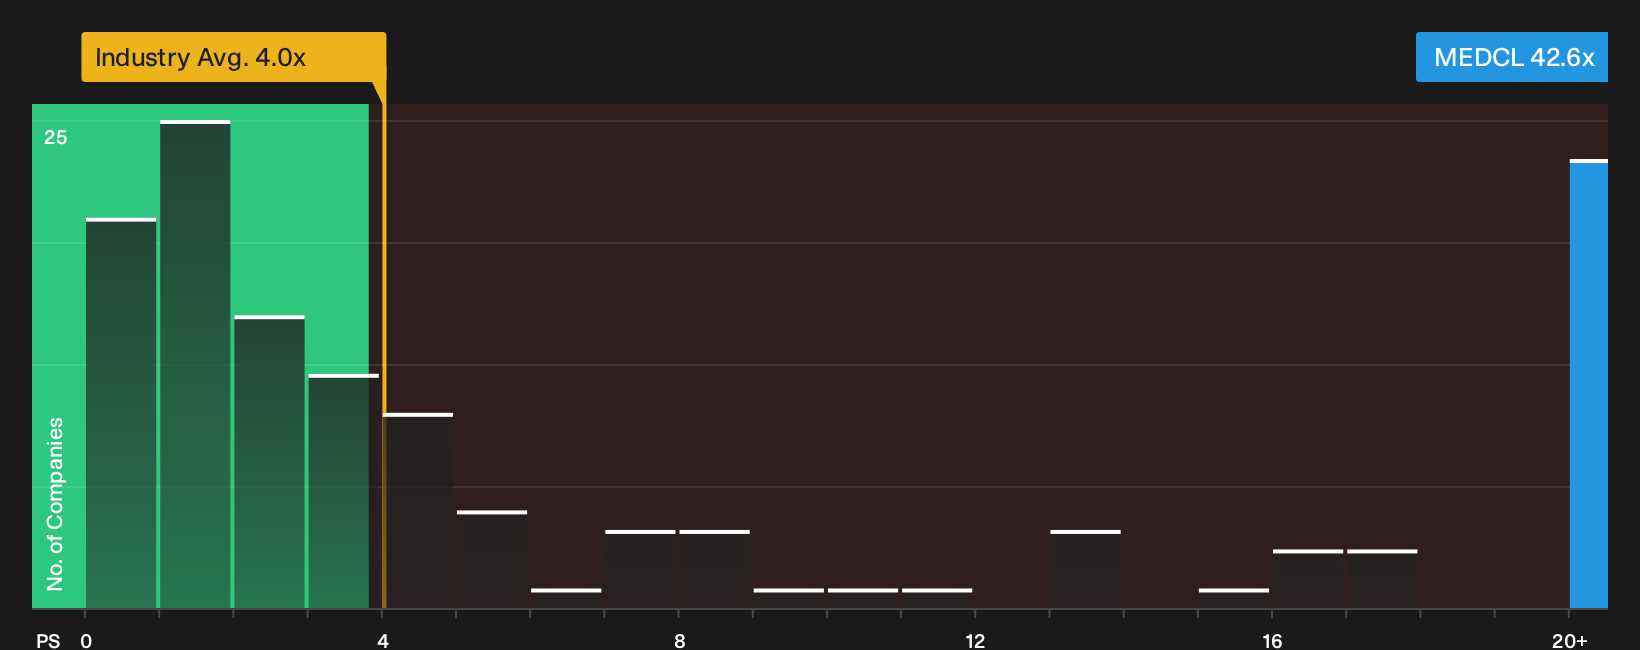
The P/S ratio is a natural lens for MedinCell because revenue is the cleanest anchor for a business that is still loss making on earnings and free cash flow. At about 42.6x sales, the stock trades far above the Pharmaceuticals industry average of roughly 2.7x and well ahead of the peer group on about 1.7x. That gap means each euro of MedinCell’s revenue is currently priced at a much richer level than many sector rivals.
The Fair Ratio model, which adjusts the P/S benchmark for MedinCell’s margins, size, risk profile and projected cash flows, flags the current 42.6x as overvalued and as an extreme reading rather than a tight estimate of where the shares “should” trade. The framework is heavily discounting the company’s recent losses and the quality and timing of future revenue, so the implied fair multiple is best read as a warning light rather than a precise target. Despite the recent FDA approval and upcoming U.S. launch of WELTRUZA, the P/S multiple still prices MedinCell at a steep premium that investors need to weigh against execution risk on those new products. Explore the numbers behind MedinCell's P/S valuation.
The MedinCell Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for MedinCell leaves off by spelling out the specific paths for growth, profitability and earnings that would need to play out for the stock to look materially cheaper or more expensive than it does today. Each narrative ties its number to a clear view on how MedinCell's expansion, margin profile and risk picture might evolve, giving you something concrete to revisit as new information comes through.
One of the top community narratives on MedinCell: 18% undervalued
"MedinCell's long acting injectable platform, supported by extended patent protection and real world value data, is positioned to support premium pricing and broader uptake..."
Discover why this Narrative puts MedinCell at 18% undervalued.
Before you focus only on MedinCell's valuation, there is one more angle to check
MedinCell's pricing story is only part of the picture, because internal checks have also raised specific areas of concern that could matter just as much for your decision. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com