


Recall event puts Flowers Foods back in focus
Flowers Foods (FLO) has issued a recall of specific Nature's Own Hawaiian Bread products after finding undeclared milk, a labeling issue that raises both food safety questions and potential reputational risk for the baker.
Investors have seen short term momentum build in Flowers Foods, with a 1 day share price return of 3.96% and 7 day share price return of 7.86%, even as the 90 day share price return has fallen 27.14% and the 5 year total shareholder return is down 68.79%. This frames the recall against a backdrop of long running pressure on the stock and shifting views on its risk profile.
Scan how investors are pricing product recall risk and food safety execution across the sector by comparing Flowers Foods with our curated list of 31 resilient stocks with low risk scores.
Flowers Foods still runs a large, established bakery business. After a sharp move off deeply weaker multi year returns, the real question now is whether the current price fairly reflects that reality.
Most Popular Narrative: 24% Undervalued
Against the recall news flow, the most followed narrative still anchors Flowers Foods to a fair value of $7.90 versus a last close of $6.04, which frames the debate around whether the portfolio reset and mix shift can outweigh weaker long term share price performance.
Analysts expect Flowers Foods to keep facing pressure in traditional loaf bread while leaning on Better For You bread and snacks, brand renovation and cost control to support the business over time.
The main thing that has to go right is Flowers Foods successfully shifting its portfolio and marketing toward Better For You and snacking platforms while managing promotions, costs and leverage so that earnings pressure does not outweigh mix and efficiency gains.
See why 31 investors see Flowers Foods as 24% undervalued.
Result: Fair Value of $7.90 (UNDERVALUED)
Still, the Flowers Foods story can break if weakness in traditional loaf bread continues to drag on volumes or if oil-linked packaging and diesel costs increase more than expected.
Find out about the key risks to this Flowers Foods narrative.
Another View: Flowers Foods looks expensive on earnings
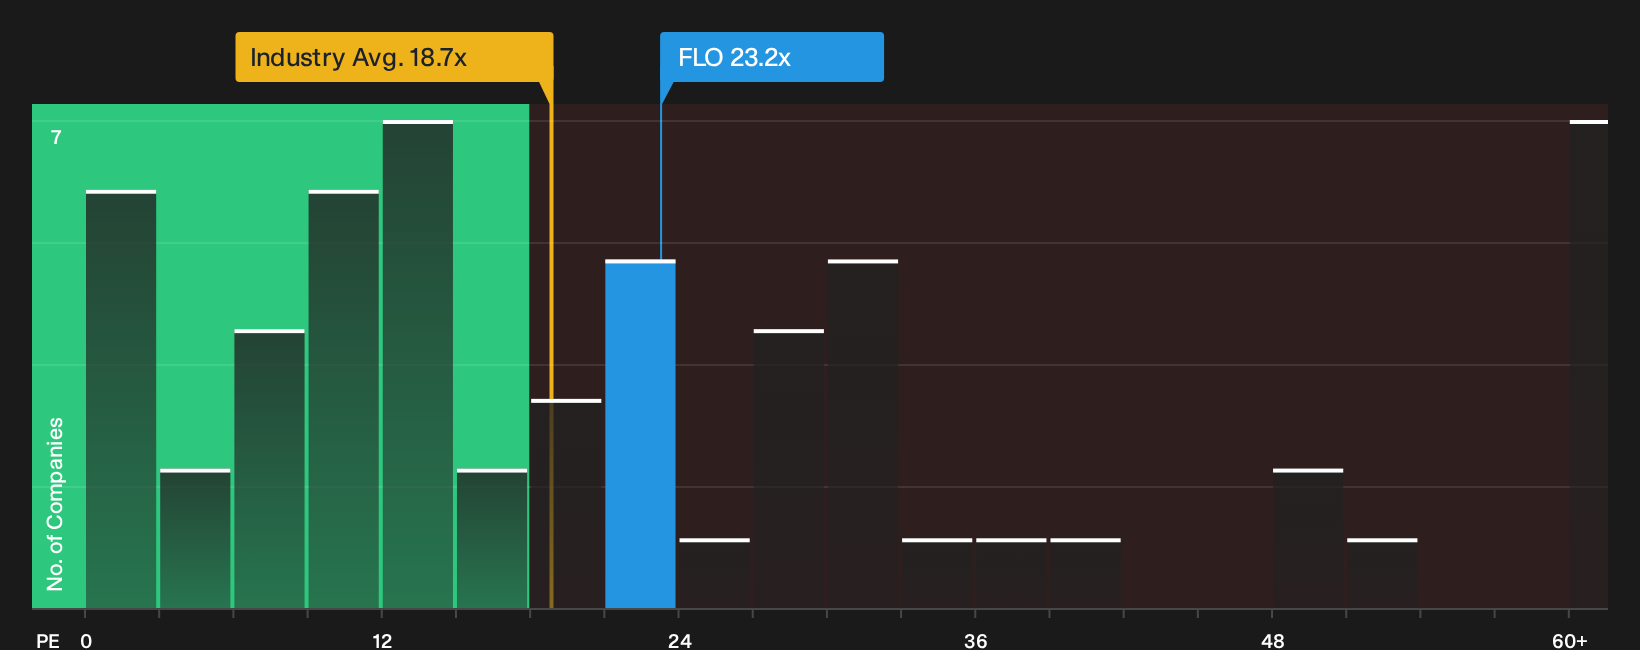
While the SWS DCF model points to a gap between price and fair value, the simple P/E check tells a tighter story. Flowers Foods trades on 23.2x earnings compared with 18.7x for the US Food group and a fair ratio of 17x, which leans toward valuation risk rather than clear upside. So which signal do you trust more right now?
For a closer look at how that earnings based valuation stacks up against peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can be confusing, so use this as a prompt to move quickly, review the underlying numbers and decide where you land on Flowers Foods. To weigh the downside flags against the potential upside, start with the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Flowers Foods?
If you only focus on Flowers Foods, you risk missing other attractive setups that could balance your portfolio and sharpen your overall returns.
- Target stronger cash returns by scanning a curated set of income ideas through the 8 dividend fortresses.
- Hunt for potential value opportunities before the crowd notices by working through the 20 high quality undiscovered gems.
- Prioritize resilience and capital protection by screening defensively tilted opportunities via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com