


Q2 guidance shift puts Cheniere’s recent run in context
Cheniere Energy (LNG) raised its full year 2026 outlook after reporting Q2 adjusted EBITDA of about US$1.8b and distributable cash flow near US$1.2b, tied to higher LNG production and exports.
The update arrives with the stock up about 1.5% over the past month and roughly 6.6% over the past 3 months, giving investors fresh numbers to weigh against recent expansion commitments.
At a share price of US$282.49, Cheniere Energy has paired a strong year to date share price return of 42.82% with a 1 year total shareholder return of 25.67%. This suggests momentum has cooled lately, even as Q2 guidance and expansion progress keep the longer term story in focus.
Scan how Cheniere Energy compares with other large energy plays that show resilient fundamentals and pricing strength by reviewing our hand picked list of solid balance sheet and fundamentals (25 results).
Cheniere Energy now combines a large US$58.3b market value with strong LNG infrastructure and fresh guidance. The real tension is simple: Are you paying a fair price for that setup today?
Most Popular Narrative: 9% Undervalued
On the most followed view, Cheniere Energy screens as modestly undervalued, with a fair value of about $309.95 versus the recent $282.49 close. That gap reflects a story built around long term LNG contracts, incremental capacity and efforts to smooth out reported earnings volatility.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is expected to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
See why 68 investors see Cheniere Energy as 9% undervalued.
Result: Fair Value of $309.95 (UNDERVALUED)
Still, the narrative around Cheniere Energy can be knocked off course if LNG linked derivatives keep swinging reported earnings or if the US$370m tax credit probe escalates.
Find out about the key risks to this Cheniere Energy narrative.
Another View: Cheniere Energy Looks Full On Earnings Multiples
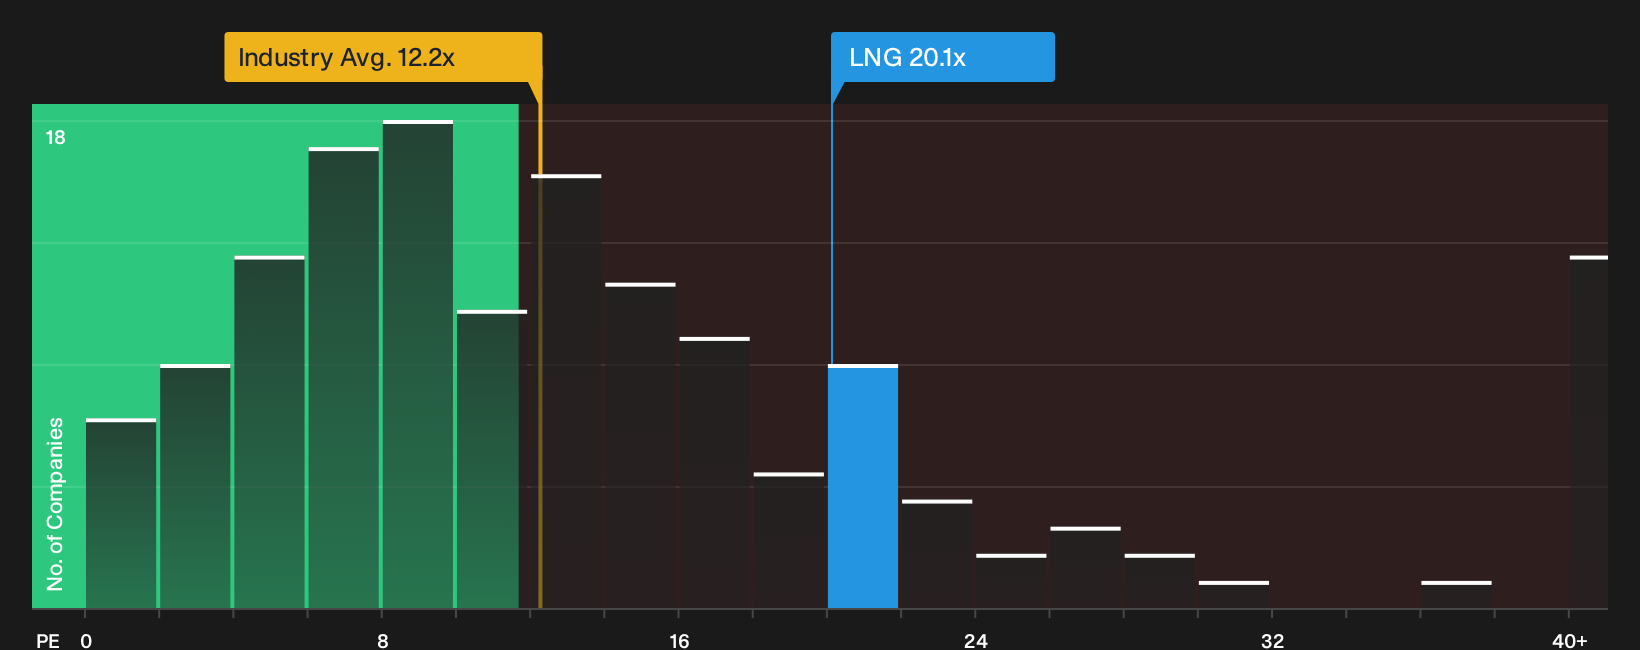
The narrative around Cheniere Energy as 9% undervalued meets a very different message from plain earnings ratios. At a P/E of about 20.1x, the stock trades above both its estimated fair ratio of 19.8x and peers at 18.8x, and well above the wider US Oil and Gas group at 12.2x. That kind of premium can make sense if you are comfortable paying up for contracted LNG cash flows, but it also raises a simple question: How much margin of safety do you really have if sentiment on the sector cools?
To see how that earnings multiple stacks up against detailed assumptions and peer checks, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Cheniere Energy is split, with clear concerns alongside clear bright spots. Move quickly and review the underlying data yourself while the details are still fresh. To weigh both sides of that debate in one place, start with our breakdown of 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Cheniere Energy?
If you stop at Cheniere Energy, you risk missing other opportunities that could better match your goals, risk tolerance and timeframe across the wider market.
- Target reliable cash generators by reviewing our hand picked 29 high quality undervalued stocks that combine solid fundamentals with pricing that may still leave room for upside.
- Strengthen your income backbone through 8 dividend fortresses that focus on higher yielding payers with an emphasis on durability and balance sheet support.
- Build a sturdier core portfolio using our curated 31 resilient stocks with low risk scores that highlights businesses with more resilient risk profiles and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com