


- Onto Innovation recently reported record revenue, gross margin, operating margin and earnings per share that all surpassed its own guidance. The company also highlighted rapid growth in advanced nodes and inspection tools, and a higher outlook for second half revenue growth of at least 25% over the first half.
- The business also received a Best Partner Award from SK hynix for its Dragonfly G5 high bandwidth memory inspection system, underscoring how its measurement technology is embedded in critical AI infrastructure build outs at major chipmakers.
- We will now explore how Onto Innovation's guidance raise, anchored in AI driven HBM demand, could reshape the existing investment narrative.
Scan beyond Onto Innovation and line up other AI infrastructure beneficiaries with the hand picked 92 AI infrastructure stocks that could also be riding high bandwidth memory demand.
Onto Innovation Investment Narrative Recap
To own Onto Innovation, you need to believe the AI packaging and HBM driven demand can keep the tool pipeline busy enough for its record revenue, margins and EPS to be repeatable rather than a one off spike. The raised second half outlook and guidance for Q4 above Q3 put execution in advanced packaging and inspection at the centre of the near term story.
The biggest swing factor right now sits in how smoothly those large HBM and OSAT orders convert into shipments and margin mix, especially with power semiconductor weakness and the sizeable Rigaku commitment already flagged as pressure points. Legal investigations around fiduciary duty add background headline risk, but based on current disclosures this looks secondary to operational delivery.
The SK hynix Best Partner Award is the clearest signal tying this earnings beat to a real world production footprint. It indicates Onto Innovation is not just talking about AI and HBM; its Dragonfly G5 system is already wired into a key memory supplier’s roadmap, where any yield slip on these expensive devices quickly becomes material.
For catalysts, that award matters because it supports the multi year Dragonfly order story, including more than US$240 million tied to an HBM customer and over US$200 million from an OSAT. The more deeply tools are embedded in customer roadmaps and production flows, the more the raised outlook for roughly 80% advanced packaging growth in 2026, higher gross margin guidance and extended factory benefits depends on execution rather than pure aspiration.
What The Analyst Scenario Implies For Onto Innovation
Onto Innovation's narrative projects US$2.4b revenue and US$832.7m earnings by 2029. This assumes 29.5% yearly revenue growth and an earnings increase of about US$700m from US$132.6m today, in order to reach that 2029 consensus level.
Uncover why Onto Innovation's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
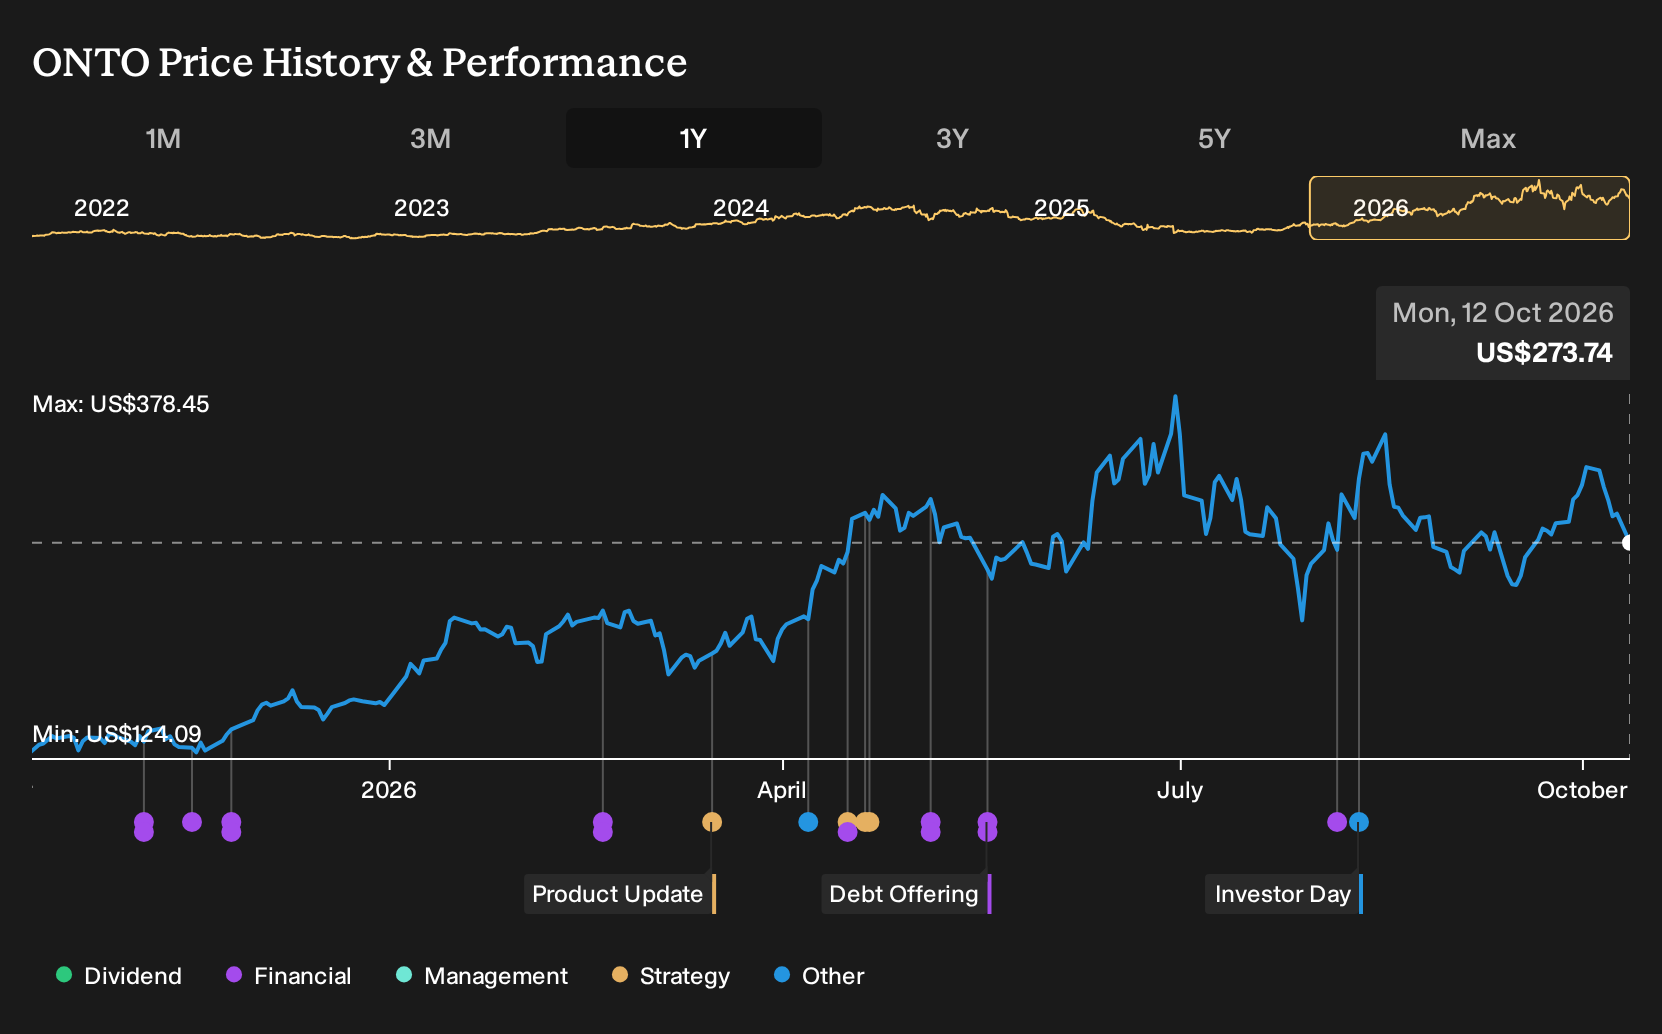
Exploring Other Perspectives
One alternate view hinges on silicon photonics rather than HBM. The most optimistic Onto Innovation analysts were already pencilling in revenue of about US$2.8b and earnings of US$845.9m by 2029. That is a far more upbeat path, and today’s news could either push those projections higher or prompt you to reassess them entirely.
Explore 4 other Onto Innovation fair value estimates, including one that suggests as much as 42% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Onto Innovation research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Onto Innovation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Onto Innovation's overall financial health at a glance.
Looking For More Ideas Beyond Onto Innovation?
If the Onto Innovation story has sharpened your interest in AI infrastructure and semiconductor tools, it can help to widen the lens and compare it with other potential opportunities using the Simply Wall St Screener.
- Target strong balance sheets and robust fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that can help you focus on financially resilient businesses.
- Hunt for quality at a price you find reasonable by reviewing a 29 high quality undervalued stocks that blend solid cash flows with what may be attractive valuations.
- Prioritise stability over drama by checking a 31 resilient stocks with low risk scores that score well on risk metrics and may help anchor a more defensive part of your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com