


Bloom Energy (BE) has just moved into a new phase. Record revenue, first-time GAAP profitability, higher 2026 guidance, and stronger cash flow are all being driven by demand from AI-focused data centers.
Investors have been reminded how volatile Bloom Energy can be, with the share price falling 6.5% in the last day and 8.5% over the past week even as the year-to-date share price return sits at 165.8% and the 5-year total shareholder return is above 11x. Recent pullbacks have arrived alongside short-seller commentary, profit taking and an earnings date announcement. Yet the 3-year total shareholder return of more than 20x signals that the market has repeatedly re-rated the stock as the AI data center story has gained traction.
Pace your exposure to the AI power story by scanning a hand picked group of infrastructure players through the 92 AI infrastructure stocks.Bloom Energy now trades at a double discount, around 7% below the average analyst target and roughly 34% below one intrinsic value estimate after a sharp pullback. Is that caution priced for real risk or driven by fear of the chart?
Most Popular Narrative: 32% Undervalued
The most followed Bloom Energy valuation story points to a fair value of about $386 per share, well above the last close at $262.28. This puts the recent pullback into sharper context for anyone trying to size up the risk and reward trade off.
The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth, international, other market segments, even personal or community power (where they started) are largely untapped.
The main constraint on their opportunity is plain and simple ignorance.
See why 42 investors see Bloom Energy as 32% undervalued.
Result: Fair Value of $386.10 (UNDERVALUED)
Still, Bloom Energy depends heavily on AI data center demand and favorable policy for on site power, and either trend cooling could challenge this optimism.
Find out about the key risks to this Bloom Energy narrative.
Another View On Bloom Energy’s Valuation
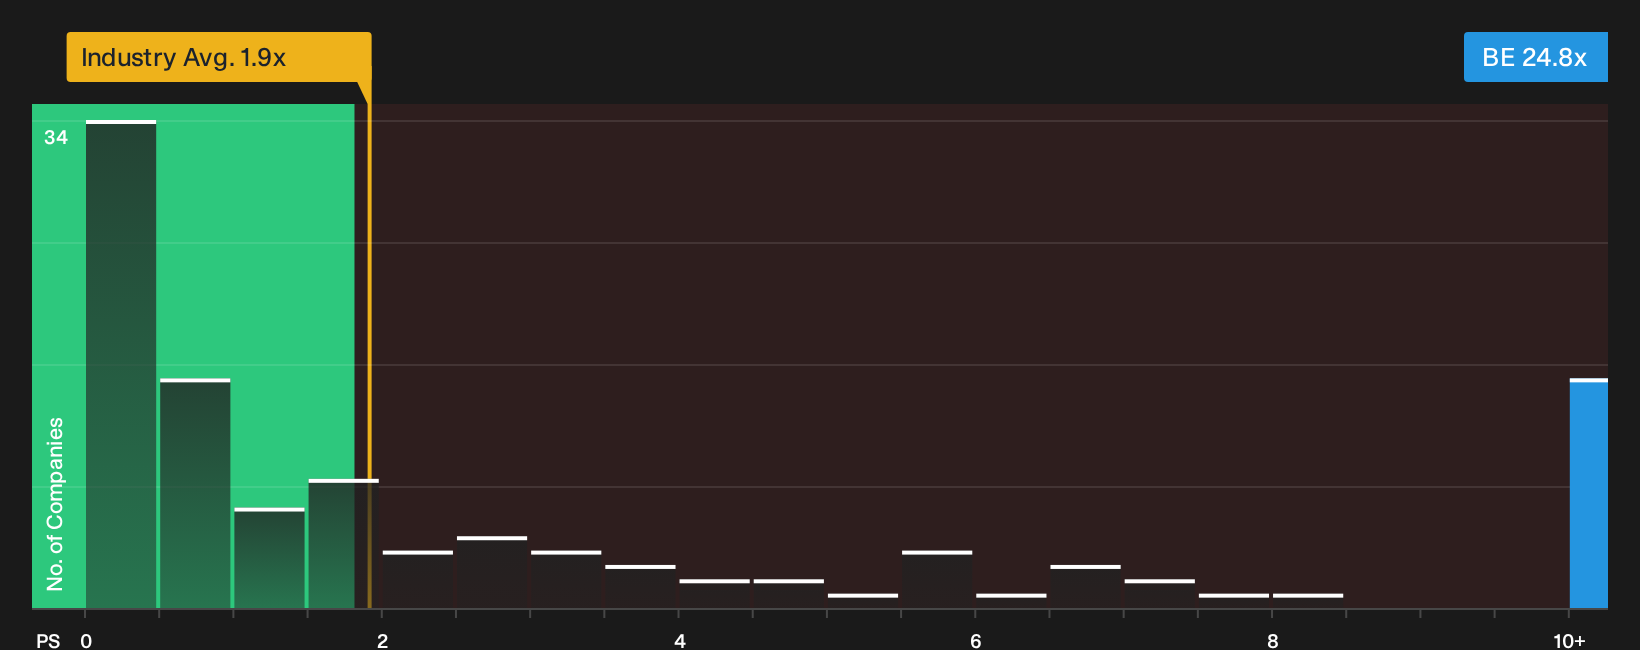
The story looks very different once the focus shifts to simple sales multiples. Bloom Energy trades on a P/S of 24.8x. The fair ratio sits at 15.3x, the US Electrical industry averages 1.9x, and close peers are around 5.9x. That gap points to a lot of expectation already baked into the price. Is this a premium you are comfortable paying for the growth narrative?
For a closer look at how those revenue multiples stack up against what the numbers suggest, take a moment to See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals in Bloom Energy's story can be a strength if you use them well. Move quickly, review the underlying data, and weigh both the 3 key rewards and 4 important warning signs.
Looking for more Bloom Energy sized ideas?
You have seen how quickly a story like Bloom Energy can evolve. Do not stop here. Use the Simply Wall Street Screener to explore another set of opportunities before they move out of reach.
- Target quality at a discount by reviewing a carefully filtered 29 high quality undervalued stocks that pairs solid fundamentals with attractive pricing.
- Prioritise resilience by scanning a 31 resilient stocks with low risk scores that focuses on businesses with stronger risk profiles than the wider market.
- Identify potential standouts early with a 20 high quality undiscovered gems that surfaces quieter companies with stronger numbers backing them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com