


When the IMF starts talking about the world economy hitting its “limits of resilience,” cash stops looking boring and starts looking like optionality. Investors who usually focus on long-term growth stories suddenly care a lot more about liquidity, short-duration instruments and who actually runs the pipes behind institutional cash. This article walks through 3 stocks that sit close to those cash flows, and how the latest AI and inflation shocks might matter for each one.
The stocks covered below are just a small sample of what shows up when you look for listed cash engines, and the full screen surfaced 22 more companies with equally compelling narratives that are not covered in this article. If you want to identify which short-duration cash and liquidity providers best fit your own playbook, head straight to the Global Short-Duration Cash & Liquidity Providers screener.
Turkiye Garanti Bankasi (IBSE:GARAN)
Overview: Turkiye Garanti Bankasi is a large Turkish bank that takes deposits and provides loans, payments, digital banking and cash management services for individuals and businesses.
Operations: Turkiye Garanti Bankasi generates TRY 233.7b from Retail Banking, TRY 204.3b from Corporate Banking and TRY 55.9b from Other activities, with Investment Banking reporting TRY 110.4b lower revenue.
Market Cap: TRY 545.2b
Turkiye Garanti Bankasi matters for this cash and liquidity screen because it controls a deep deposit pool and runs everyday payment rails that can absorb higher cash balances when investors and corporates step back from riskier assets.
“The ongoing focus on a TL-heavy customer deposit base, with customer deposits funding around 66% of assets and a high share of free funds and demand balances, is expected to keep funding costs relatively efficient and support net interest margins.”
The real swing factor is how one pressure on its higher yielding retail book ultimately feeds through to margins if conditions stay tight.
That margin pressure is exactly why the full narrative for Turkiye Garanti Bankasi explores how Turkiye Garanti Bankasi could balance funding costs, fee income and deposit mix as conditions shift.

Yapi ve Kredi Bankasi (IBSE:YKBNK)
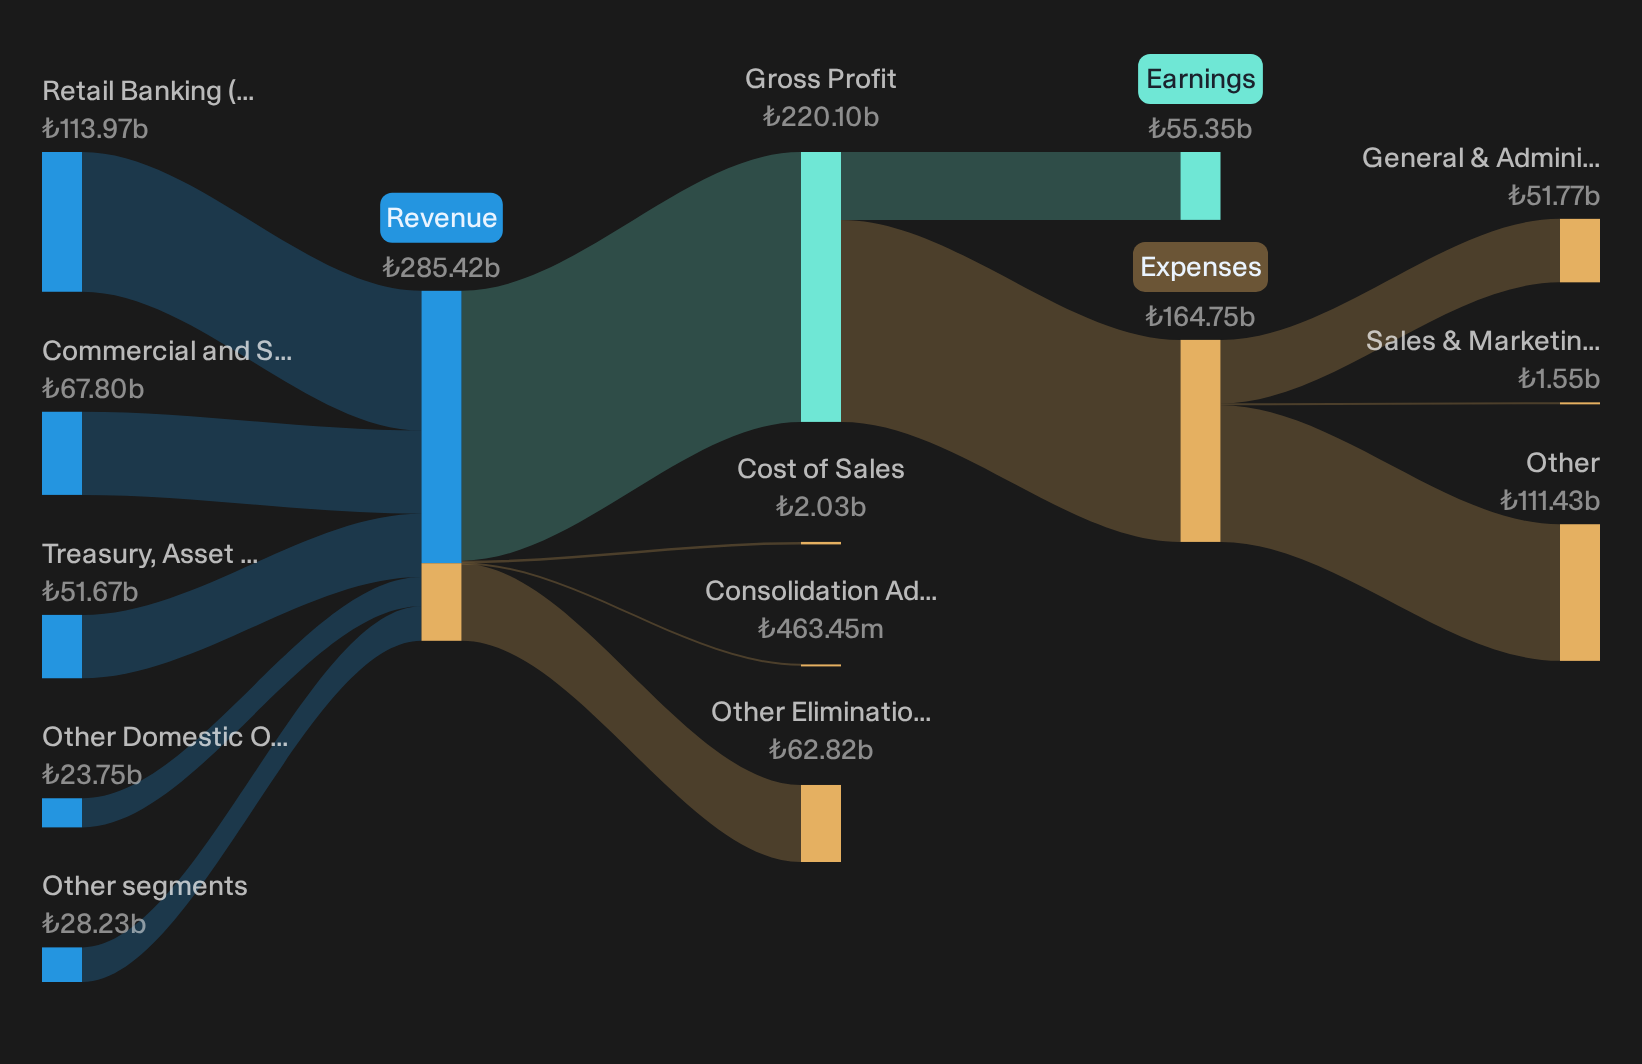
Overview: Yapi ve Kredi Bankasi is a Turkish-based universal bank that collects deposits and provides lending, payments and wealth services for individuals, SMEs and large corporates, giving investors direct exposure to cash management and short duration funding flows.
Operations: Yapi ve Kredi Bankasi generates TRY 114.0b from Retail Banking, TRY 67.8b from Commercial and SME Banking, TRY 21.1b from Corporate Banking and TRY 51.7b from Treasury, Asset Liability Management and Other activities, with TRY 23.8b from Other Domestic Operations and TRY 7.1b from Other Foreign Operations.
Market Cap: TRY 301.6b
Yapi ve Kredi Bankasi matters in this cash focused screen because it turns a deposit heavy, short term funding model into fee and interest income across retail, SME and corporate clients, which becomes more relevant when investors prize liquidity over long duration bets.
"The bank’s large share of low cost demand and small ticket deposits, including around 46% of total deposits in non interest bearing demand accounts, continues to provide a funding advantage that can support net interest margin and earnings in a high rate setting."
What really tests that advantage is how one unresolved credit cost pressure interacts with those cheap deposits when risk aversion spikes again.
When that pressure hits, full narrative for Yapi ve Kredi Bankasi shows how Yapi ve Kredi Bankasi’s cheap funding base could either absorb the shock or accelerate earnings volatility.
Bandhan Bank (NSEI:BANDHANBNK)
Overview: Bandhan Bank is an Indian full service bank that collects deposits and provides loans and transaction services to households and businesses.
Operations: Bandhan Bank generates about ₹219.7b from Retail Banking, ₹29.3b from Corporate and Wholesale Banking and ₹27.9b from Treasury activities.
Market Cap: ₹253.8b
Bandhan Bank matters for this short duration cash theme because its deposit and transaction franchises give it a direct line into customers who park money in safer, liquid accounts when global risks feel higher.
"Continued strong growth in the bank's non-EEB segments, especially secured retail, housing, and wholesale banking loans (growing 27%+ YoY), and further asset mix diversification are likely to reduce concentration risk and credit costs, leading to more stable earnings and improved net interest margins."
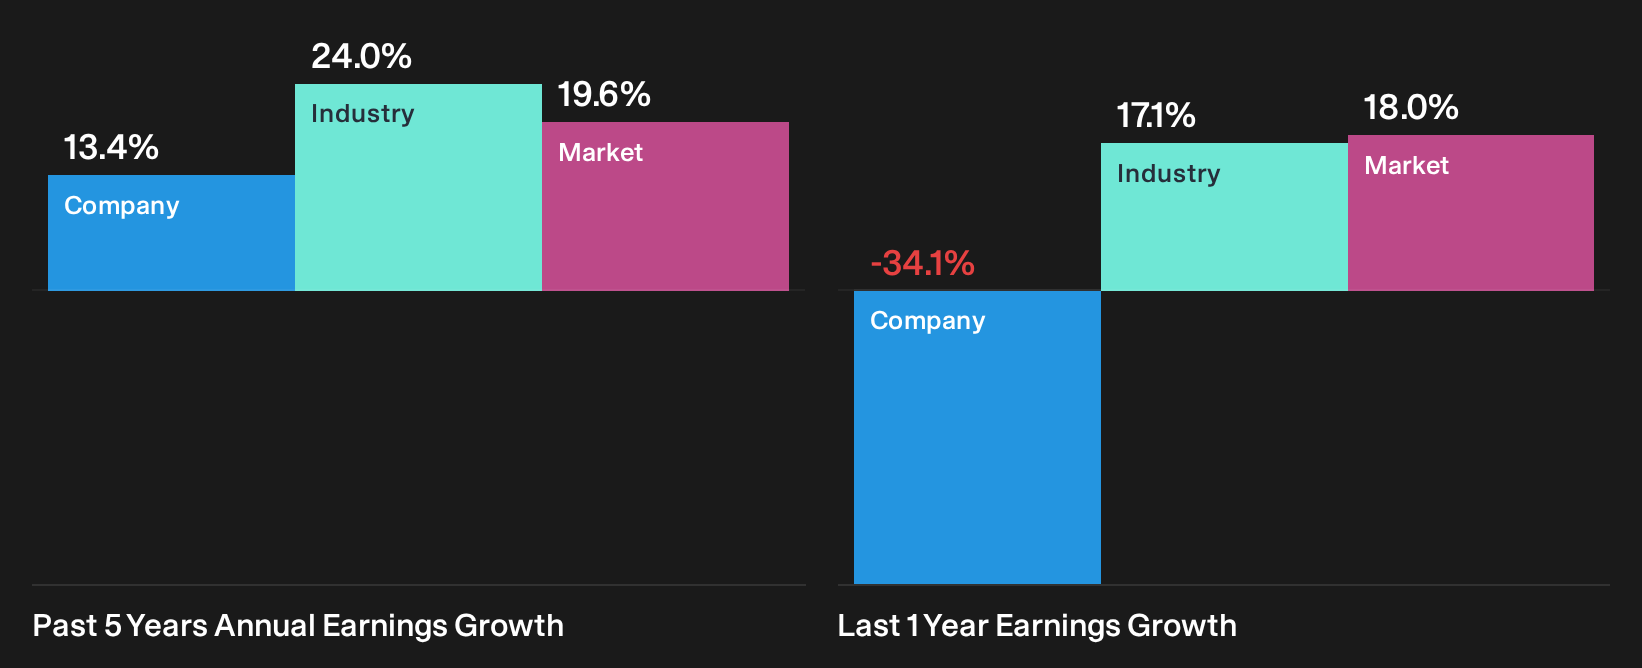
What really shapes that earnings path is how one lingering credit and provisioning pressure interacts with those stickier, cash rich relationships over time.
That lingering pressure is exactly why the full narrative for Bandhan Bank digs into whether Bandhan Bank’s shifting mix can turn credit scars into accelerating returns on those cash rich relationships.
Seeking Alternatives Before The Crowd?
Fresh themes often move first when momentum builds, and under the radar stories can start moving higher before the crowd even looks. Do your homework while it matters and consider acting early.
- Look for smaller companies building real businesses, then scan the 120 elite penny stocks with strong financials that filters for stronger balance sheets instead of story-only momentum.
- Explore structural demand for secure digital assets by checking the curated 20 cryptocurrency and blockchain stocks before that corner of the market changes in valuation.
- Review potential infrastructure-related opportunities and use the 43 power grid technology and infrastructure stocks while those cash generators remain less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com