


PayPal Holdings has seen its share price travel a long way over the past few years, and that mixed journey puts fresh attention on whether the current US$56.05 level still lines up with what its earnings can reasonably support. For anyone considering the stock today, the core issue is what that earnings profile really says about the value on offer.
- PayPal Holdings shares have fallen 79.0% over the last 5 years, which puts more weight on the question of whether the business now generates enough earnings to back up the current market value.
- The company’s model depends heavily on converting payment volumes into consistent profit and cash flow, so any change in take rates or operating efficiency can meaningfully shift what its earnings are worth.
- Your read on PayPal Holdings is one view; the desks covering it have another. See what analysts think PayPal Holdings's shares could be worth.
The issue now is whether the earnings that PayPal Holdings produces today are sufficient to justify the price investors are being asked to pay.
If you want to stress test this same earnings question beyond PayPal Holdings, it can help to compare it with 29 high quality undervalued stocks.
Is PayPal Holdings a Bargain on Earnings?
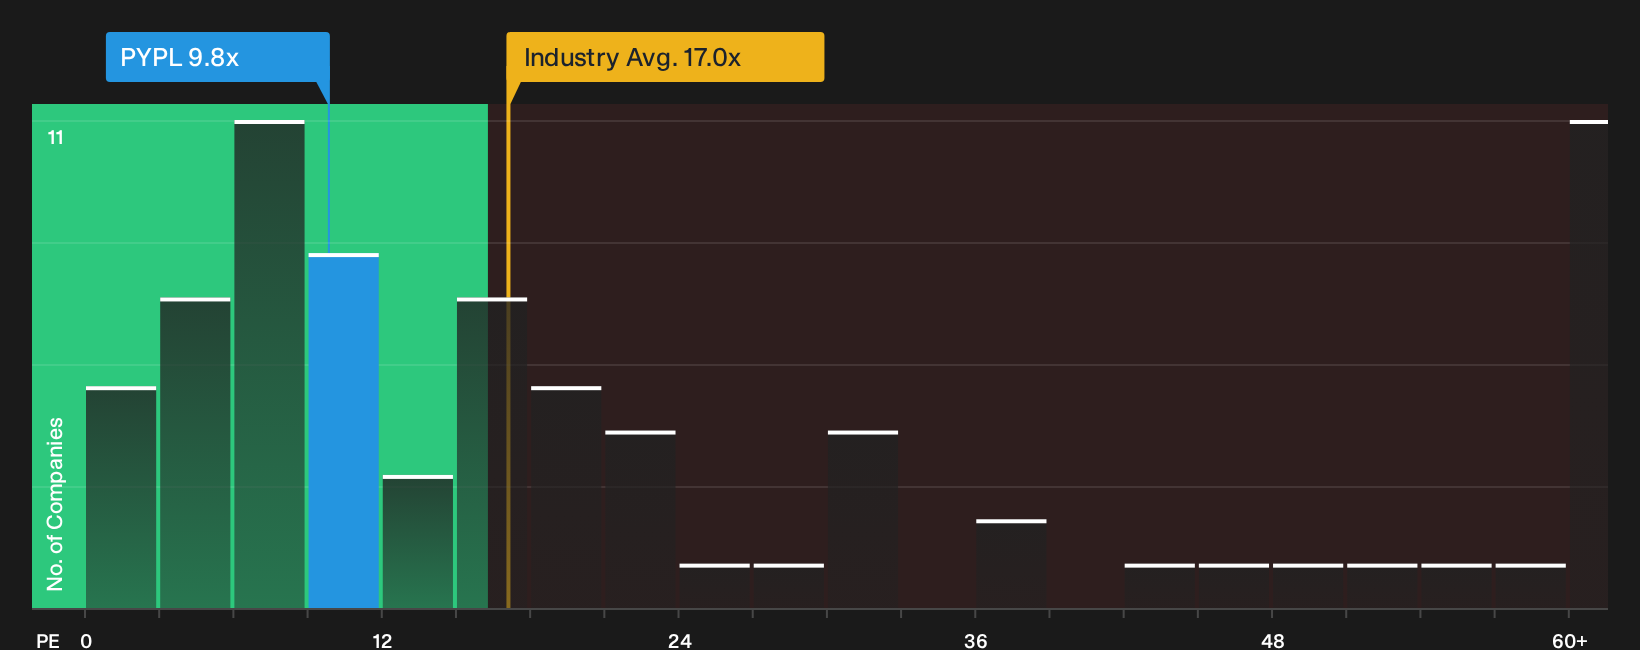
P/E fits PayPal Holdings because earnings remain the main reference point investors watch when judging cash generating power from its payment volumes. On this metric, the stock trades on roughly 9.8x earnings, well below the diversified financials sector average of about 17.0x and the peer group near 51.4x. That is a wide gap for a large scale payments platform with a long operating history.
The Fair Ratio model, which adjusts the P/E you might expect for PayPal Holdings based on factors like profitability, risk and size, also points to a higher level than where the shares change hands today. Together, the discount to both the tailored Fair Ratio and to sector and peer averages suggests the market is pricing PayPal Holdings cautiously relative to many comparable financial platforms. Explore the numbers behind PayPal Holdings's P/E valuation.
The PayPal Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for PayPal Holdings by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each scenario ties a fair value estimate to a specific storyline about PayPal Holdings' potential catalysts and key risks, so you can track over time which version of events is actually unfolding in the real business.
Community views on PayPal Holdings are split between those who see an asset light cash engine and those who are worried about take rate pressure and execution risk.
Bull case: 32% undervalued
"By remaining a "fintech," PayPal retains the flexibility to return that excess capital to you, the shareholder, through its aggressive buyback program…"
Discover why this Narrative puts PayPal Holdings at 32% undervalued.
Bear case: 46% overvalued
"The plan to generate at least US$1.5b in gross run rate cost savings over two to three years, including a roughly 20% workforce reduction…"
Explore why this Narrative puts PayPal Holdings at 46% overvalued.
One more PayPal Holdings check that belongs next to the price tag
Before you lean too heavily on earnings multiples and narrative cases, it helps to weigh a separate set of risk checks that highlight specific pressure points inside PayPal Holdings. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com