


Markets are on edge as Iran and the U.S. square off, and that kind of standoff tends to shuffle where money feels “safe.” Defense and aerospace stocks on our Global Defense & Aerospace Stocks screener sit right in the crosshairs of this shift, which can create both potential opportunity and real risk for your portfolio. This article explains three stocks exposed to this news backdrop and why investors are paying attention now.
The three stocks that follow are only a starting sample, and the full Global Defense & Aerospace Stocks screen surfaced 54 more companies with equally compelling narratives that are not covered below. If you want to identify and analyze potential high conviction ideas across regions and market caps in one place, head straight into the Global Defense & Aerospace Stocks screener.
Cohort (AIM:CHRT)
Cohort is one of the pure-play defense stocks in this screen, with its sensors, communications and cyber capabilities closely linked to government and intelligence budgets across key allied markets.
Cohort generates about £159 million from its Communications and Intelligence division and roughly £147 million from Sensors and Effectors. This provides a relatively balanced mix of electronic warfare, sonar and secure communications activities within a £587 million market cap group.
"Order conversion risk across a long dated book of over £600m and a large pipeline of prospects. If customers defer or cancel programmes such as Italian Navy submarines, Atlantic Bastion or naval communications upgrades, revenue could be pushed out beyond current analyst timelines and increase earnings volatility."
For investors tracking Cohort, a single pressure point in this defense order pipeline could be the swing factor for both cash generation and margin resilience.
That swing factor cuts both ways, and the full narrative for Cohort shows how Cohort could convert order timing risk into accelerating cash generation as defense priorities evolve.

Ducommun (DCO)
Ducommun plugs directly into the Global Defense & Aerospace Stocks theme, supplying the electronics and structures that missile, radar and aircraft programs depend on. This is exactly where investors tend to look when geopolitical risk puts defense spending in sharper focus.
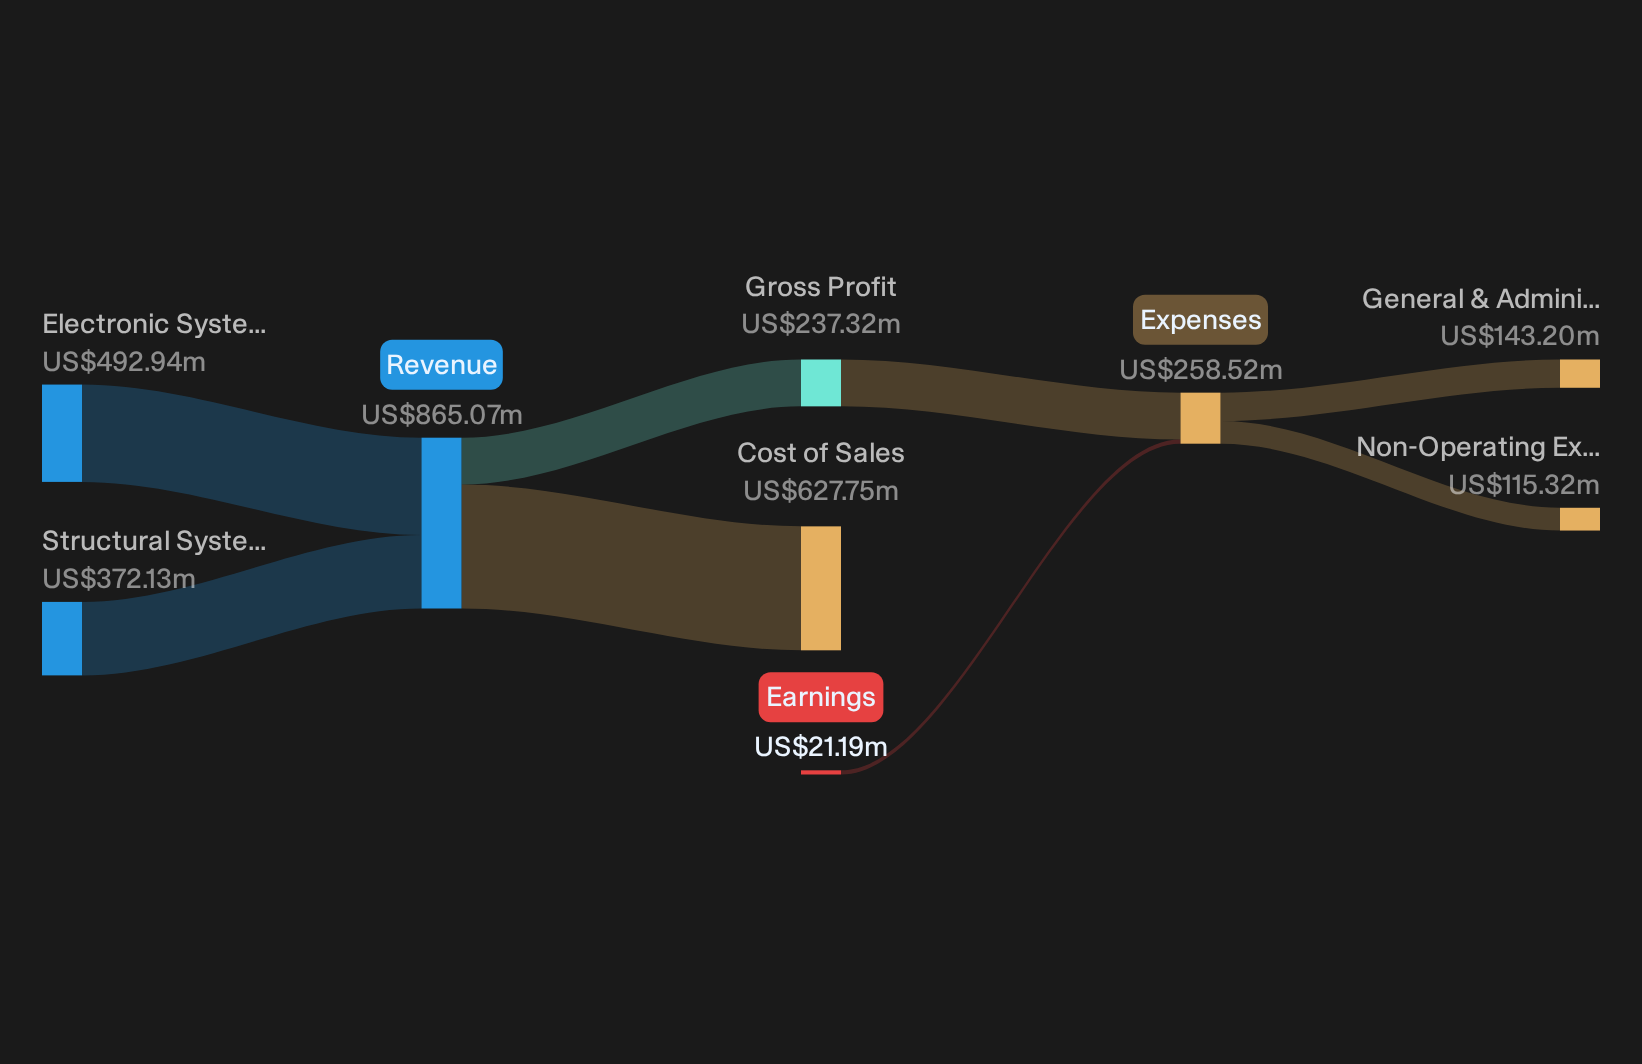
Ducommun is an aerospace and defense engineering group that earns about US$492.9 million from Electronic Systems and US$372.1 million from Structural Systems, giving it a broad mix of defense electronics and aerostructures within a roughly US$2.5b market cap.
"Elevated global defense spending and the replenishment of missile and radar inventories, with Ducommun reporting its missile business up 68% year-on-year in Q2 2026 and missiles, radar and electronic warfare now over 20% of total revenue, points to ongoing program ramps that can support higher defense revenue and earnings over the next several years."
What really matters now is how one unresolved shift in Ducommun’s product mix feeds through to margins as those long dated defense orders convert.
If that mix shift is what you are watching, the full narrative for Ducommun joins the dots on where Ducommun’s defense exposure could be accelerating or quietly stalling.
Graham (GHM)
Graham leans into the Global Defense & Aerospace Stocks theme through its vacuum, fluid and power systems for defense and space customers, while still selling into energy and process markets, which gives investors a different mix of defense exposure than pure weapons contractors.
Graham generates about $261 million by designing and manufacturing heat transfer and vacuum equipment, with a market cap near $954 million that keeps it in the mid cap bracket for this screen.
Graham gives this screen exposure to the plumbing behind torpedoes, Navy propulsion and space hardware rather than the missiles and jets most investors already watch.
"Record backlog of about $557 million with roughly 35% to 40% expected to convert within 12 months, together with about 85% of that backlog tied to defense, points to multi year revenue visibility that some investors may not be fully reflecting in Graham’s current valuation, with potential future support for earnings stability."
What happens when one long cycle defense platform tilts that backlog mix could end up mattering more for Graham’s future margins than any headline today.
When that backlog mix starts to shift, the full narrative for Graham lays out how Graham’s defense exposure could be accelerating, masking risk or quietly reshaping long term returns.

Seeking Alternatives Beyond Defense Screeners
Fresh ideas can move first. Breakout momentum often flies under the radar for now, and the best entry points get caught quickly. Scan these curated lists and get in early.
- Target resilient cash generators before the crowd clocks them by scanning the list of solid balance sheet and fundamentals (9 results) that filters for financial strength while it still matters.
- Ride early momentum in high potential miners by tracking the 36 elite gold producer stocks curated for disciplined producers while sentiment is still dropping elsewhere.
- Spot early leaders in next wave automation by running the 91 robotics and automation stocks and pinpointing companies building real revenue engines before valuations run away.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com