


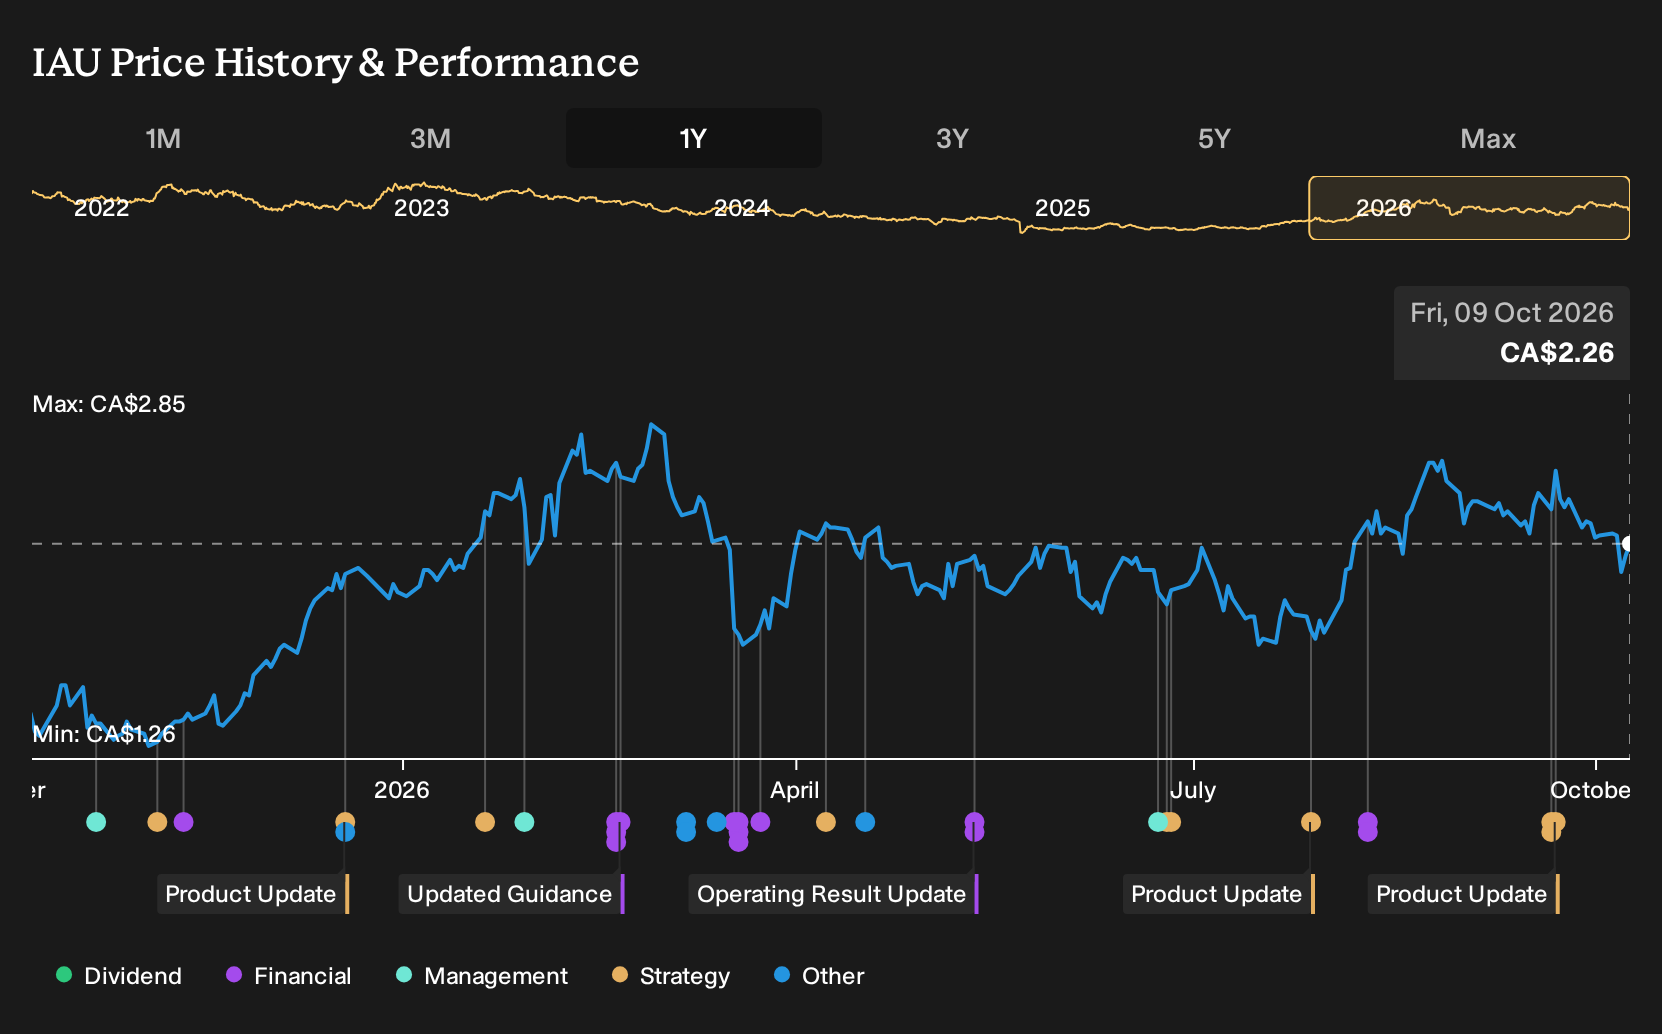
If you only glanced at i-80 Gold’s latest results, the story looked rough. Revenue slipped and losses widened as net margin moved further into the red. Yet investors who held i-80 Gold over the past year are up 54.8%, including dividends. If you had bought on 9 October 2025, that gap between weaker reported performance and strong share gain would be hard to ignore. So what exactly was the market rewarding?
i-80 Gold is not the only name tied to this theme. Zero in on 36 elite gold producer stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On i-80 Gold
The shares cost CA$1.33 at the start of the period, and i-80 Gold sat between two very different stories about where its Nevada projects might lead.
The bullish view pointed to a Fair Value of CA$2.28, a rough guide to what that camp thought the stock should be worth if things played out as hoped, assuming stronger revenue from Granite Creek, higher recovery rates from a refurbished Lone Tree autoclave, and in-house processing that could lift cash generation.
The bearish narrative anchored on a Fair Value of CA$1.05 and treated the same expansion as a source of strain, focusing on the need for roughly CA$900 million to CA$950 million of funding, the risk of shareholder dilution from fresh equity and debt, and Nevada specific regulatory or environmental hurdles that could push up costs.
What The Evidence Did To The i-80 Gold Argument
The clearest new fact for i-80 Gold was operational. Management secured more than US$1b of financing and reported record Q1 2026 revenue and gross profit as Granite Creek output and processing shifted, which backed the bullish focus on funding and mine build out. At the same time, Q2 2026 revenue slipped to US$24.348m and the business logged a larger loss, with net margin moving further into the red, so profitability progress remained unproven.
The lesson is simple. When a miner leans on a build out story, test the pitch against two things: fresh financing capacity and the direction of net margin once that capital starts to be spent.
What You Would Be Paying For In i-80 Gold Today
At today’s CA$2.26 share price, this Narrative’s Fair Value sits above the market level, based on a view that i-80 Gold can turn its Nevada build out into stronger revenue and healthier cash generation over time.
The pitch leans on higher grade output, in-house processing and Lone Tree progress. A buyer now would need to judge whether ramp up milestones and cost discipline at these projects keep tracking the story that underpins that higher figure.
"Key Takeaways: Increased production from Nevada projects, infrastructure upgrades and high gold prices are described as factors that could support revenue, cash flow and margins. Continued exploration and in-house processing are also highlighted as potential supports for long-term reserve growth and as factors that could position the company in light of sector supply constraints."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where The i-80 Gold Theme Extends
i-80 Gold highlights metals pulled from the ground, but that is only one step.
Electric vehicles, wind farms and defense gear all rely on powerful permanent magnets.
One specialist producer focuses on rare earth materials that sit inside those components.
This business is expanding processing, magnet manufacturing and recycling capacity instead of stopping at raw concentrate.
Government contracts and long duration supply deals aim to support demand, while scaling downstream efficiently remains the unresolved test.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 68% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com