


Kyocera (TSE:6971) has just wrapped up a sizeable share repurchase, buying 49,227,800 shares for ¥177,628.19 million, alongside fresh printhead product announcements that push deeper into logistics, healthcare, and decorative label and packaging markets.
These moves come after a powerful run in Kyocera’s share price, with a 30 day share price return of 7.15% and a year to date share price return of 70.51%, while the 1 year total shareholder return of 97.81% and 5 year total shareholder return of 155.46% point to momentum that has been strong over both shorter and longer horizons.
Spot opportunities riding similar logistics and digital traceability trends by scanning our hand picked 91 robotics and automation stocks that are also targeting automation and industrial efficiency.After a ¥177,628.19 million buyback and fresh printhead launches, Kyocera now trades above the average analyst target while still sitting at a discount to intrinsic value estimates. Is this a sign of caution from the market, or a mispriced rerating story?
Price-to-Earnings of 30x: Is it justified?
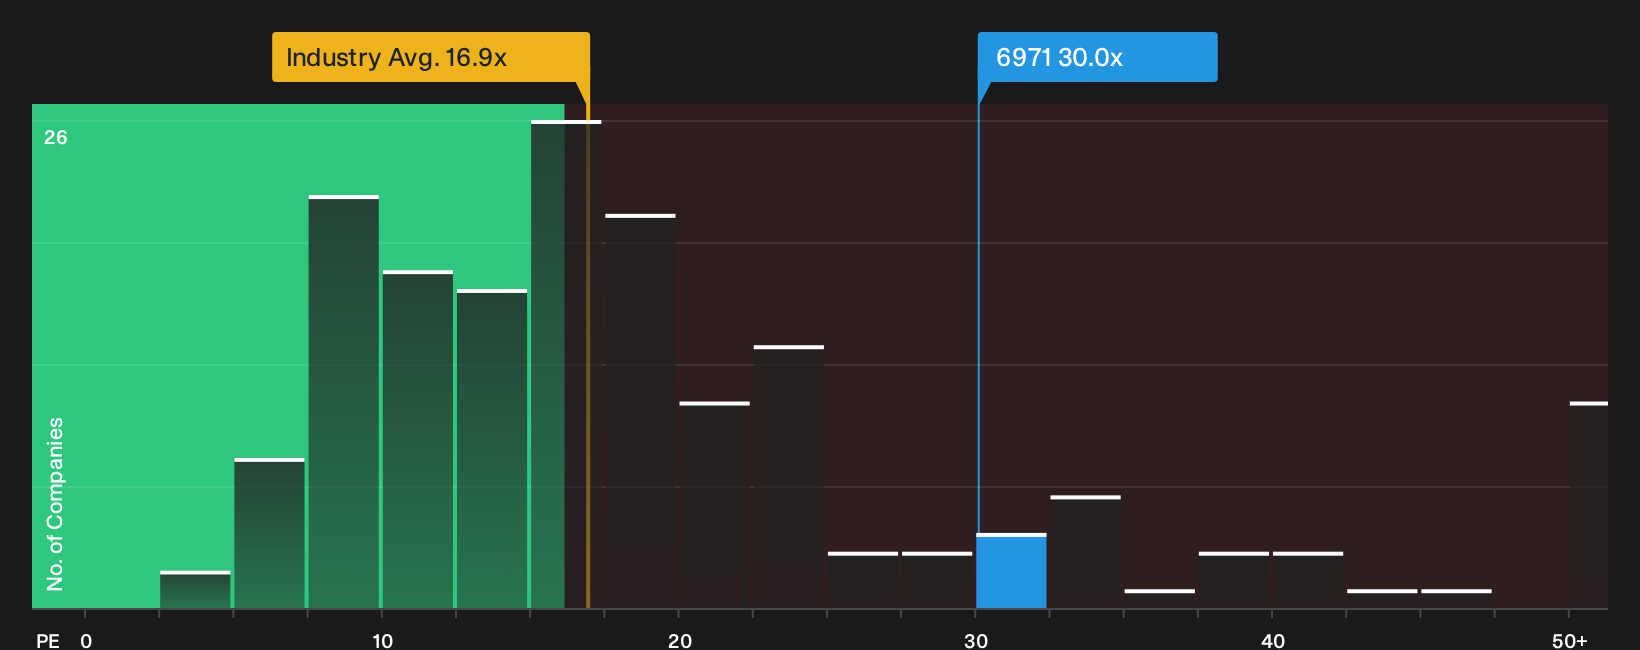
Kyocera now trades on a P/E of 30x with a last close of ¥3,805, which looks rich compared to both its own fair multiple estimate and sector peers.
The P/E ratio compares the current share price with earnings per share and gives a shorthand view of how much investors are paying for each unit of profit. For a diversified tech and industrial components group like Kyocera, this metric often reflects expectations around earnings durability across segments such as Core Components, Electronic Components, and Solutions.
There is a clear tension between the current valuation and the reference points provided. Kyocera is flagged as expensive versus the estimated fair P/E of 19.7x, which is a level the market could move towards if enthusiasm cools. The same 30x multiple is also described as expensive compared to the JP Electronic industry average of 16.9x, meaning investors are paying a much steeper price for its earnings than for the wider peer group.
Explore the SWS fair ratio for Kyocera.
Result: Price-to-Earnings of 30x (OVERVALUED)
Still, Kyocera’s premium P/E and a share price that already sits above the average analyst target could quickly look exposed if earnings momentum or buyback activity slows.
Find out about the key risks to this Kyocera narrative.
Another View on Kyocera’s Value
A different lens tells a softer story. On a peer comparison, Kyocera’s P/E of 30x is described as good value against a 59.8x average, even if it still looks expensive versus the JP Electronic industry on 16.9x. That split raises a sharper question: Is the risk that expectations are too high for the sector, or just too high for Kyocera specifically?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyocera for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 12 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Kyocera is clearly mixed, with valuation signals pulling in different directions, so it makes sense to review the underlying data directly before forming a view. To see what the upside case looks like in more detail, take a closer look at the 2 key rewards
Looking for more investment ideas beyond Kyocera?
If you stop with Kyocera, you miss a wider set of opportunities. Use the screener to line up fresh ideas and pressure test your current watchlist.
- Hunt for potential mispricings by scanning a 12 high quality undervalued stocks that already combine quality fundamentals with what may be appealing entry points.
- Target steadier profiles by reviewing 23 resilient stocks with low risk scores that score well on resilience and may help balance out more volatile positions.
- Spot under followed potential opportunities by checking 74 high quality undiscovered gems that pair solid financials with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com