


AI has gone from market hero to potential hazard in a matter of months, with warnings from Broadcom and the IMF turning hype into hard questions about debt, risk and pricing. That kind of shock can punish anything loosely linked to the theme, including bond and credit-focused asset managers. It also throws up mispriced opportunities. This piece walks through three stocks from our Global Corporate Bond and Credit-Focused Asset Managers screener that appear particularly exposed to the AI story right now.
The three stocks covered below are only a slice of the idea, with the full screen surfacing 38 more asset managers and ETF groups whose credit stories are just as interesting but not unpacked here. If you want to identify which of those fixed income focused businesses best match your risk, income, and quality filters, head straight into the Global Corporate Bond and Credit-Focused Asset Managers screener.
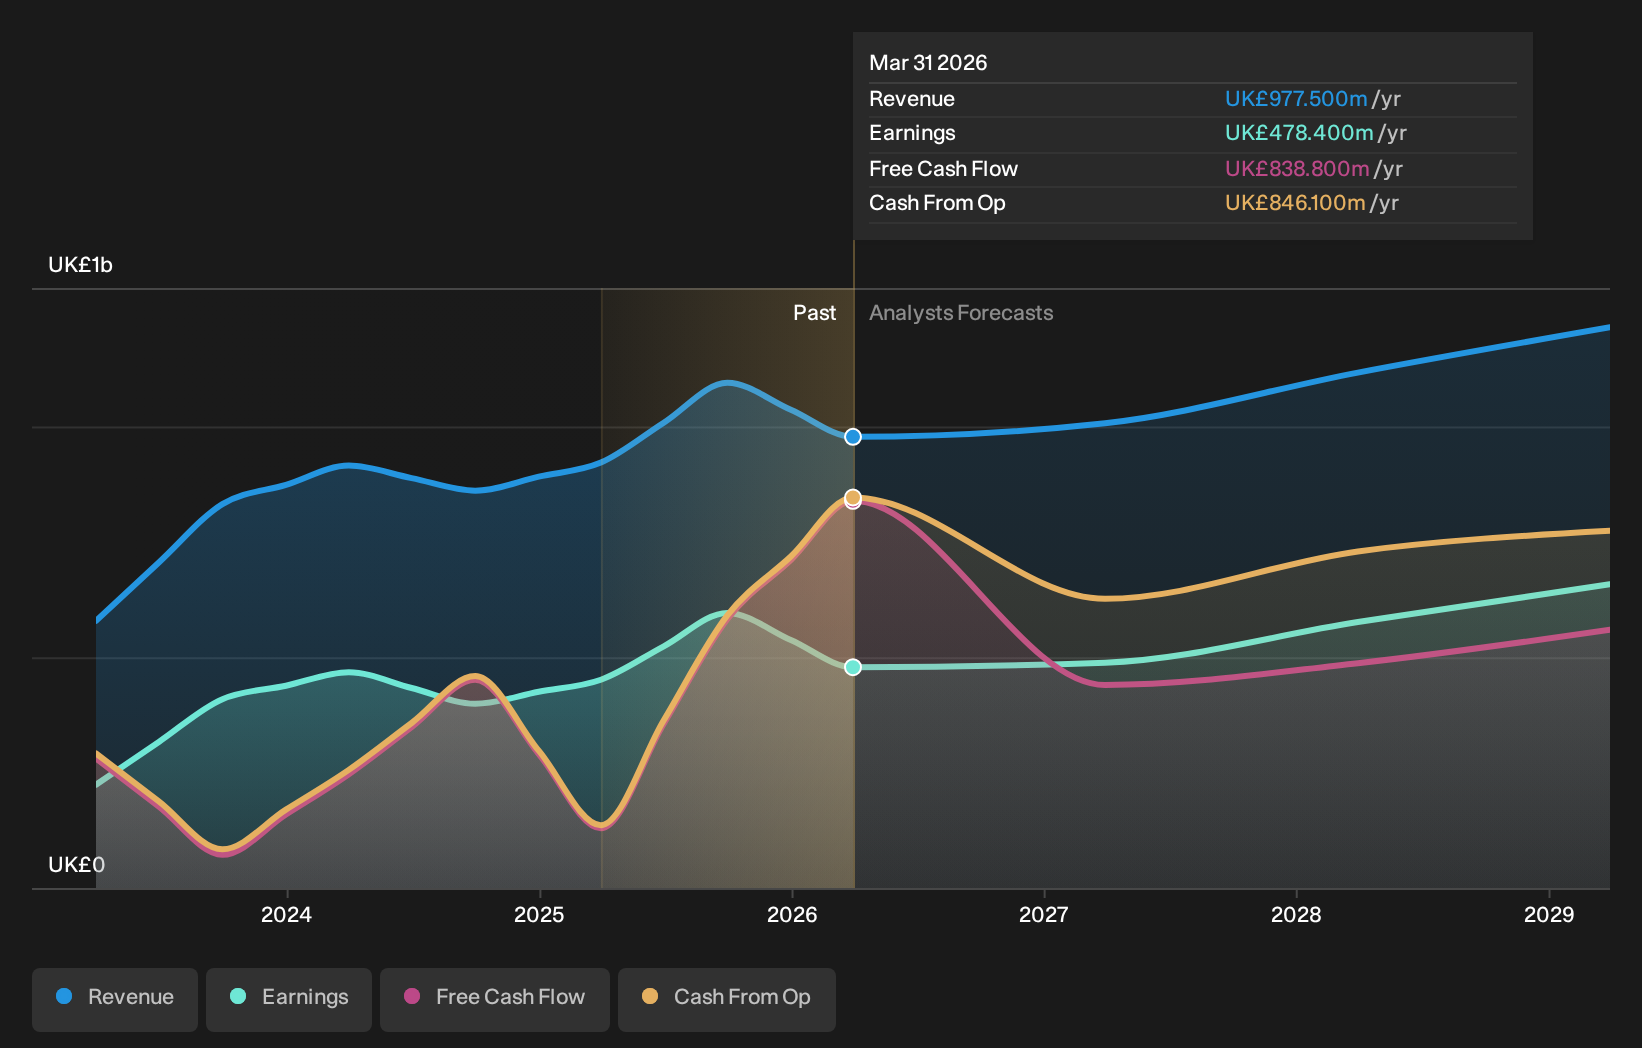
St. James's Place (LSE:STJ)
Overview: St. James's Place is a UK-based wealth manager that runs global equity, fixed income, and balanced funds through adviser-led relationships.
Operations: The group generates about £44.8b of wealth management revenue almost entirely from clients in the United Kingdom.
Market Cap: £5.3b
St. James's Place matters for this credit-focused screen because it channels client savings into diversified portfolios, including bond strategies that can look more appealing when AI-linked equities feel fragile.
"The company is capitalising on significant intergenerational wealth transfer, with more younger clients being acquired and actively engaged through the adviser academy and digital initiatives. This positions SJP for sustainable long-term AUM growth and improved client retention, benefitting future revenue and earnings."
What happens to those ambitions if a single unseen pressure quietly reshapes how clients weigh guaranteed income against market-linked returns?
Those shifting preferences are exactly where the full narrative for St. James's Place shows how St. James's Place could turn AI anxiety into accelerating client demand for income and advice-first portfolios.

Moody's (MCO)
Overview: Moody's is a global risk assessment group that rates debt, analyzes credit, and sells software and data tools to bond market participants.
Operations: Moody's generates about US$3.7b from Moody's Analytics and US$4.7b from Moody's Investors Service, with most income tied to US and EMEA clients.
Market Cap: US$81.5b
Moody's matters for this credit-focused screen because every extra dollar of corporate and AI-linked bond issuance flows through its ratings and analytics, giving the stock direct exposure to how confidently debt markets keep funding the AI build out.
"What makes the story even stronger today is that Moody’s is no longer only a ratings company. Over the past decade, management has steadily built Moody’s Analytics (MA) into a major recurring-revenue software and data business."
The key question is what happens to that mix if a single unseen pressure quietly changes how issuers, regulators, and investors price credit risk across the AI debt cycle.
If that hidden pressure is what you care about, read the full narrative for Moody's to see how Moody's credit engine could accelerate or stall as AI debt cycles evolve.

ICG (LSE:ICG)
Overview: ICG is a London based private markets manager that focuses on private credit, secondaries, structured capital and real assets globally.
Operations: ICG generates about £897.7 million from its Fund Management Company segment, with most income coming from Europe including the UK and North America.
Market Cap: £4.9b
ICG matters for this credit focused screen because it channels long term institutional and wealth money into private debt, structured loans and other income oriented assets. These can look appealing when listed bond markets feel more volatile.
"Although the tilt towards higher returning strategies in structured capital, secondaries and real assets has lifted the weighted average management fee rate to just under 1%, the move into more complex, higher barrier products increases execution risk."
What happens to ICG’s appeal as a credit linked asset manager if a single assumption about fund raising momentum quietly starts to shift?
If that assumption is starting to wobble, read the full narrative for ICG to see whether execution risk is masking an accelerating opportunity in ICG’s credit platform.
Seeking Alternatives Before The Crowd Moves
Fresh themes keep breaking out while older stories lose momentum or get caught by dropping sentiment. Use these curated ideas while it matters and get in early.
- Target reliable payers with strong balance sheets by scanning the curated 1 dividend fortresses before yields and entry prices move away from comfortable levels.
- Hunt for early AI momentum where profits already matter by working through the hand picked 39 profitable AI stocks that aren't just burning cash before valuations get ahead of the story.
- Position for potential future infrastructure opportunities by checking the focused 43 power grid technology and infrastructure stocks while these grid upgrades remain relatively under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com