


AI has gone from buzzword to budget line, and the IMF is now warning that if this boom hits a wall, the shock could ripple through credit markets well beyond the tech giants. That mix of promise and risk is exactly where careful stock selection can matter most, especially for investors who dislike the idea of missing a major turn in global credit. This article reviews three investment grade-focused stocks from our Global Investment-Grade Credit & Loan Funds screener that are closely linked to the AI narrative and recent macro headlines, and outlines why some investors are watching them more closely after the IMF’s latest AI and growth warnings.
The three stocks in this article are just a starting sample. The full screen surfaced 15 more investment grade-focused companies with equally compelling credit and loan stories that are not covered here. To identify and analyze the highest conviction ideas tied to this theme, head straight into the Global Investment-Grade Credit & Loan Funds screener
Ridgepost Capital (RPC)
Overview: Ridgepost Capital is a Dallas based alternative asset manager providing multi-asset private market solutions, including private equity, venture capital, impact investing, and private credit strategies that link investors to diversified credit exposures.
Operations: Ridgepost Capital generates US$312.9 million in asset management fees, almost entirely from clients in the United States.
Market Cap: US$903 million
Ridgepost Capital provides investors access to private credit and loan focused portfolios tied to higher quality corporate borrowers, which is consistent with this investment grade credit theme. The stock offers exposure to fee based asset management, with an alternative approach to traditional banks for credit risk. Many outcomes depend on how one unseen pressure ultimately affects funding costs and fee stability.
If that unseen pressure worries you, go straight to the 4 key rewards and 3 important warning signs (2 are major!) to see what might be masking risk or pointing to underappreciated upside.
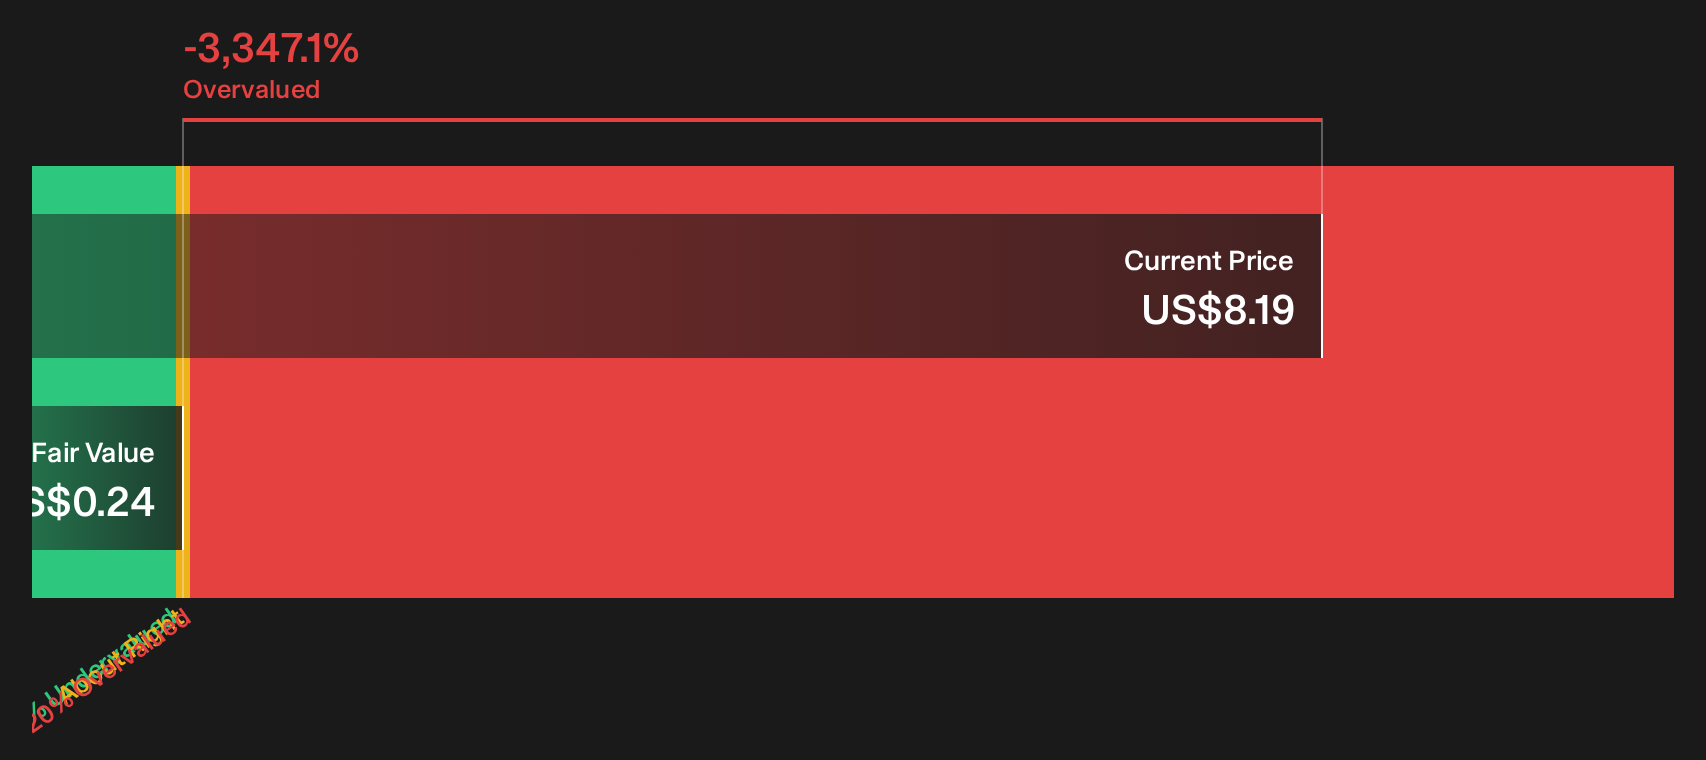
CapMan Oyj (HLSE:CAPMAN)
Overview: CapMan Oyj is a Nordic private assets manager that raises funds to invest in real assets, private equity and credit financing for unlisted companies.
Market Cap: €306 million
For the Global Investment-Grade Credit & Loan Funds theme, CapMan Oyj matters because it channels institutional money into private debt and real asset financing that sit close to investment grade borrowers, yet behave very differently from listed corporate bonds when markets turn.
"Expanding real assets platform, including Real Asset Debt and larger open ended real estate funds in resilient segments such as residential, social real estate and hotels, positions CapMan to capture renewed institutional demand for income focused strategies and enhance recurring management fee margins."
What those fee streams look like a few years from now hinges on how one quiet shift in investor appetite for illiquid credit plays out.
That quiet shift is the hinge. Read the full narrative for CapMan Oyj to see how CapMan Oyj’s income engine could accelerate or stall as credit cycles turn.

CARE Ratings (NSEI:CARERATING)
Overview: CARE Ratings is a Mumbai based credit rating agency that assesses the creditworthiness of borrowers and instruments across India and select international markets.
Operations: CARE Ratings generates ₹4.4b from ratings and related services and ₹531m from other activities, with ₹4.9b of revenue coming from India.
Market Cap: ₹45.9b
CARE Ratings matters for this Global Investment-Grade Credit & Loan Funds theme because its opinions directly influence how higher quality borrowers are priced in bond and loan markets.
"India's ongoing move towards greater formalization and transparency, along with regulatory reforms (for example, mandatory ratings by IFSCA-registered agencies), is expected to structurally increase demand for credit ratings. This is expected to result in sustained top-line growth as more entities access capital markets and require ratings."
What investors really need to watch is how any shift in pricing power between issuers and rating agencies reshapes those economics.
That pricing shift is exactly where the full narrative for CARE Ratings shows how CARE Ratings’ earnings power could accelerate, decouple from peers, and reprice perceived risk.

Seeking Fresh Alternatives Before They Fly
Some opportunities are already building quiet breakout momentum, while others risk getting caught once the crowd piles in. Scan these fresh stock ideas now, while it matters, and consider them at an early stage.
- Spot early-stage turnarounds that still look under the radar for now by running the 20 high quality undiscovered gems before the rest of the market focuses on them.
- Lock onto resilient payers built for income stability by reviewing the 8 dividend fortresses before yields change or valuations move away from attractive entry points.
- Track real businesses connected to the crypto theme by scanning the 20 cryptocurrency and blockchain stocks while these stocks remain mispriced and sentiment continues to swing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com