


The IMF is warning that high public debt and rising borrowing costs could weigh on future returns from broad markets. Reliable cash payouts suddenly look a lot more appealing. This is where high-yielding, well-covered and steadily growing dividend payers come in. The article walks through three income-focused stocks from a 3% plus yield screen that can help anchor a portfolio when headlines get noisy.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher yielding, well covered dividend payers with stable and growing distributions. However, if you want the absolute best, these 8 dividend aristocrats stocks are the cream of the crop.
DRDGOLD (DRD)
Overview: DRDGOLD extracts gold from processing surface mine tailings in South Africa, turning legacy waste dumps into cash-generating production assets.
Operations: DRDGOLD generates ZAR 8,080 million from the Ergo segment and ZAR 3,079 million from FWGR, with all ZAR 11,159 million revenue earned in South Africa.
Market Cap: US$2.1b
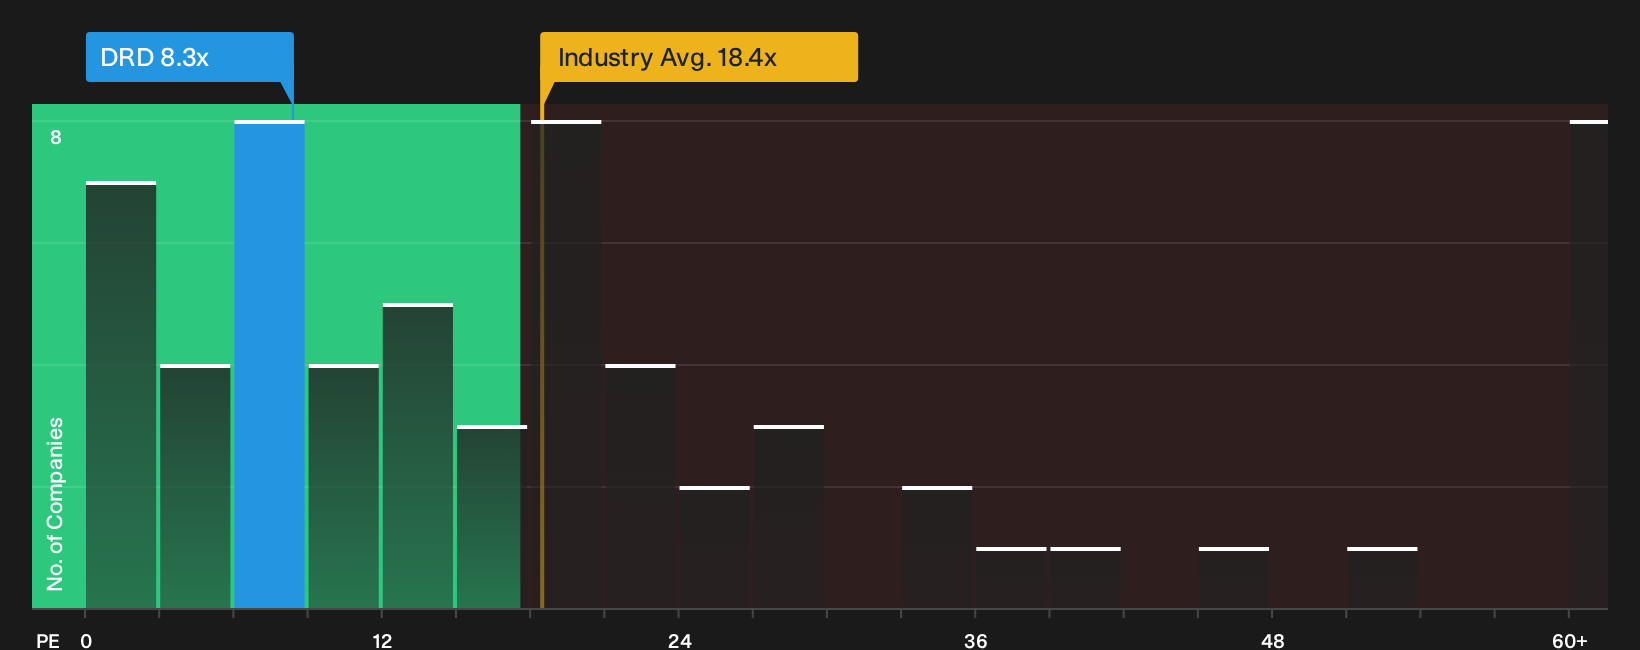
DRDGOLD ties directly into the Dividend Powerhouses theme because its tailings retreatment business throws off cash that supports sizeable payouts, including a record 120 SA cents final dividend in 2026 and 19 consecutive years of distributions. Income investors see a high yield and single digit 8.3x P/E, although payout reliability still depends on one pressure point in the funding mix.
That single funding pressure point is exactly what many investors want unpacked, so go straight to the 2 key rewards and 2 important warning signs (1 is major!) for a closer look at how DRDGOLD’s yield profile compares.
Brown-Forman (BF.B)
Overview: Brown-Forman sells Jack Daniel’s, Woodford Reserve and a wider spirits portfolio that generates recurring cash flow used to support its dividend.
Operations: Brown-Forman generates US$3.9b from Beverage Alcohol Consumer Products, with US$1.9b recorded in the United States and the remainder internationally.
Market Cap: US$12.4b
For income investors, Brown-Forman matters because its long-lived whiskey labels and wider spirits portfolio have supported a 3% plus dividend that aims to be steady, well covered and growing over time.
"Brown-Forman is still shifting its business mix toward international markets after moving from a sales split of 80% U.S. and 20% international to 40% U.S. and 60% international, with recent 9% organic net sales growth in emerging markets such as Mexico and the UAE pointing to further potential support for revenue diversification and earnings resilience."
What ultimately happens to that dependable payout may hinge on how one quiet margin and cash flow pressure resolves over the next few years.
If that margin squeeze is what you are watching, read the full narrative for Brown-Forman to see whether Brown-Forman’s payout story is quietly accelerating or stalling here.

Accenture (ACN)
Overview: Accenture helps large organisations modernise operations by delivering recurring cloud, data and AI services that support consistent, well-covered dividends.
Operations: Accenture generates about US$22.5b from Products, US$15.2b from Health & Public Service, US$14.0b from Financial Services, US$12.7b from Communications, Media & Technology and US$9.9b from Resources, with most revenue coming from the Americas, then EMEA and Asia Pacific.
Market Cap: US$128.1b
Accenture appears in a dividend-focused screen because its long-term cloud, data and AI outsourcing work behaves much closer to a subscription than one-off consulting, which can help support a yield investors may plan around.
"AI could reduce the need for traditional consulting, coding, testing, documentation, support, and outsourcing roles."
What really shapes the income story from here is how one quiet shift in contract mix ultimately lands on pricing power and margins.
That contract mix shift is exactly what income investors need to understand. Read the full narrative for Accenture to see whether Accenture’s dividend engine is quietly accelerating.

Seeking Alternatives Before The Crowd?
Fresh opportunities rarely stay quiet for long. Breakout ideas can gain momentum fast, and by the time headlines catch up the easy entry points may no longer be available.
- Spot early movers in potential AI leaders by scanning 38 profitable AI stocks that aren't just burning cash that already support their stories with earnings instead of relying on hope and cash burn.
- Target resilient payers by focusing on 8 dividend fortresses that combine higher yields with balance sheets structured to handle tougher borrowing costs.
- Look for relatively under the radar stability through the list of solid balance sheet and fundamentals (25 results) so you can monitor financially robust candidates before they receive broader attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com