


Man Group has logged a strong share price run in recent years, which puts fresh attention on what investors are paying for each pound of earnings. With that backdrop, the key issue now is whether the current valuation can be squared with what the business is actually earning.
- Over the past 5 years the stock has returned about 99.0%, so a lot of future earnings power is implicitly on the line in today's price.
- The group earns fees on assets it manages, so any change in profitability or fee mix can quickly alter how much of that revenue stream ultimately turns into sustainable earnings.
- The analysts covering Man Group have run their own numbers. See what analysts think Man Group's shares could be worth.
The stock's next move may depend on whether Man Group's current share price is well supported by its earnings profile.
If you are questioning whether Man Group's recent earnings justify its share price, it can help to compare that picture with a focused list of 8 high quality undervalued stocks.
Where Does Man Group Sit on Earnings?
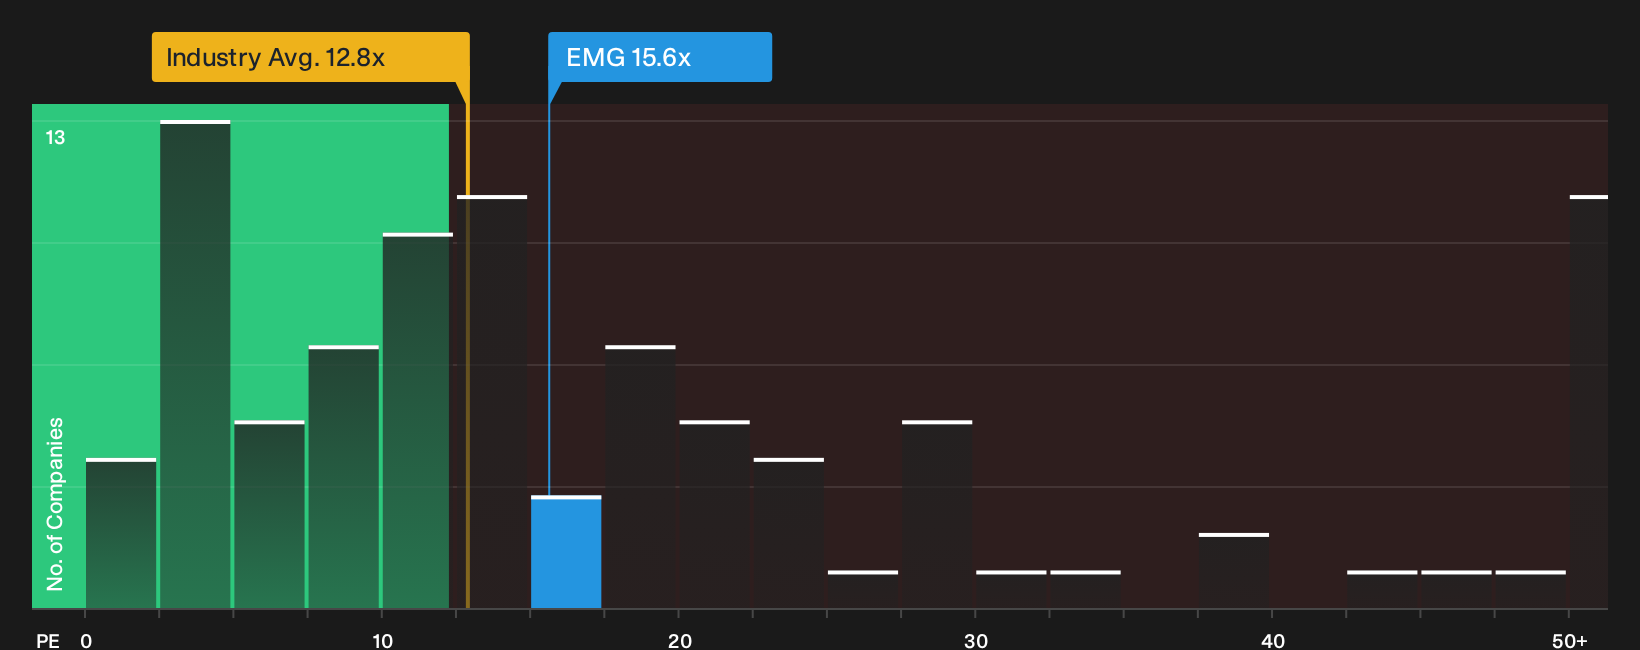
The P/E ratio fits Man Group because investors focus heavily on what it earns from managing client assets. Right now the stock trades at about 15.6x earnings, which sits below the peer average near 39.5x but above the wider capital markets industry on roughly 12.8x. That mix suggests the market is giving the business some credit for its fee model and return profile, without pricing it at the upper end of the sector.
A fair-value framework that blends Man Group's expected growth, profitability and risk points to a P/E level slightly above where the shares trade today. The current multiple sits just under that reference point, which implies the price is broadly in line with what those fundamentals support. For you as a shareholder, that places more weight on whether future earnings match the profile embedded in that fair P/E level. Explore the numbers behind Man Group's P/E valuation.
The Man Group Narrative: What Would Justify Today's Price?
Narratives pick up where that P/E puzzle leaves off by spelling out which paths for Man Group's growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today. Each one links its number to a specific view on how growth, profitability and risk could evolve from here, giving you something you can come back to as new figures and updates roll in on Simply Wall St's Community page.
On Man Group, community views are split between those who see more upside in the story and those who think the current pricing already bakes most of it in.
Bull case: 7% undervalued
"Robust global institutional demand for alternative and customized investment solutions continues to drive strong net inflows, positioning Man Group for sustained AUM and recurring fee income growth…"
Discover why this Narrative puts Man Group at 7% undervalued.
Bear case: roughly fairly valued
"The accelerating adoption of passive, low-fee investment solutions such as ETFs continues to undercut the appeal of actively managed and alternative products like those offered by Man Group, threatening to erode their ability to attract and retain assets…"
Explore why this Narrative puts Man Group at roughly fairly valued.
For Man Group, price is only one piece of the decision
Before treating Man Group's valuation as the full story, it is worth knowing that Simply Wall St's checks have highlighted specific areas of concern that some investors may want to weigh carefully. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com