


Why YASKAWA Electric’s Latest Earnings Matter For Investors
YASKAWA Electric (TSE:6506) just reported half year 2026 results with higher sales and net income than a year earlier, and management lifted full year revenue and profit guidance for fiscal 2027.
This combination of reported performance and updated outlook gives investors fresh data on how demand for YASKAWA Electric products is translating into earnings, ahead of the H1 2027 earnings call scheduled for October 13, 2026.
Recent price action reflects that earnings update. YASKAWA Electric’s share price has delivered a 12.53% gain over the past month but is still down 11.84% over the last quarter, while the 1 year total shareholder return of 20.8% indicates that momentum is building over a longer horizon.
Scan how YASKAWA Electric’s robotics momentum compares with peers by reviewing the hand picked 91 robotics and automation stocks shaping the next leg of factory automation.
After that sharp rebound and with YASKAWA Electric still trading well below the average analyst target, the real tension is simple: Does fair value sit closer to the market’s caution or the richer valuation implied by estimates?
Price-to-Earnings of 34.9x: Is It Justified For YASKAWA Electric?
Valuation currently leans rich for YASKAWA Electric, with the stock on a P/E of 34.9x while last closing at ¥4,840, well above both peer and fair P/E reference points.
The P/E ratio compares the share price to earnings per share and shows how much investors are paying for each unit of profit. For an automation specialist like YASKAWA Electric, that multiple often reflects what the market is willing to pay for its earnings profile in areas such as Motion Control and Robotics, where future demand expectations can play a large role.
Here the market is paying a much higher P/E than both the peer average of 18.9x and the broader JP Machinery industry on 13.2x. The estimated fair P/E of 25.6x is also well below the current 34.9x. This points to investors assigning a premium that the market could eventually move away from if expectations cool.
The premium valuation is just as stark against the estimated fair ratio. The current 34.9x P/E sits significantly above the 25.6x level that the fair ratio suggests.
Explore the SWS fair ratio for YASKAWA Electric.
Result: Price-to-Earnings of 34.9x (OVERVALUED)
Still, YASKAWA Electric’s rich 34.9x P/E and sensitivity to automation spending cycles could quickly pressure that premium if sentiment or orders soften.
Find out about the key risks to this YASKAWA Electric narrative.
Another View On YASKAWA Electric’s Valuation
There is a very different message coming from our DCF model. YASKAWA Electric trades at ¥4,840, while the estimated future cash flow value sits at ¥2,884.3, which screens as overvalued on this method. So which signal should carry more weight for you: earnings multiples or cash flows?
Look into how the SWS DCF model arrives at its fair value.
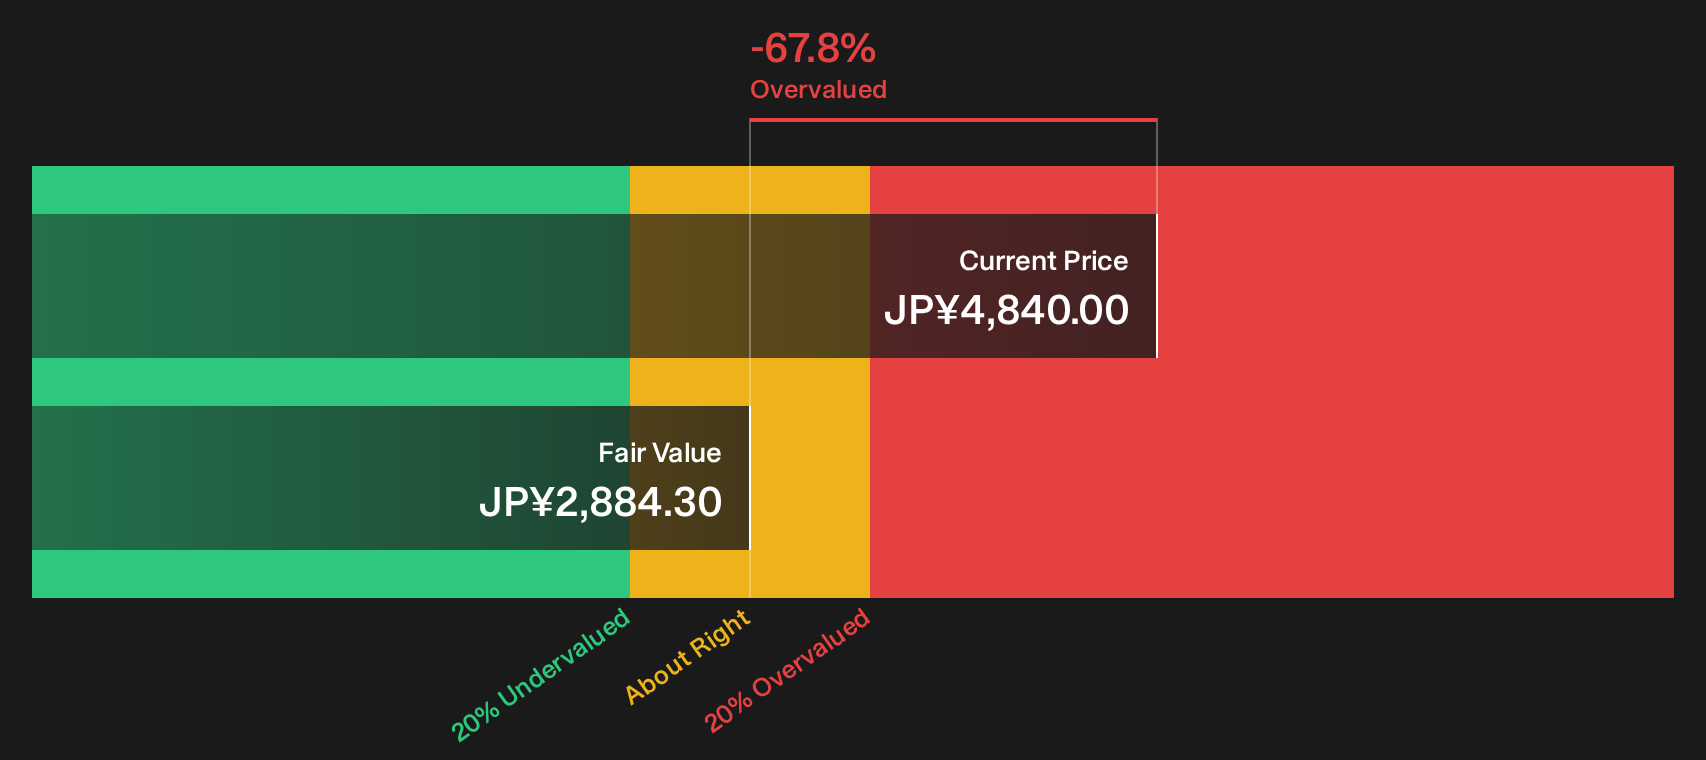
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out YASKAWA Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on valuation and sentiment can be useful if you are willing to interrogate the numbers yourself and not just rely on headlines. If you want a concise snapshot of both sides of the story on YASKAWA Electric, start with the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond YASKAWA Electric?
If you are only watching YASKAWA Electric, you might miss other opportunities. Broaden your watchlist now so you are not reacting after the move.
- Target potential mispricings by scanning a 13 high quality undervalued stocks that combine resilient earnings power with more modest expectations baked into the price.
- Secure potential income ideas by focusing on a 27 dividend fortresses that prioritise yield alongside balance sheet strength and payout consistency.
- Protect your downside by concentrating on a 24 resilient stocks with low risk scores built around resilient fundamentals and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com