


Nipro (TSE:8086) drew fresh attention after announcing that its U.S. unit completed enrollment in the GREAT pivotal trial for the investigational Golazo Peripheral Atherectomy System targeting peripheral artery disease.
For context, Nipro’s latest share price of ¥1,350.5 leaves the 1 year total shareholder return down 6.64%, even though the 3 year total shareholder return is up 32.23%. This suggests that longer term holders are still sitting on gains despite weaker recent momentum.
Scan beyond Nipro and see how other medical and healthcare equipment stocks are positioned with our hand picked list of solid balance sheet and fundamentals (21 results).
Bulls point to Nipro’s clinical progress and the gap to analyst price targets, while bears highlight the recent share price slide. Which story does the current valuation actually support next?
Price-to-Earnings of 16x: Is it justified?
Nipro trades on a P/E of 16x, which places the current ¥1,350.5 share price slightly above both its own cash flow value and the sector average.
The P/E ratio links what investors are paying today to the earnings the business is currently producing. For a medical equipment group like Nipro, which operates across devices, pharma products and packaging, this metric helps you see how the market prices each unit of profit in a sector where scale and product breadth matter.
On one side, Nipro is classed as good value against a fair P/E estimate of 18.9x and against a peer average of 19.4x. That suggests the current multiple leaves room for the market to move closer to that fair ratio if earnings hold up. On the other side, the stock sits slightly expensive when compared with the wider JP Medical Equipment industry at 15.9x, which points to investors already paying a small premium relative to the broader group.
The contrast is clear. Against direct peers and the fair P/E level, the valuation looks restrained, yet versus the wider industry, the price is a touch richer. That mix implies the market is neither throwing Nipro away nor pricing it aggressively and may still be adjusting to its recent earnings rebound and one off gains.
Explore the SWS fair ratio for Nipro.
Result: Price-to-Earnings of 16x (ABOUT RIGHT)
Still, the recent 9.4% year to date share price decline and the 42.1% intrinsic premium suggest expectations could unwind quickly if earnings or clinical milestones disappoint.
Find out about the key risks to this Nipro narrative.
Another view on Nipro’s value
The P/E workup paints Nipro as roughly fairly priced, yet the SWS DCF model points the other way. On that framework, the current ¥1,350.5 quote sits well above an estimated future cash flow value of ¥950.06, which implies the stock trades on a premium rather than a discount. So which signal deserves more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
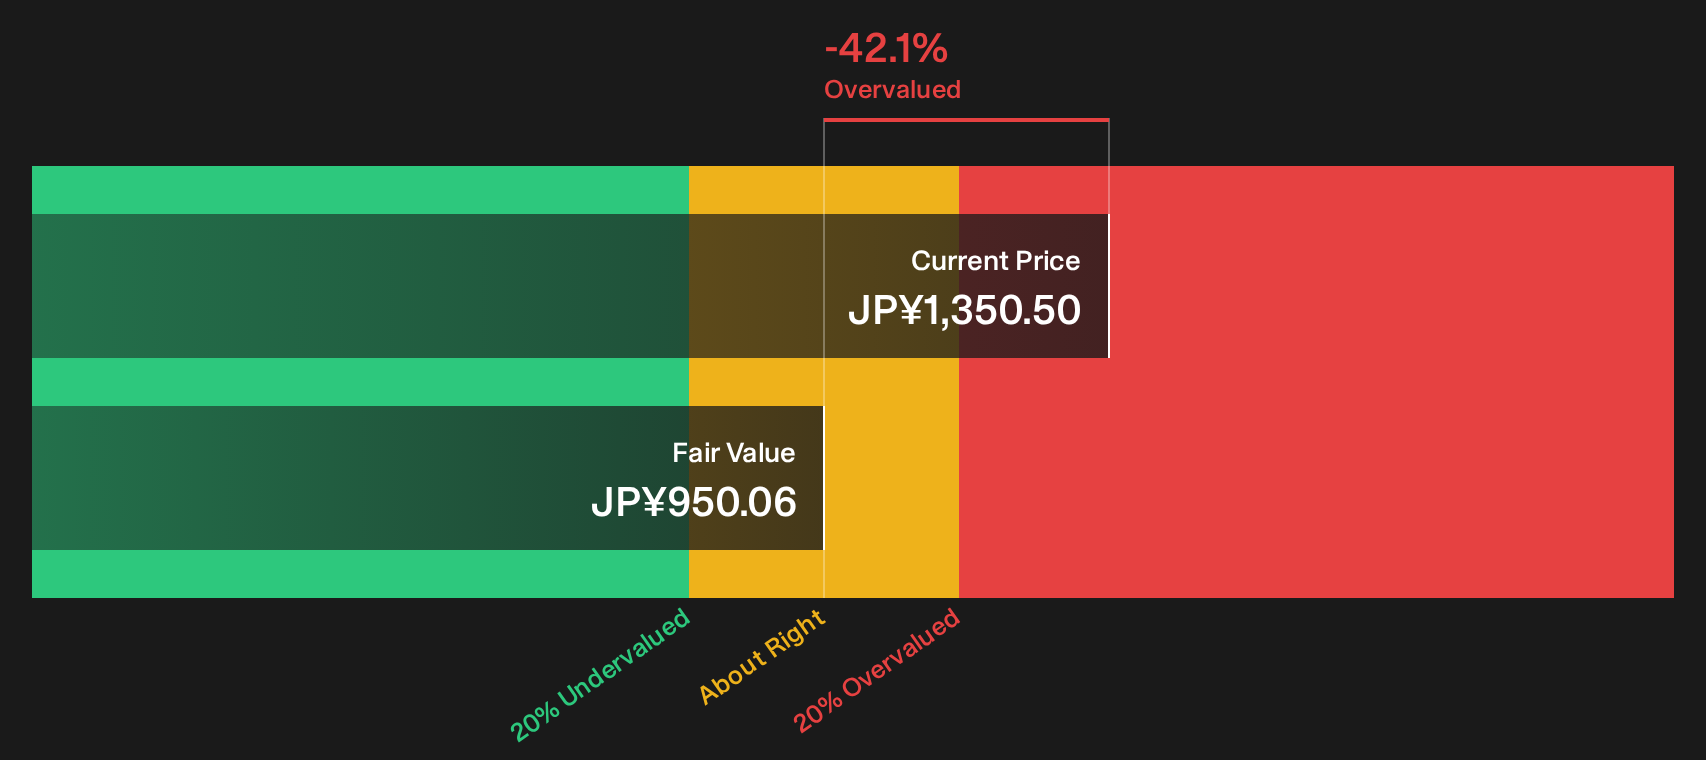
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nipro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Nipro so far? Act while the data is fresh, weigh the risks against the potential upsides, and review the 2 key rewards and 3 important warning signs.
Looking for more Nipro sized investment ideas?
Do not stop at Nipro. Use the Simply Wall St screener to uncover fresh opportunities that match your style before other investors move first.
- Target potential mispricings by scanning a curated set of quality companies through the 13 high quality undervalued stocks.
- Lock in income focused opportunities by reviewing a hand picked universe of resilient payers with the 27 dividend fortresses.
- Sleep easier by focusing on financially robust businesses using the 24 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com