


Costco Wholesale has delivered powerful share gains in recent years, and the question now is whether the cash flows behind the membership model are strong enough to back up today’s valuation. With the stock changing hands at US$959.44 at the last close, investors are asking how much of Costco’s future cash generation is already reflected in that price.
- Over the past 5 years, Costco Wholesale has returned 119.2%, which puts a lot of long term optimism about its underlying cash engine on the line.
- Recent double digit sales growth in September, helped by steady member renewal rates and traffic, can support expectations for future cash flows but also raises questions about how much of that performance comes from lower margin or one off drivers.
- If you'd rather focus on earnings, this one's for you. See what Costco Wholesale's 46.1x P/E says about the price.
The issue now is whether Costco Wholesale’s current share price is adequately supported by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
For context when weighing Costco Wholesale’s rich valuation against its cash flows, it can help to look at other companies screened for 29 high quality undervalued stocks.
Does Costco Wholesale Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Costco Wholesale’s projected cash generation and brings it back to today’s dollars. On this view, the latest twelve month free cash flow sits around $9.8b, with analyst and model projections indicating higher cash flows over the next decade rather than a shrinking profile.
The gap between those discounted cash flows and the current share price of US$959.44 points to the DCF estimate sitting meaningfully lower than where the stock trades today. Strong September sales and heavy traffic, helped by categories like gasoline and the food court, can support the long term cash story, yet the reliance on some lower margin or one off drivers helps explain why the cash flow model does not fully line up with the market price. Find out what Costco Wholesale could be worth using our Discounted Cash Flow (DCF) estimate.
The Costco Wholesale Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Costco Wholesale pick up where the DCF puzzle leaves off. They spell out which specific paths for growth, margins and earnings would need to play out for the stock to justify a meaningfully higher or lower price than today. Each one ties its number to a clear view on how Costco Wholesale's expansion, profitability and risk profile could evolve, giving you a reference point you can return to as fresh information arrives on the Community page.
Community views on Costco Wholesale split sharply between those who see more runway in the membership engine and those focused on valuation risk.
Bull case: 9% undervalued
"Rapid growth in traffic from AI search, which carries the highest conversion rate of any digital source and often leads directly to Costco memberships, together with triple digit growth in personalized digital sales, creates a data driven engine that can support higher revenue and membership fee income over time…"
Discover why this Narrative puts Costco Wholesale at 9% undervalued.
Bear case: 32% overvalued
"Based on my projections through 2031, Costco is priced for perfection. My Base Case (Mid) suggests an Annualized Return (IRR) of just 5.6%, largely because valuation compression is likely to offset operational growth…"
Explore why this Narrative puts Costco Wholesale at 32% overvalued.
One more Costco Wholesale signal that deserves your attention
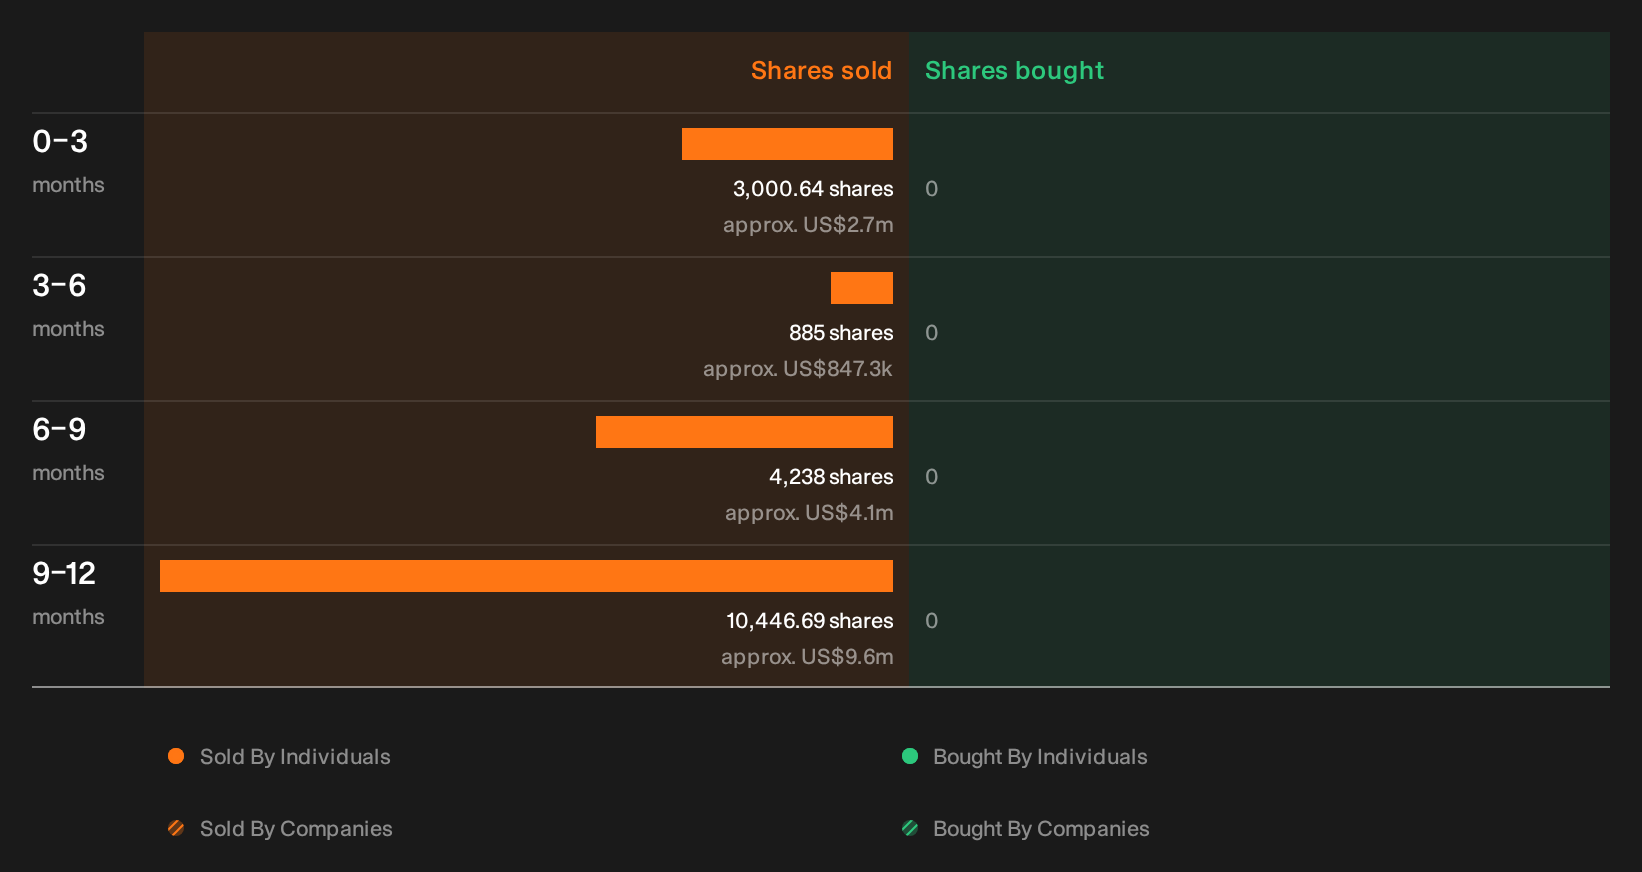
Cash flows and valuation tell only part of the story, because recent trading by Costco Wholesale insiders has been flagged and the specific sellers, sizes and possible read throughs are still for you to inspect. See the recent insider selling flagged for Costco Wholesale.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com