


- Honda Motor has agreed to sell Mitsubishi Motors' Thai-built Triton pickup trucks under the Honda brand across Southeast Asia, starting in 2028. This is expected to lift Triton volumes and support factory utilization for Mitsubishi.
- The move effectively turns Mitsubishi into a manufacturing and product partner for Honda in a key pickup region. It gives Mitsubishi added scale in a cost intensive vehicle segment while it is already viewed by some value screens as trading on relatively low P/B and P/S multiples.
- We will now look at how Mitsubishi's investment narrative intersects with this Honda Triton partnership and what that might imply.
Mitsubishi Investment Narrative Recap
To own Mitsubishi, you need to be comfortable with a conglomerate that leans on cyclical resource exposure while trying to build steadier earnings in areas like mobility, food and infrastructure. The near term story still hinges on execution in LNG and mineral resources, where commodity price swings can quickly reshape cash generation and segment profit.
The Honda Triton tie up plugs directly into the Mobility arm and may support scale, but it does not change the central risk around volatile resource and energy markets. The key watchpoint remains how quickly newer, more recurring businesses offset any weakness in legacy commodity linked operations.
The most relevant recent development for this story is how Mitsubishi screens on value. Zacks gives the stock an A grade for Value, and its P/B of 1.44 and P/S of 0.84 both sit below industry averages. That framing matters because the Honda Triton partnership speaks to using existing assets more efficiently rather than chasing premium multiples.
If the collaboration with Honda helps utilization and volumes in the wider mobility ecosystem, investors may pay closer attention to how Mitsubishi balances that against commodity exposed earnings. The value profile only stays attractive if management keeps capital discipline tight, grows high quality profit streams, and avoids letting cyclical shocks drive prolonged pressure on returns.
Mitsubishi earnings and revenue assumptions behind the Triton story
The stock story around Mitsubishi already comes with a clear set of analyst expectations. Revenue is assumed to rise by 4.9% a year over the next few years, with current earnings of ¥895.9b projected to reach ¥1,164.2b by 2029 as profit margins move from 4.5% to 5.1%. That implies an earnings increase of roughly ¥268.3b from today to the consensus forecast level.
Mitsubishi's narrative projects ¥22,926.6b revenue and ¥1,164.2b earnings by 2029. This requires 4.9% yearly revenue growth and an earnings increase of roughly ¥268.3b from current earnings of ¥895.9b.
Uncover how Mitsubishi's fair value indicates a 12% potential upside to its current price, which could narrow quickly if sentiment catches up.
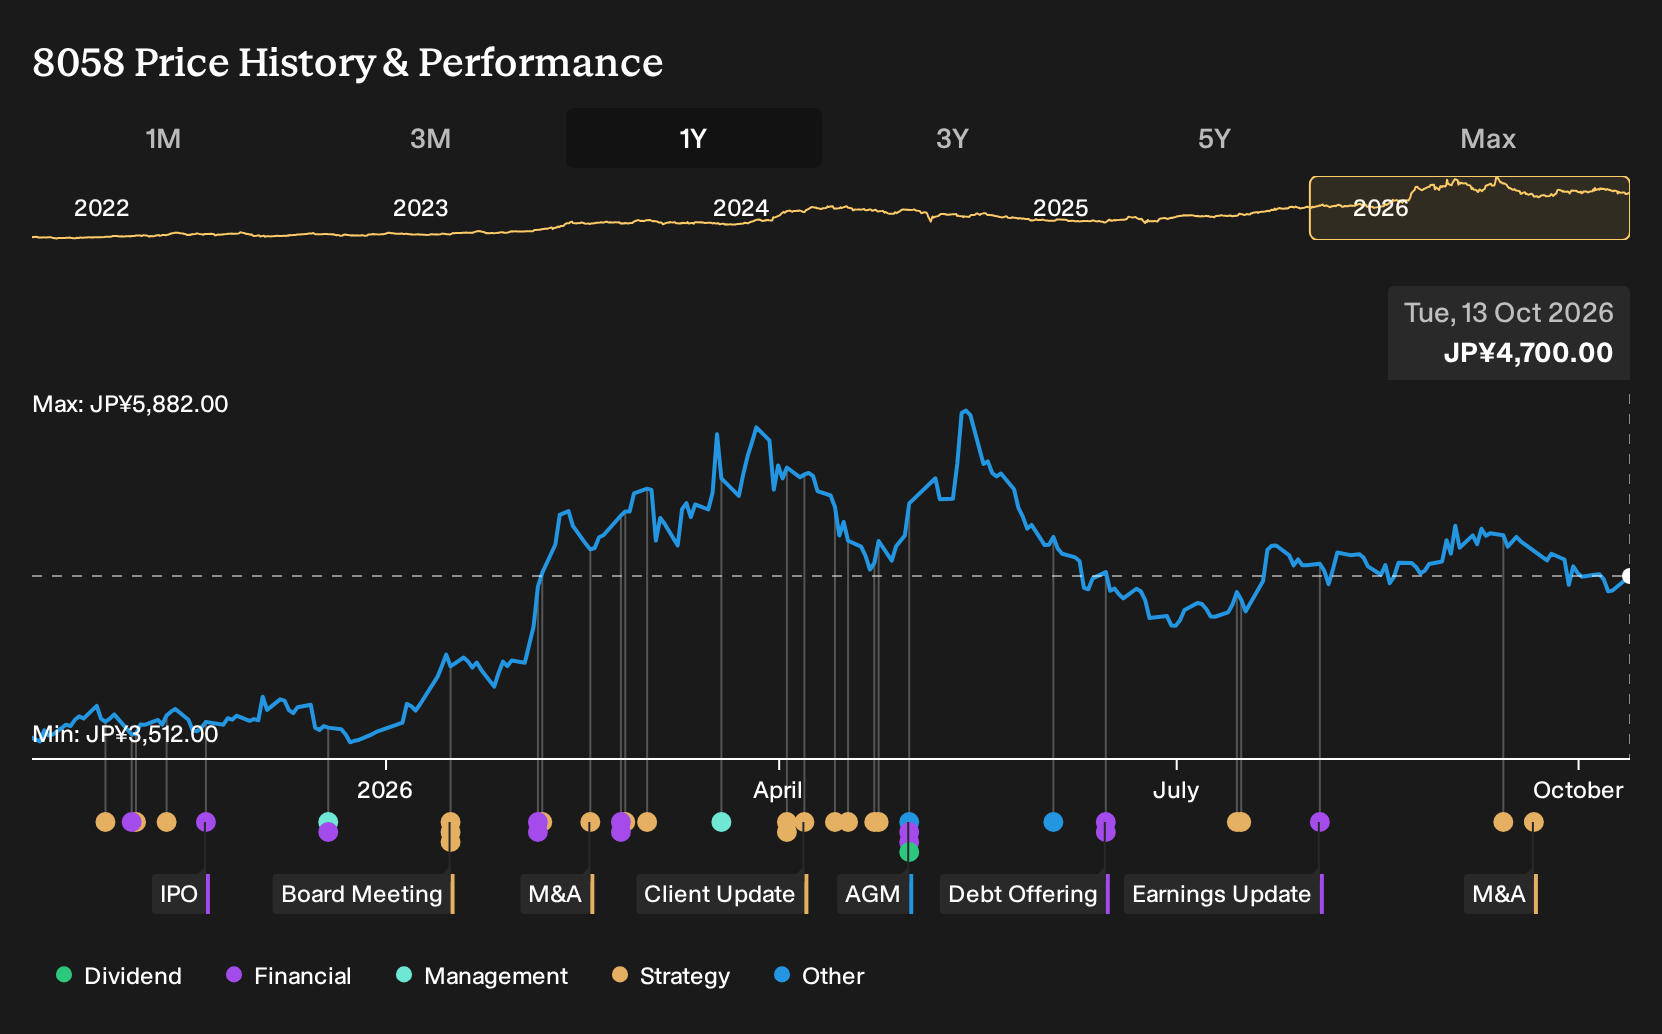
Exploring Other Perspectives
One alternate Mitsubishi angle you may want to consider focuses on aggressive buybacks rather than factory usage. The most optimistic analysts were already assuming 5.3% annual revenue growth and earnings of ¥1,140.2b by 2029, supported by shares declining 6.83% a year. Those forecasts came before this Honda Triton agreement, so expectations could shift meaningfully from here.
Explore 3 other Mitsubishi fair value estimates, including one that suggests up to 13% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mitsubishi research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mitsubishi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi's overall financial health at a glance.
Looking for more Mitsubishi sized investment ideas?
If the Mitsubishi Honda story has you thinking about where else value might be hiding, the Simply Wall St Screener can help you widen the field without losing focus on quality and fundamentals.
- For investors who care about steady balance sheets and cleaner financial risk, check out a list of solid balance sheet and fundamentals (21 results) that meet strict strength criteria.
- If capital protection is front of mind, filter for companies with more resilient profiles through a 24 resilient stocks with low risk scores that might better match your comfort level.
- When you want something a bit more off the radar, broaden your watchlist with a 74 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com